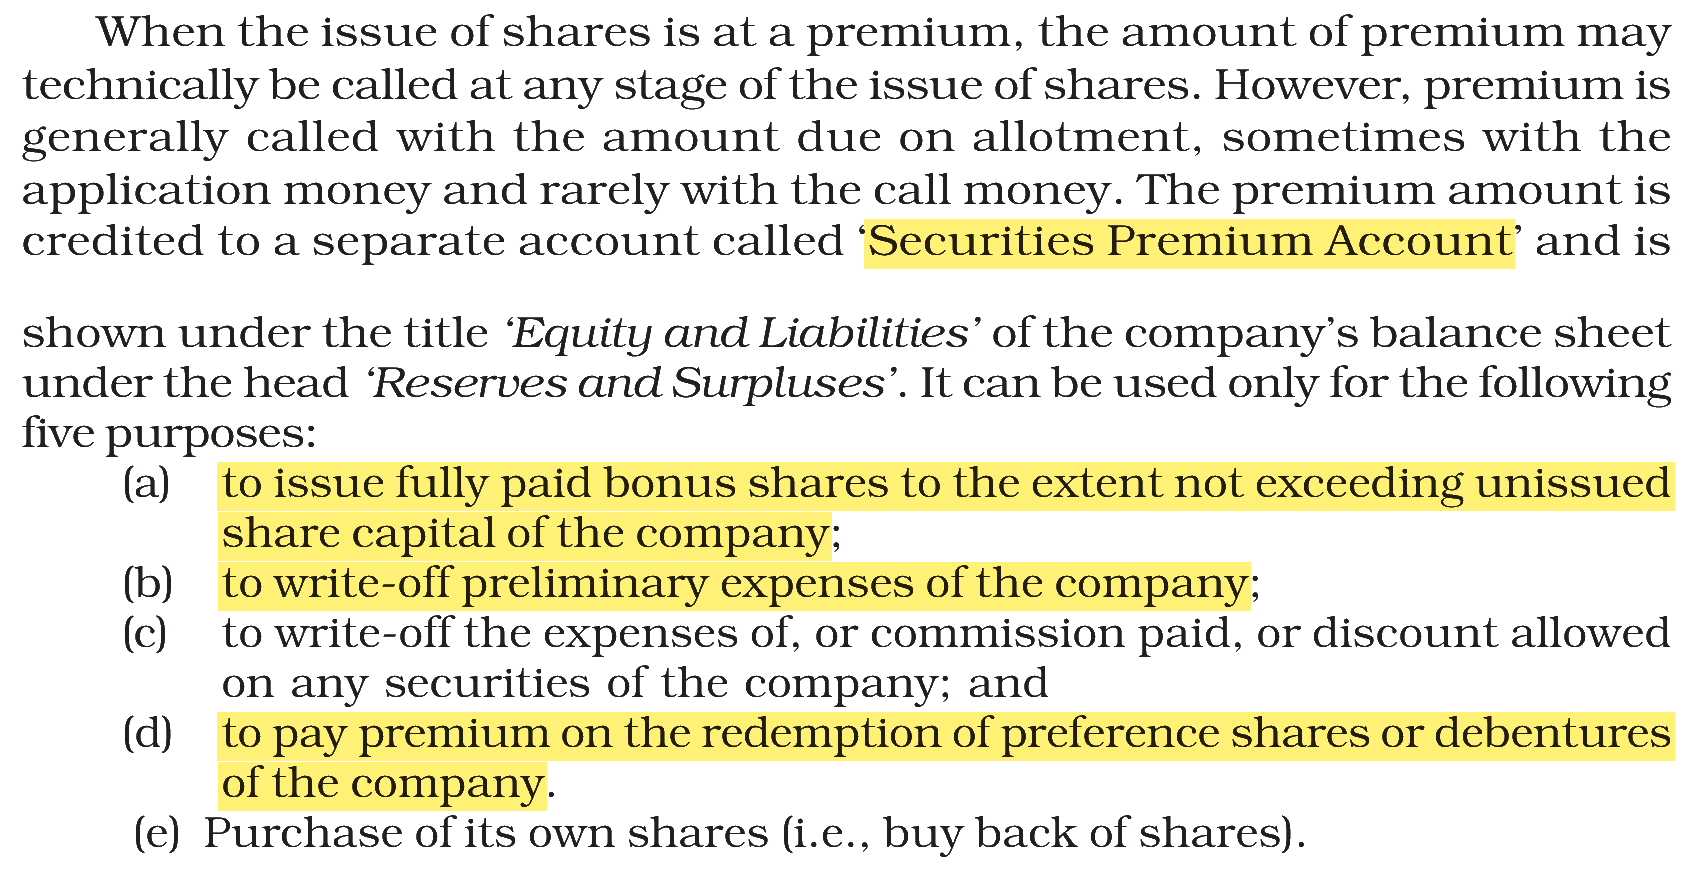
Securities Premium Reserve as per section 52(2) of the companies Act 2013 can be used :
(A) To write-off preliminary expenses of the company
(B) To issue fully paid bonus shares to the extent not exceeding unissued share capital of the company
(C) To pay premium on the redemption of preference shares or debentures
(D) To write off discount allowed on the goods sold on credit
Choose the correct answer from the options given below :
Answer & explanation
Correct answer: option 4
The correct answer is Option (4) → (A), (B) and (C) only
Section 52(2) of the Companies Act, 2013 allows the balance in Securities Premium to be used only for a few listed purposes.
(A) To write-off preliminary expenses of the company — Correct. Writing off preliminary expenses is one of the permitted uses.
(B) To issue fully paid bonus shares to the extent not exceeding unissued share capital of the company — Correct. Issuing fully paid bonus shares is a permitted use.
(C) To pay premium on the redemption of preference shares or debentures — Correct. Paying the premium on redemption of preference shares or debentures is a permitted use.
(D) To write off discount allowed on the goods sold on credit — Incorrect. Discount allowed to customers on goods sold is a revenue expense of the business, charged to the statement of profit and loss. Securities premium is capital in nature and cannot be used for it.
NCERT (2026-27 edition):
|