Read the following information to answer.
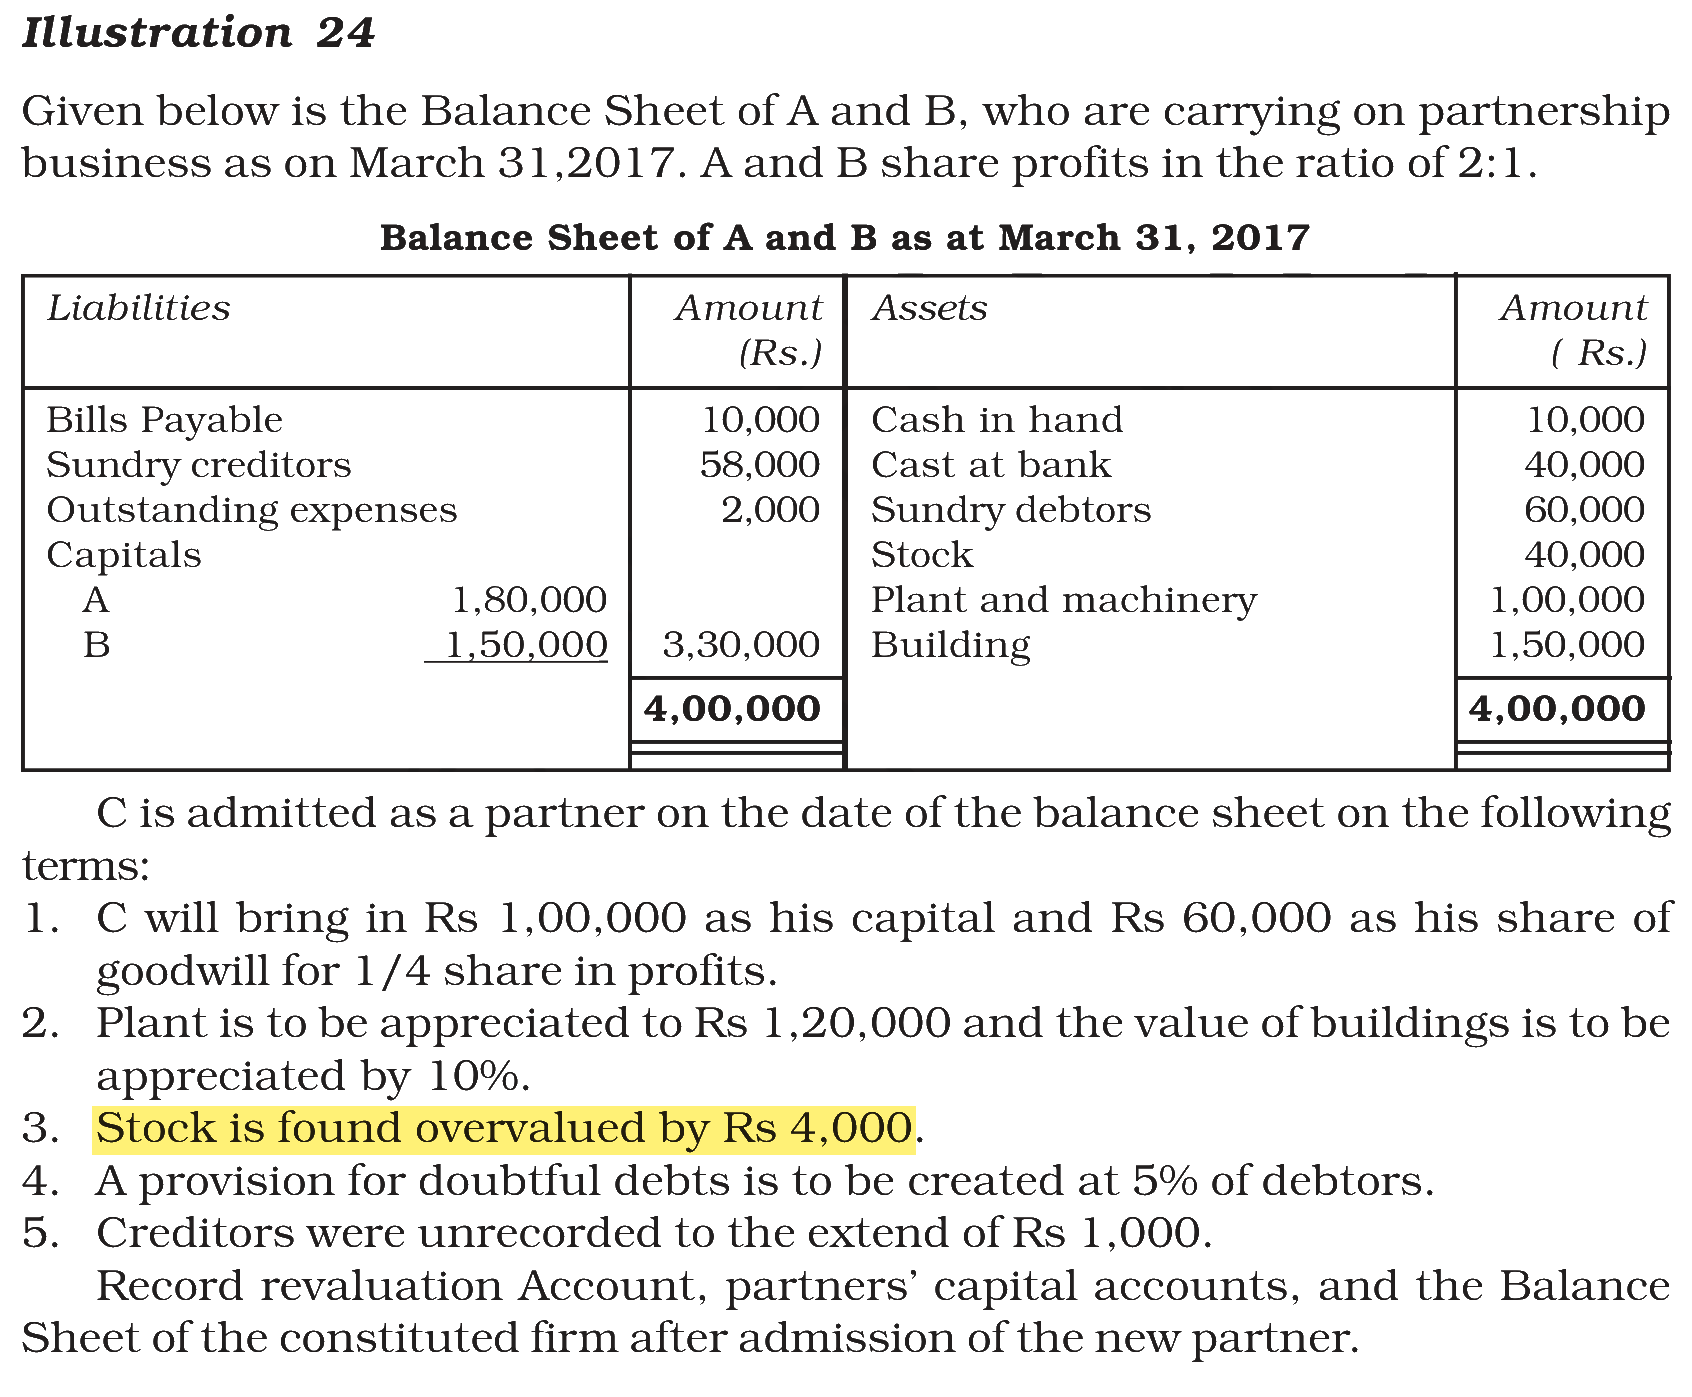
A and B are two partners, dealing in manufacturing steel, sharing profits in the ratio of 2 : 1. They enjoying a buoyant demand of its products as economic growth is about 7% - 8% and the demand for steel is growing. It is planned to set up a new steel plant to encash on the increasing demand. It is estimated that they will require about Rs. 1,00,000. So they admitted, C as a partner. On the date of admission Balance sheet is as follows.
Balance Sheet of A and B
| Liabilities | Rs. | Assets | Rs. |
|---|---|---|---|
| Bills Payable | 10,000 | Cash in hand | 10,000 |
| Sundry creditor | 58,000 | Cash at bank | 40,000 |
| Outstanding Expenses | 2,000 | Sundry Debtors | 60,000 |
| Capital | 3,30,000 | Stock | 40,000 |
| A - 1,80,000 | Plant and Machinery | 1,00,000 | |
| B - 1,50,000 | Building | 1,50,000 | |
| 4,00,000 | 4,00,000 |
Other information :
1. C will bring in Rs. 1,00,000 as capital and Rs. 60,000 as his share of goodwill for \( \displaystyle\frac{1}{4} \) share in profit.
2. Plant is to be appreciated to Rs. 1,20,000 and the value of building is to be appreciated by 10%.
3. Stock is found overvalued by Rs. 4,000.
4. A provision for doubtful debts is to be created at 5% of debtors.
5. Creditors were unrecorded to the extent of Rs. 1,000.
On the basis of above case study, answer the following :
Value of stock to be shown in Balance sheet after admission will be :
Answer & explanation
Correct answer: option 3
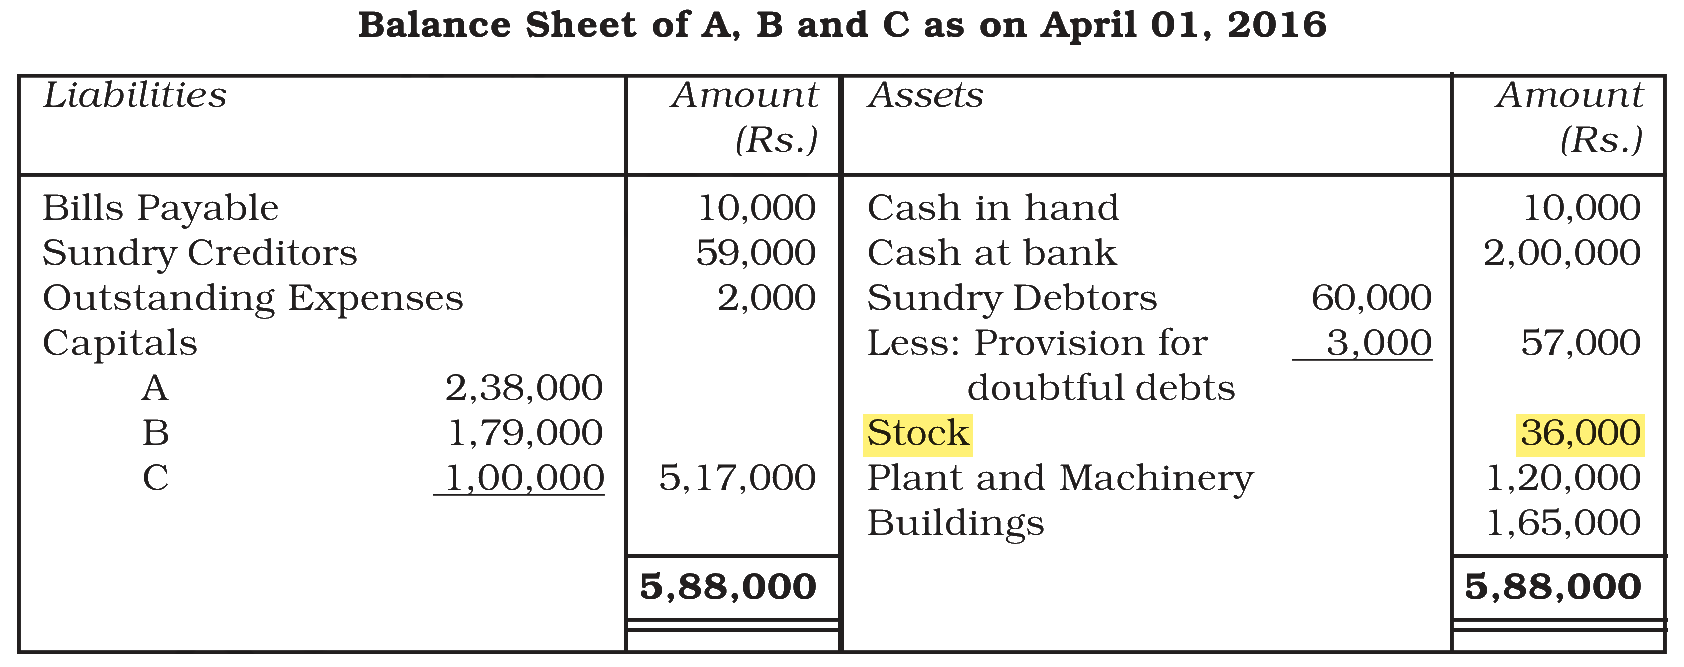
The correct answer is Option (3) → Rs. 36,000
On admission, assets are shown in the new balance sheet at their revised values. Stock that is overvalued is shown in the books at more than it is worth, so its value is brought down by the excess. The fall of Rs. 4,000 is a loss, debited to the Revaluation Account.
Stock as per balance sheet = Rs. 40,000
Less: Overvaluation = Rs. 4,000
Stock after admission = Rs. 40,000 − Rs. 4,000 = Rs. 36,000
NCERT (2026-27 edition):
|