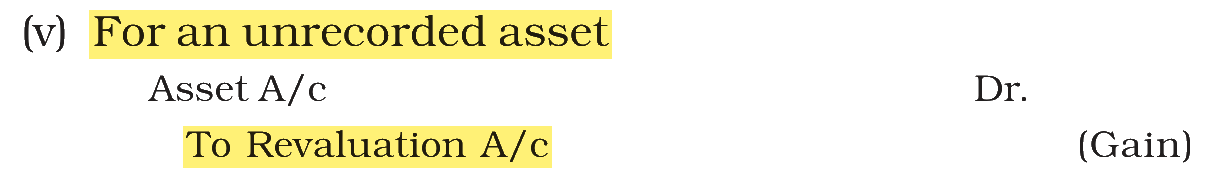
A, B and C are partners. They agreed to change their existing profit sharing ratio from 3:2:1 to 1:1:1. An unrecorded asset of Rs. 50,000 was identified. For this unrecorded asset:
Answer & explanation
Correct answer: option 3
The correct answer is Option (3) → Revaluation Account is Credited.
Note: The given answer is as per the official NTA Answer Key. However, the question does not say whether it asks only about the entry for the unrecorded asset or also about sharing the profit it creates, and with that reading Option (2) could also be a possible answer, as explained below.
A change in the profit sharing ratio among existing partners is treated like an admission: assets and liabilities are revalued. An unrecorded asset is a gain, so it is brought into the books by debiting the asset and crediting Revaluation Account. In the next step, the revaluation profit is shared by crediting the partners’ capital accounts in the old ratio 3 : 2 : 1.
Option (1) Revaluation Account is Debited — Incorrect. A debit to Revaluation Account records a loss, such as a fall in an asset or a rise in a liability.
Option (2) Partner's Capital Account is/are Credited — Should also be correct, though not the answer given by NTA. It is the next step in the working above, not the entry for the asset itself.
Option (3) Revaluation Account is Credited. — Correct. It is the entry for the asset itself, which the question asks about.
Option (4) Partner's Current Account is/are Credited — Incorrect. The revaluation profit goes to the capital accounts, not to the current accounts.
NCERT (2026-27 edition): NCERT (2026-27 edition):
|