The correct answer is Option (3) → Realisation Account
On dissolution, all external liabilities, creditors included, are closed by transfer to the credit side of the Realisation Account (Creditors A/c Dr. To Realisation A/c); their payment is later debited to the same account, so the account shows the net result of paying them off.
NCERT (2026-27 edition):
Accounting Treatment – “When the firm is dissolved, its books of account are to be closed and the profit or loss arising on realisation of its assets and discharge of liabilities is to be computed. For this purpose, a Realisation Account is prepared to ascertain the net effect (profit or loss) of realisation of assets and payment of liabilities which may be is transferred to partner’s capital accounts in their profit sharing ratio. Hence, all assets (other than cash in hand bank balance and fictitious assets, if any), and all external liabilities are transferred to this account.” NCERT (2026-27 edition):
Journal Entries 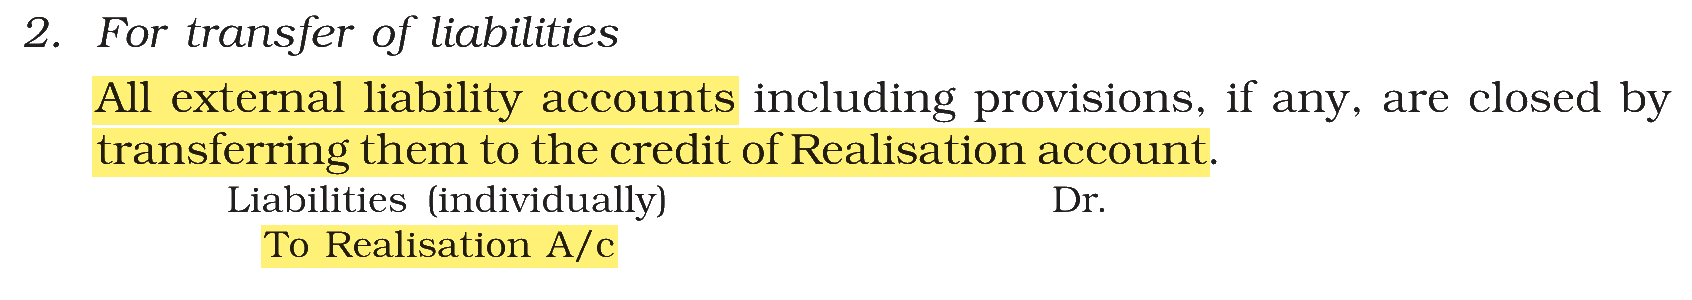
|
