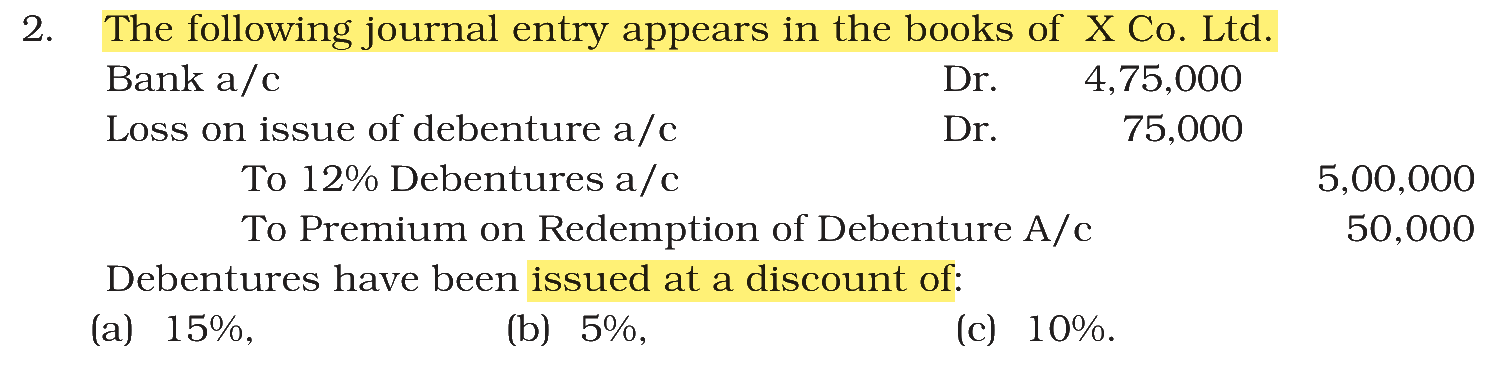
The following journal entry appears in the books of X Co. Ltd.
| Date | Particular | L.F | Dr (Rs.) | Cr (Rs.) |
| Bank a/c Dr. | 4,75,000 | |||
| Loss on issue of debenture a/c Dr. | 70,000 | |||
| To 12% Debentures A/c | 5,00,000 | |||
| To Premium on Redemption of Debenture A/c | 45,000 |
Debentures issued at discount of __________ and redeemable at a premium of __________.
Answer & explanation
Correct answer: option 3
The correct answer is Option (3) → Discount of 5% and Premium of 9%
When debentures are issued at a discount and redeemed at a premium, the Loss on Issue of Debentures A/c is debited with the discount on issue plus the premium on redemption. Each figure can be read back from the entry.
Premium on redemption:
Premium on Redemption A/c credited = Rs. 45,000
Rs. 45,000 ÷ Rs. 5,00,000 × 100 = 9%
Discount on issue:
Cash received (Bank) = Rs. 4,75,000 against a nominal value of Rs. 5,00,000
Discount = Rs. 5,00,000 − Rs. 4,75,000 = Rs. 25,000
Rs. 25,000 ÷ Rs. 5,00,000 × 100 = 5%
Check:
Loss on issue = Rs. 25,000 + Rs. 45,000 = Rs. 70,000, as in the entry
Note: NTA picked this question from an NCERT (2026-27) exercise and changed the figures. Do not ignore NCERT while practising numericals.
NCERT (2026-27 edition):
|