From the information provided below, calculate various questions asked in questions.
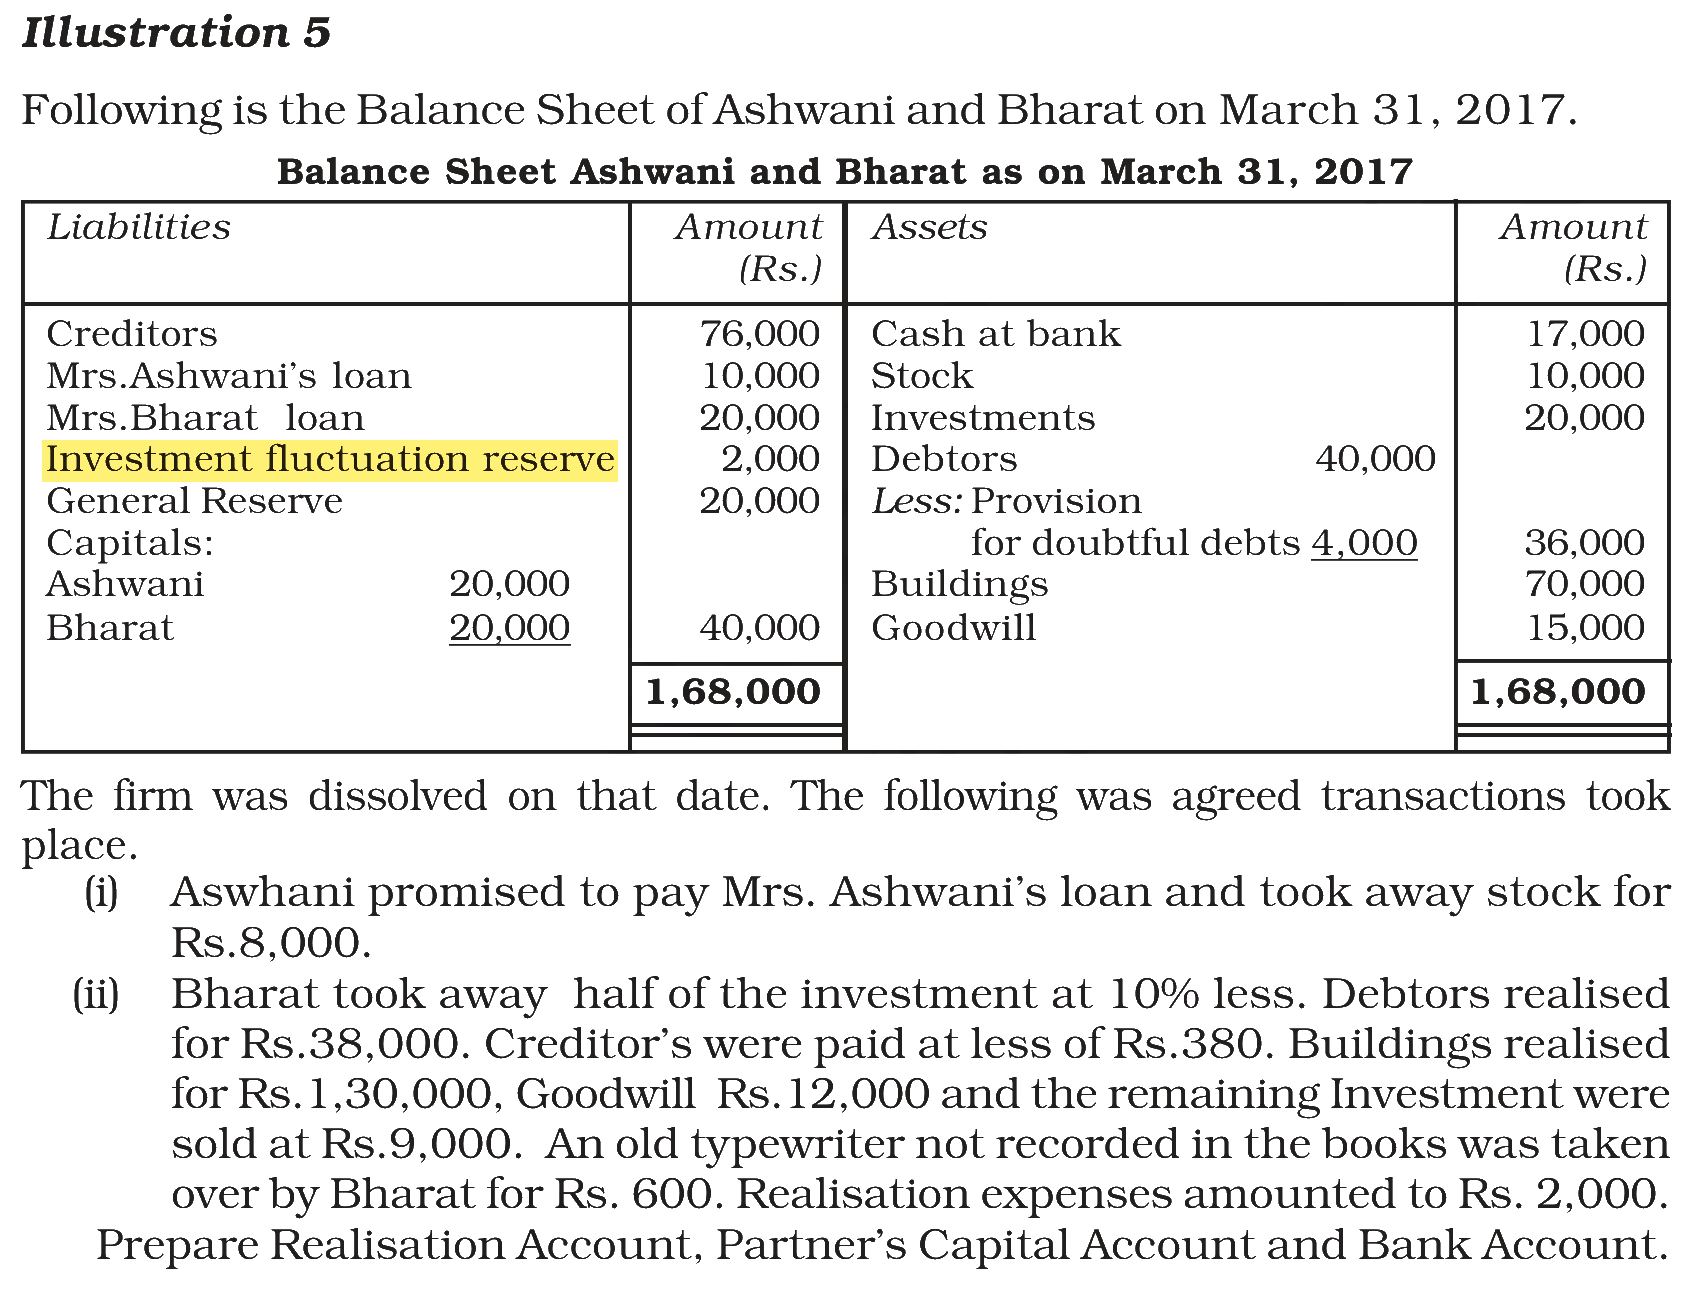
Following is the Balance Sheet of Ashwani and Bharat on March 31, 2024.
Balance Sheet Ashwani and Bharat as on March 31, 2024
|
Liabilities |
Amount (₹) |
Assets |
Amount (₹) |
| Creditors | 76,000 | Cash at bank | 17,000 |
| Mrs. Ashwani's loan | 10,000 | Stock | 10,000 |
| Mrs. Bharat loan | 20,000 | Investments | 20,000 |
| Investment fluctuation reserve | 2,000 | Debtors- 40,000 Less: Provision for doubtful debts 4,000 |
36,000 |
| General Reserve | 20,000 | Buildings | 70,000 |
| Capitals: Ashwani- 20,000 Bharat - 20,000 |
40,000 | Goodwill | 15,000 |
| Total | 1,68,000 | Total | 1,68,000 |
The firm was dissolved on that date. The following was agreed transactions took place.
(i) Aswhani promised to pay Mrs. Ashwani's loan and took away stock for ₹8,000.
(ii) Bharat took away half of the investment at 10% less. Debtors realised for ₹38,000. Creditor's were paid at less of ₹380. Buildings realised for ₹1,30,000, Goodwill ₹12,000 and the remaining Investment were sold at ₹9,000. An old typewriter not recorded in the books was taken over by Bharat for ₹600. Realisation expenses amounted to ₹2,000.
Investment Fluctuation Reserve will be:
Answer & explanation
Correct answer: option 2
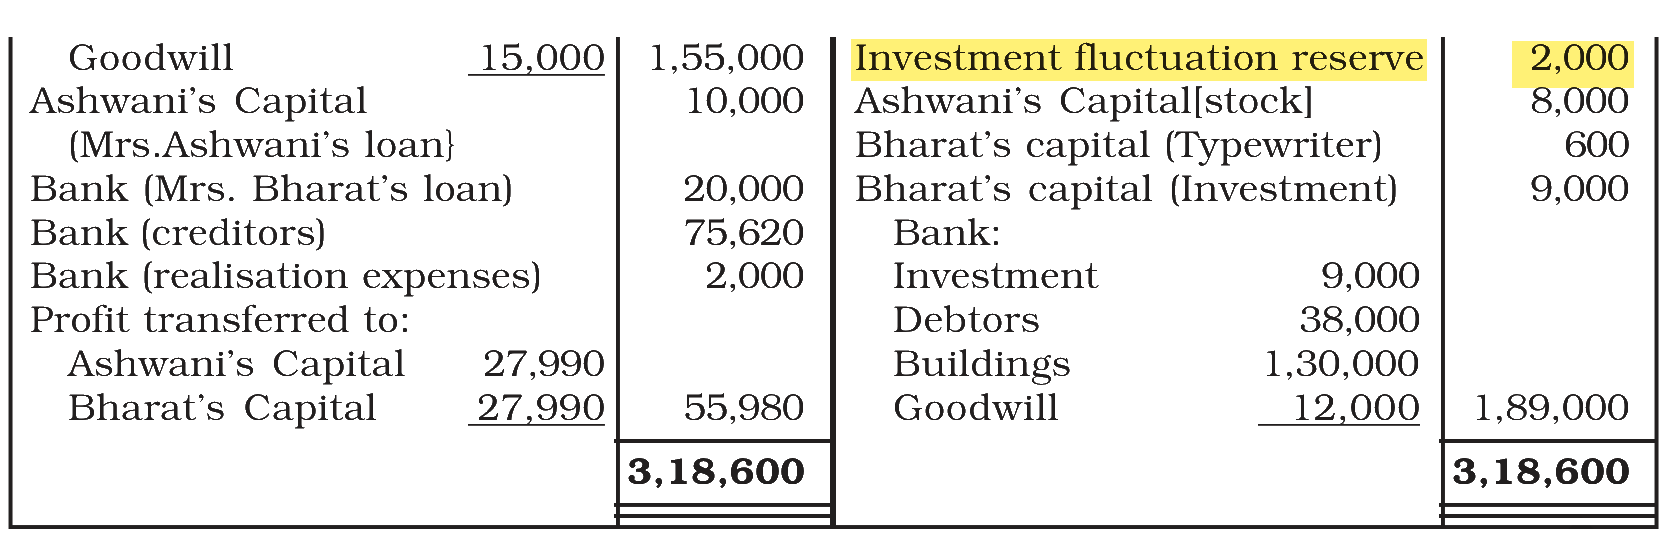
The correct answer is Option (2) → Transferred to credit side of realization A/c
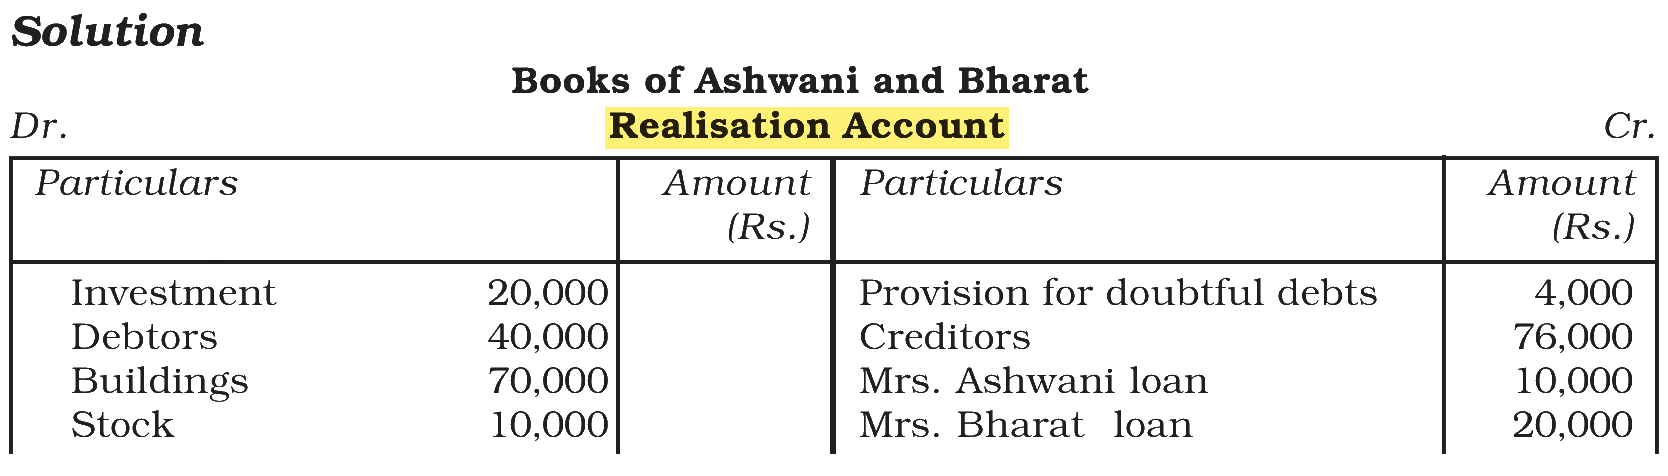
An Investment Fluctuation Reserve is set aside against a possible fall in the value of the investments. On dissolution the investments themselves are transferred to the debit of the Realisation Account at their book value, so the reserve kept against them goes to the credit side of the Realisation Account. The gain or loss on the investments is then worked out there, along with every other asset.
Why the other options are incorrect:
Option (1) Transferred to debit side of realization A/c — Incorrect. The reserve is a credit balance in the books; the debit side of the Realisation Account receives the assets and the payments, not the reserves.
Option (3) Distributed amongst partners in profit sharing ratio — Incorrect. Only free reserves such as the General Reserve (₹20,000 here) are credited to the partners’ capital accounts. This reserve is tied to the investments and is settled through the Realisation Account.
Option (4) Subtracted from Value of Investment — Incorrect. The investments are transferred to the Realisation Account at their full book value of ₹20,000; the reserve is not netted off against them.
NCERT (2026-27 edition):
|