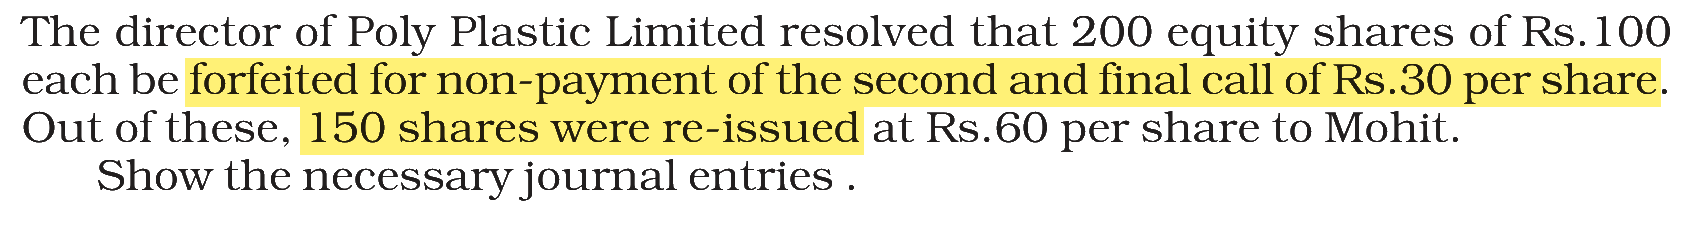
The directors of Roly Paper Limited decided that 400 equity shares of Rs. 100 each be forfeited for non-payment of the second and final call of Rs. 30 per share. Out of these, 150 shares were re-issued at Rs. 50 per share to Mohita. Necessary journal entry for Profit on reissue forfeited shares transferred to capital reserve will be?
Answer & explanation
Correct answer: option 2
The correct answer is Option (2) → Shares Forfeiture A/c Dr. 3,000, To Capital Reserve A/c 3,000
When forfeited shares are reissued, the discount allowed on reissue is charged to Shares Forfeiture A/c. What is left of the forfeited amount on the reissued shares only is a capital profit, and it is transferred to Capital Reserve.
Amount received on each forfeited share = Rs. 100 − Rs. 30 unpaid on the final call = Rs. 70
Discount on reissue = Rs. 100 − Rs. 50 = Rs. 50 per share
Profit on each reissued share = Rs. 70 − Rs. 50 = Rs. 20
Profit on 150 reissued shares = 150 × Rs. 20 = Rs. 3,000
The Rs. 17,500 (250 shares × Rs. 70) on the 250 shares not yet reissued stays in Shares Forfeiture A/c. It is not a capital profit until those shares are reissued.
Note: NTA picked this question from an NCERT (2026-27) illustration and changed the figures. Do not ignore NCERT while practising numericals.
NCERT (2026-27 edition):
|