Arrange the following steps in the order of the accounting treatment in case of death of a partner.
(A) Adjustment of capital account of the existing partner.
(B) Transfer of share of goodwill to deceased partner's capital account.
(C) Transfer of amount from deceased partner's capital account to executor's account.
(D) Calculation of New Profit Ratio and Sacrificing Ratio.
Choose the correct answer from the options given below:
Answer & explanation
Correct answer: option 2
The correct answer is Option (2) → (D), (B), (A), (C)
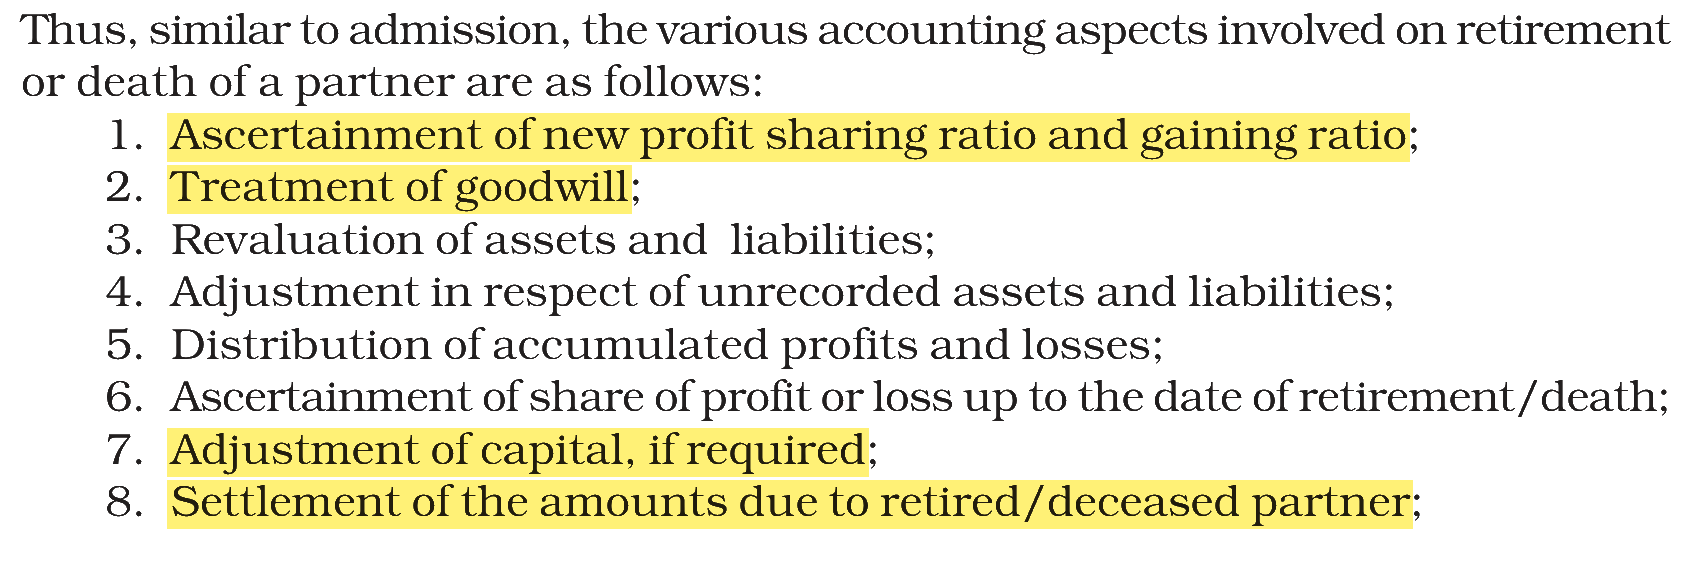
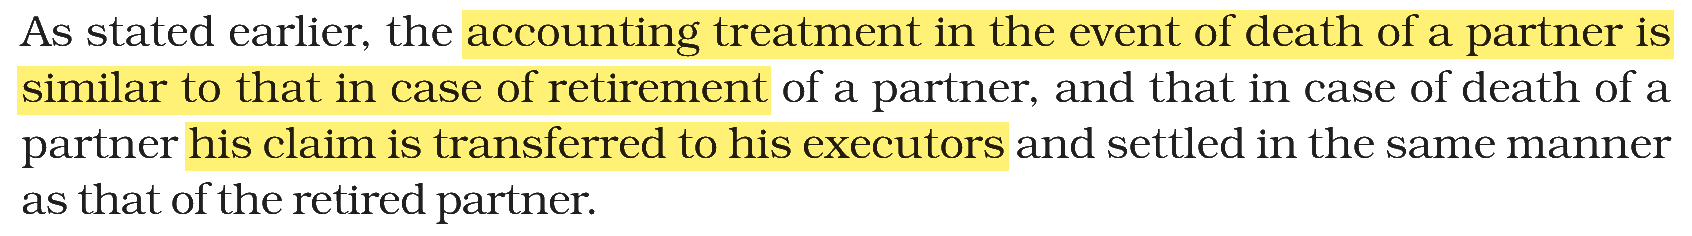
The book treats the death of a partner in the same way as retirement, so the steps follow its list of accounting aspects on retirement or death.
(D) Calculation of New Profit Ratio and Sacrificing Ratio. — item 1 of the book's list. On death, the ratio that matters is the continuing partners' gaining ratio (the book's word). The ratios come first, because the goodwill adjustment is made in the ratio in which the continuing partners gain.
(B) Transfer of share of goodwill to deceased partner's capital account. — item 2, treatment of goodwill. The deceased partner is credited with his share of goodwill, debited to the gaining partners in the ratio found in (D).
(A) Adjustment of capital account of the existing partner. — item 7, adjustment of capital, if required. It comes after goodwill, revaluation and reserves have been dealt with.
(C) Transfer of amount from deceased partner's capital account to executor's account. — item 8, settlement of the amount due, the last step. Once all adjustments are made, the balance in the deceased partner's capital account is transferred to his executor's account for payment.
NCERT (2026-27 edition):
NCERT (2026-27 edition):
|