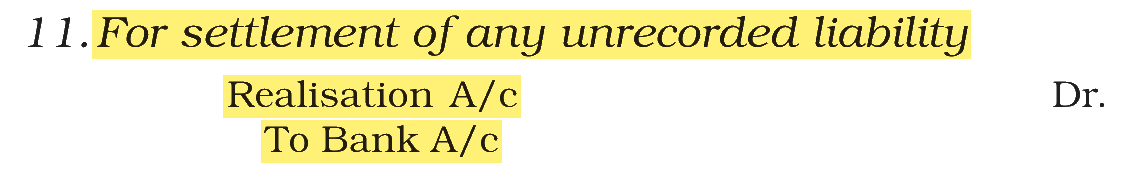Match List-I (Dissolution Transactions) with List-II (Journal Entry)
List-I
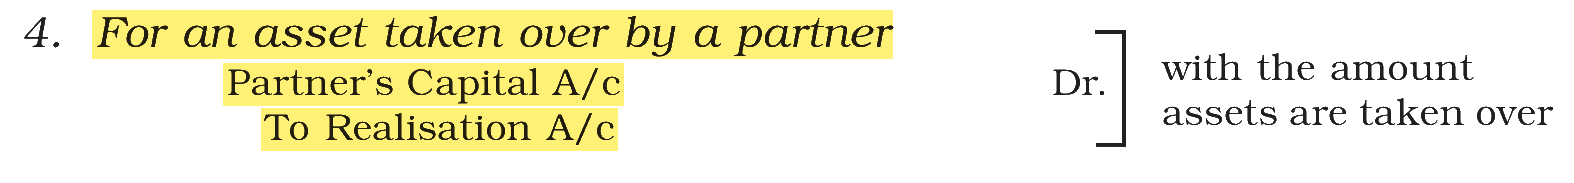
(A) For an asset taken over by a partner
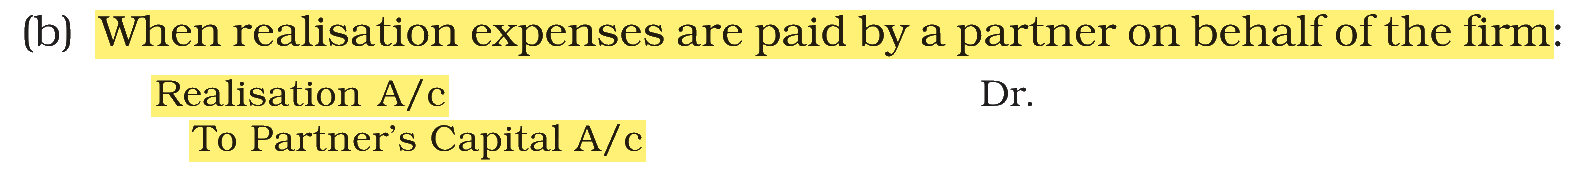
(B) Realisation expenses are paid by a partner on behalf of the firm
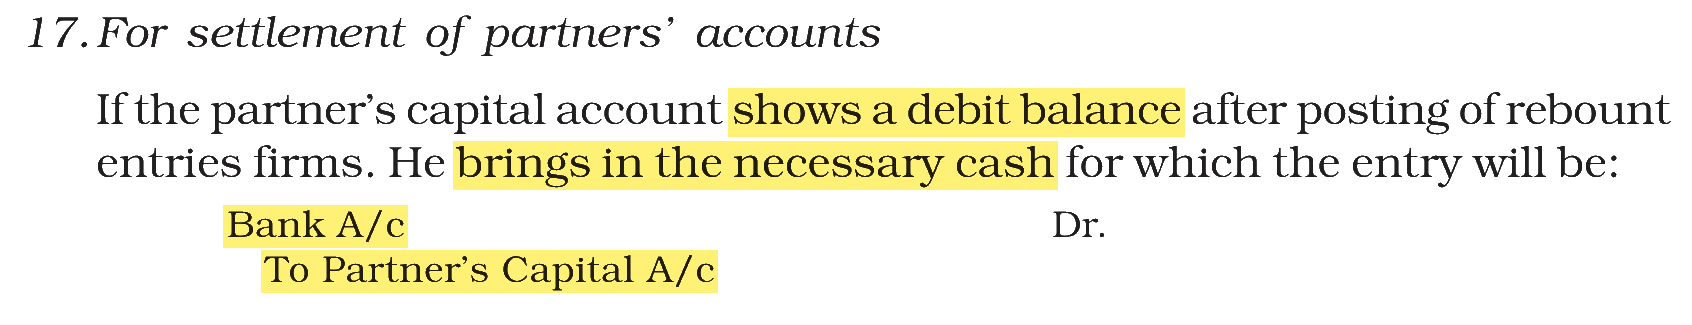
(C) For settlement of partners' accounts if the partner's capital account shows a debit balance
(D) For settlement of any unrecorded liability
List-II
(I) Bank A/c Dr.
To Partner's Capital A/c
(II) Partner's Capital A/c Dr.
To Realisation A/c
(III) Realisation A/c Dr.
To Bank A/c
(IV) Realisation A/c Dr.
To Partner's Capital A/c
Choose the correct answer from the options given below:
Answer & explanation
Correct answer: option 1
The correct answer is Option (1) → (A) - (II), (B) - (IV), (C) - (I), (D) - (III)
On dissolution, the Realisation Account is debited with assets and with everything the firm pays out, and credited with liabilities and everything the firm receives. A partner's capital account is credited when the partner gives the firm something and debited when he takes something from it.
(A) For an asset taken over by a partner — this matches (II) Partner's Capital A/c Dr. To Realisation A/c. The partner takes value out of the firm, so his capital is debited, and the Realisation Account is credited as if the asset had been sold to him.
(B) Realisation expenses are paid by a partner on behalf of the firm — this matches (IV) Realisation A/c Dr. To Partner's Capital A/c. The expense is the firm's, so it is debited to Realisation, and the partner who paid it is credited.
(C) For settlement of partners' accounts if the partner's capital account shows a debit balance — this matches (I) Bank A/c Dr. To Partner's Capital A/c. A debit balance means the partner owes the firm, so he brings in cash to close his account.
(D) For settlement of any unrecorded liability — this matches (III) Realisation A/c Dr. To Bank A/c. The liability was not in the books, so its payment is a loss on realisation, debited to the Realisation Account and paid from the bank.
NCERT (2026-27 edition):
|