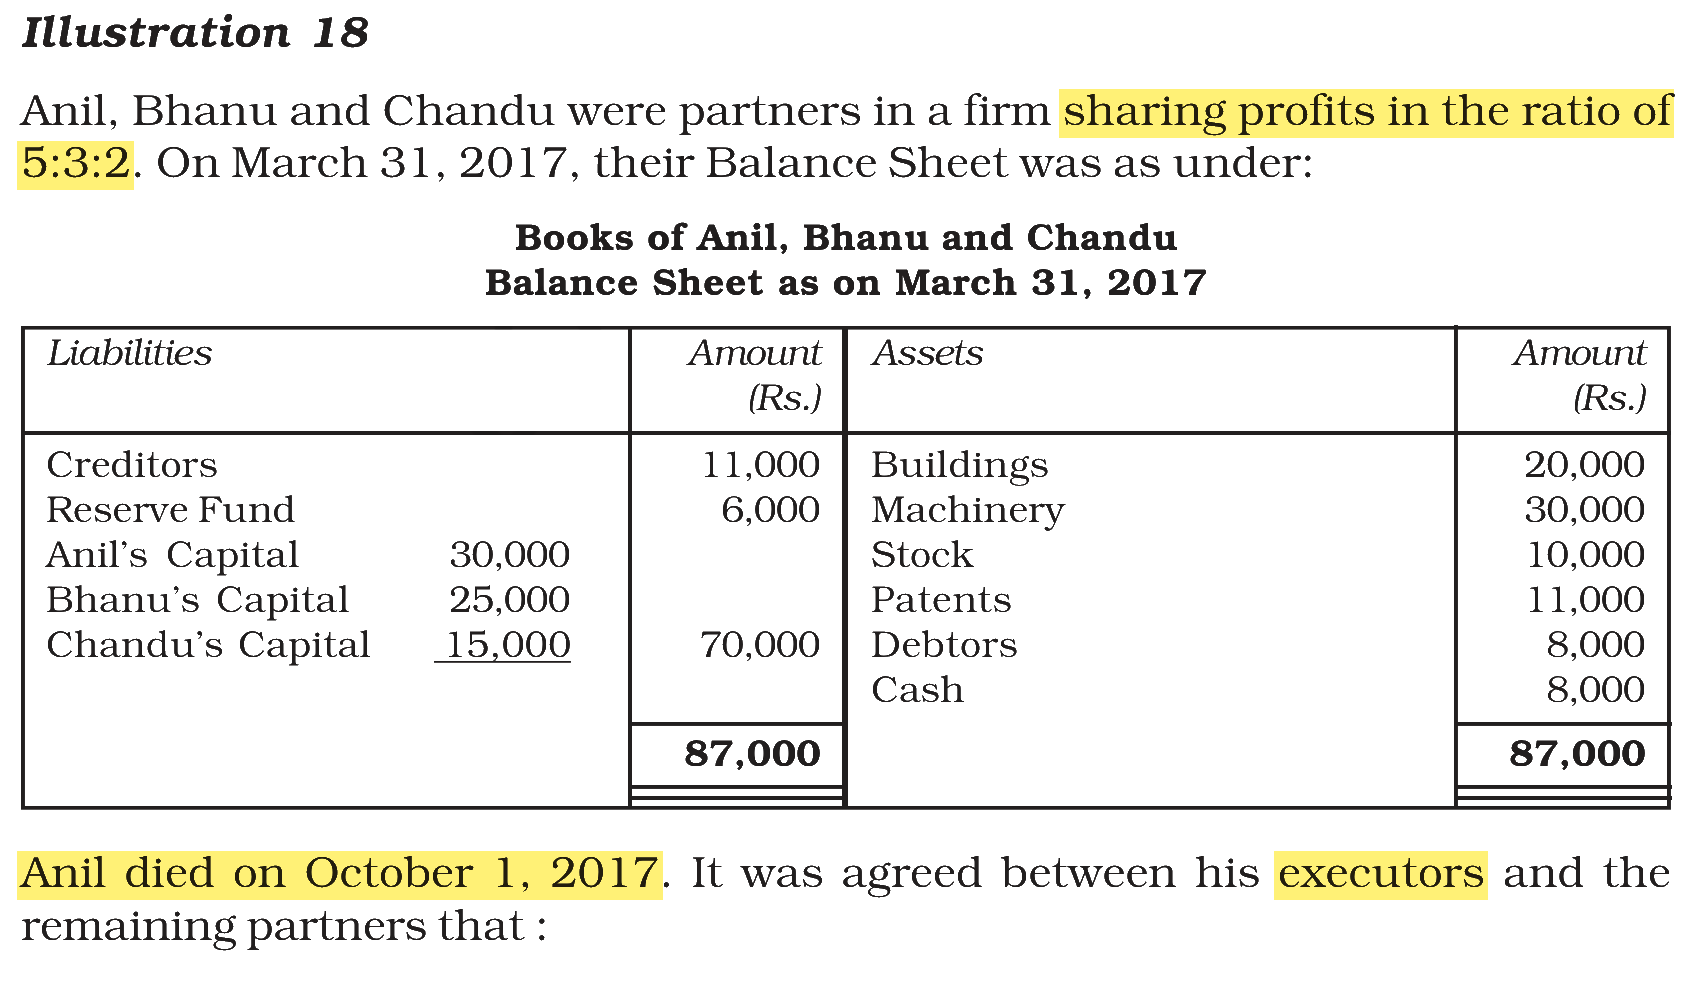
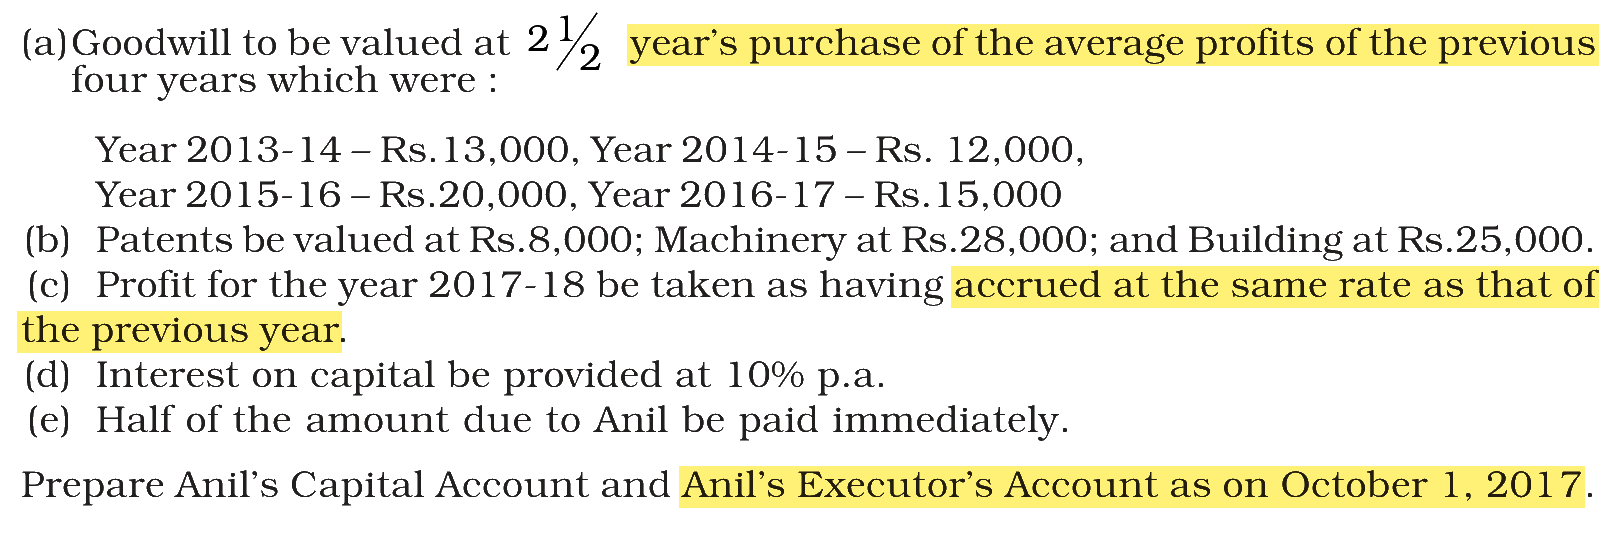
A, B and C were partners in a firm sharing profits in the ratio of 5:3:2. On March 31, 2025 the balance sheet of the firm shows the capital balance of Rs. 30,000, Rs. 25,000, and Rs. 15,000 respectively with a accumulated losses of Rs. 30,000. A died on October 1, 2025. It was agreed between his executors and the remaining partners that the profit for the year 2025-26 be taken as having accrued at the same rate as that of the previous year. Goodwill to be valued at 2.5 year's purchase of the average profits of the previous four years which were: Year 2021-22 – Rs. 13,000; Year 2022-23 – Rs. 12,000; Year 2023-24 – Rs. 20,000; Year 2024-25 – Rs. 15,000. Calculate the amount due to A's executor based on the above information.
Answer & explanation
Correct answer: option 4
The correct answer is Option (4) → Rs. 37,500
On the death of a partner, the amount due to his executor is his capital, adjusted for his share of accumulated losses, goodwill and profit up to the date of death. A died on October 1, so his share of profit is for six months, at the rate of the previous year's profit.
A's capital = Rs. 30,000
Less A's share of accumulated losses = Rs. 30,000 × 5/10 = Rs. 15,000
Average profit = (Rs. 13,000 + Rs. 12,000 + Rs. 20,000 + Rs. 15,000) ÷ 4 = Rs. 15,000
Goodwill = Rs. 15,000 × 2.5 = Rs. 37,500
Add A's share of goodwill = Rs. 37,500 × 5/10 = Rs. 18,750
Profit for 2025-26 at last year's rate = Rs. 15,000 × 6/12 = Rs. 7,500
Add A's share of profit = Rs. 7,500 × 5/10 = Rs. 3,750
Amount due to A's executor = Rs. 30,000 − Rs. 15,000 + Rs. 18,750 + Rs. 3,750 = Rs. 37,500
The accumulated losses are a debit that A shares in the old ratio, so they reduce his claim; leaving them out would add Rs. 15,000 to the answer.
Note: NTA picked this question from an NCERT (2026-27) illustration and changed the figures. Do not ignore NCERT while practising numericals.
NCERT (2026-27 edition):
|