Match the LIST-I with LIST-II
| LIST-I Transections | LIST-II Journal Entry | ||
|---|---|---|---|
| A. | For payment to outsider's liabilities (Third party) | I. | Partner's Loan A/c Dr. To Cash / Bank A/c |
| B. | Realisation Expenses are borne by a Partner | II. | Partner's Capital A/c Dr. To Realisation A/c |
| C. | If the Assets are taken over by any partner | III. | Realisation A/c Dr. To Partner's Capital A/c |
| D. | Payment of partner's loan account | IV. | Realisation A/c. Dr. To Cash / Bank A/c |
Choose the correct answer from the options given below:
Answer & explanation
Correct answer: option 4
The correct answer is Option (4) → A-IV, B-III, C-II, D-I
On dissolution, assets and outside liabilities are closed through the Realisation Account, while anything between the firm and a partner passes through the partner's own capital or loan account.
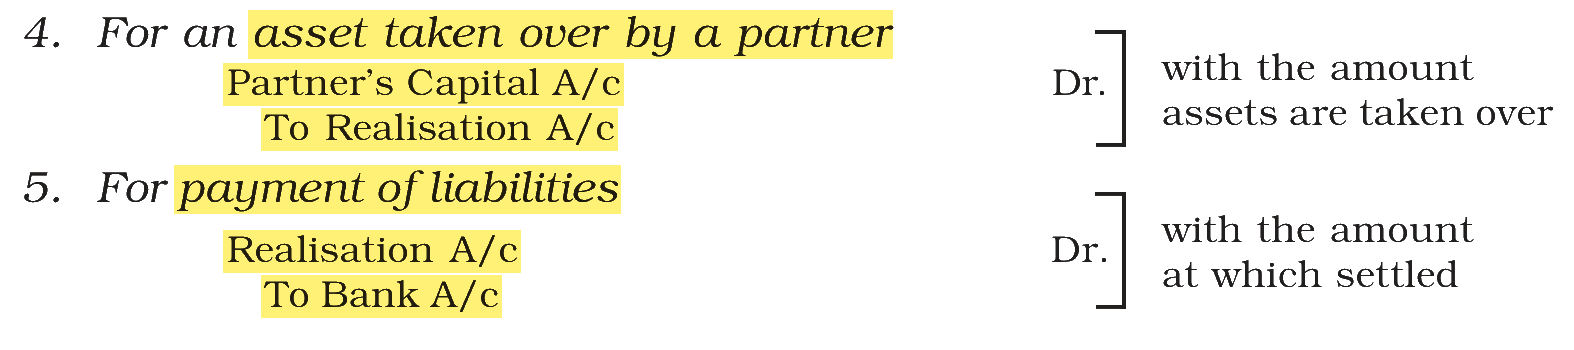
(A) For payment to outsider's liabilities (Third party) — this matches (IV) Realisation A/c. Dr. To Cash / Bank A/c. Outside liabilities have already been moved to the credit of Realisation Account, so their payment is debited to Realisation Account.
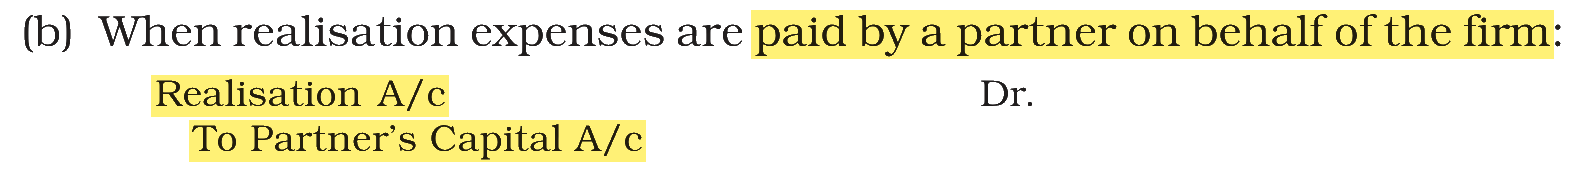
(B) Realisation Expenses are borne by a Partner — this matches (III) Realisation A/c Dr. To Partner's Capital A/c. This is the entry when a partner pays the realisation expenses on behalf of the firm: the expense is a debit to Realisation Account and the partner who paid is credited.
(C) If the Assets are taken over by any partner — this matches (II) Partner's Capital A/c Dr. To Realisation A/c. The partner takes the asset instead of cash, so his capital is debited with the value of the asset and Realisation Account is credited.
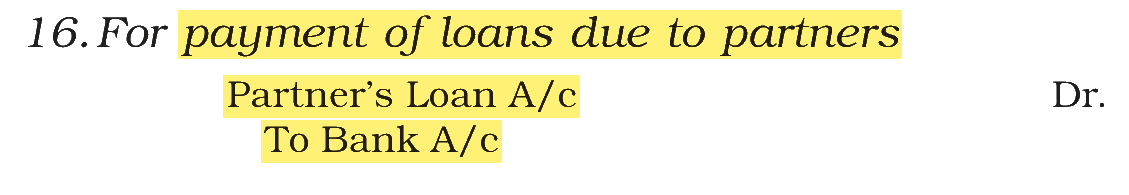
(D) Payment of partner's loan account — this matches (I) Partner's Loan A/c Dr. To Cash / Bank A/c. A partner's loan is not sent to the Realisation Account; it is paid off directly after the outside liabilities.
Note: It seems that there is a mistake in the original NTA paper, which prints item (B) as “Realisation Expenses are borne by a Partner” when it should read “Realisation Expenses are paid by a Partner”. When a partner has agreed to bear the expenses and the firm pays them, the entry is Partner's Capital A/c Dr. To Bank A/c, and if he pays them himself no entry is passed; entry (III) is the entry for expenses paid by a partner on behalf of the firm. Items (A), (C) and (D) have only one possible match each, so Option (4) is still the only possible answer.
NCERT (2026-27 edition):
|