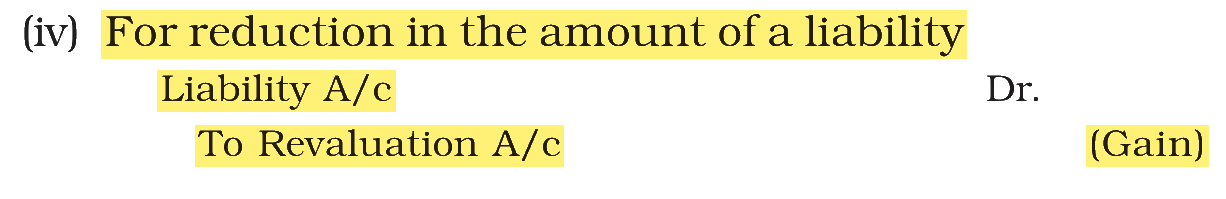"At the time of admission of a partner, provision for doubtful debts is found to be in excess."
Record this in the books of the firm.
Answer & explanation
Correct answer: option 3
The correct answer is Option (3) → Provision for doubtful debts A/c Dr, To Revaluation A/c
On admission, assets and liabilities are brought to their present values through the Revaluation Account: a gain is credited to it and a loss is debited. A provision for doubtful debts is kept for the bad debts expected from the debtors, so on revaluation it is handled like a liability. When the provision is more than now needed and is cut down, that is a reduction in the amount of a liability, and a reduction in a liability is a gain on revaluation.
The provision, like a liability, goes down by the excess, so Provision for Doubtful Debts A/c is debited
The same amount is credited to Revaluation A/c as a gain
The net gain on the Revaluation Account later goes to the old partners in the old ratio
The gain does not go straight to the partners’ capital accounts; it reaches them only when the Revaluation Account is closed.
NCERT (2026-27 edition): NCERT (2026-27 edition):
|