Answer the questions from the passage-
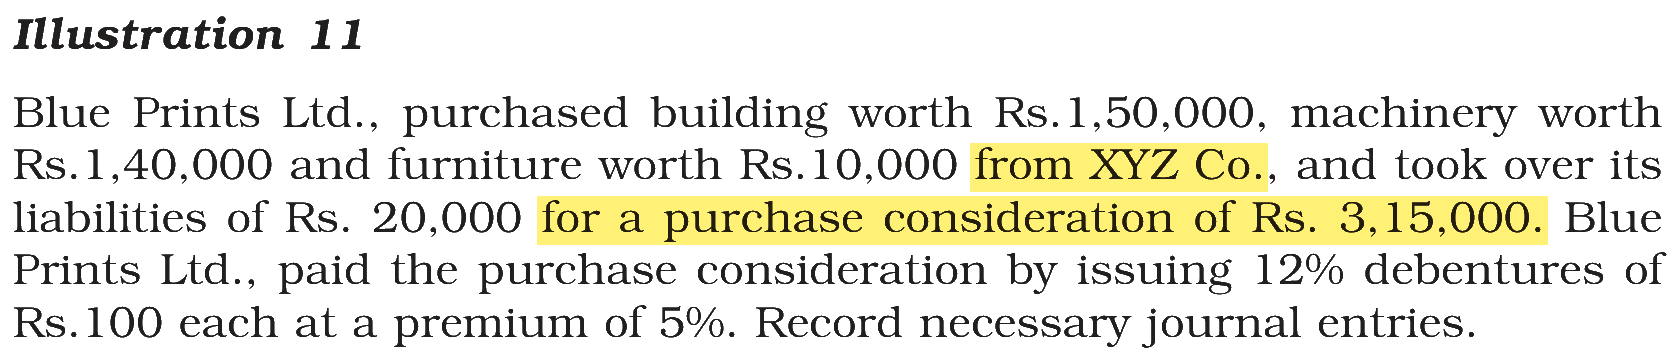
XYZ Ltd. purchased assets worth Rs 3,00,000 from Blue Prints Ltd., and took over its liabilities of Rs 20,000 for a purchase consideration of Rs 3,15,000. XYZ Ltd., paid the purchase consideration by issuing 12% debentures of Rs 100 each at a premium of 5%.
Blue Prints Ltd., account will be:
Answer & explanation
Correct answer: option 4
The correct answer is Option (4) → Credited by Rs 3,15,000
Blue Prints Ltd. is the vendor here: it sells the business to XYZ Ltd. In the buyer’s books, the vendor becomes a creditor for the full purchase consideration until it is paid.
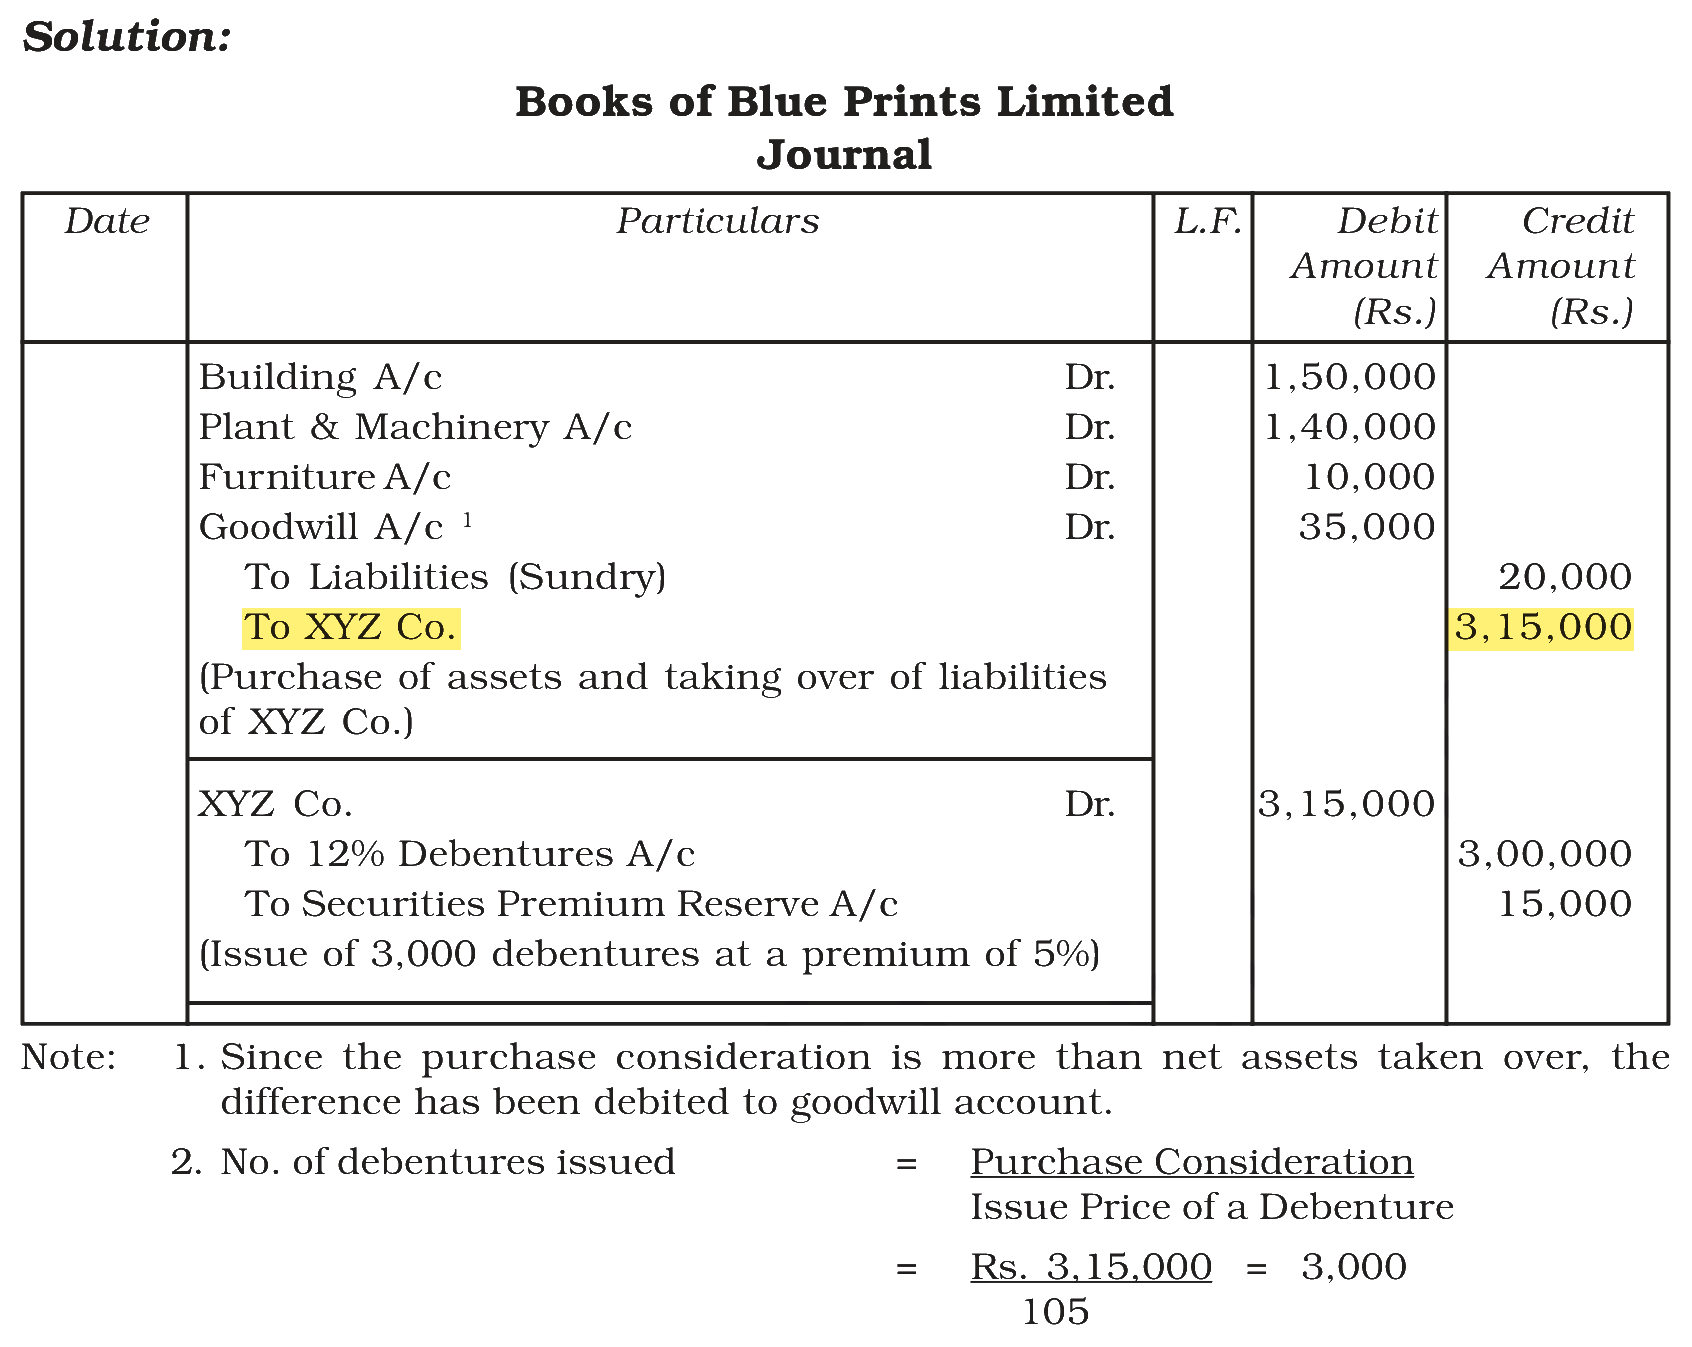
Entry for the purchase in the books of XYZ Ltd.:
Sundry Assets A/c Dr. 3,00,000
Goodwill A/c Dr. 35,000
To Sundry Liabilities A/c 20,000
To Blue Prints Ltd. 3,15,000
So Blue Prints Ltd.’s account is credited by Rs 3,15,000, the agreed purchase consideration, not by the value of the assets (Rs 3,00,000). It is debited later, by the same Rs 3,15,000, when the debentures are issued to it.
In the book’s version of this sum the two names are the other way round: Blue Prints Ltd. is the buyer and XYZ Co. the seller, so it is the seller XYZ Co. that is credited with Rs 3,15,000.
NCERT (2026-27 edition):
|