Stock at the time of dissolution was appearing in books at ₹50,000. Half of the stock was sold at a discount of 20% and the remaining was taken over by one of the partners at a 10% discount. What amount was received in cash at the time of realization of stock.
Answer & explanation
Correct answer: option 3
The correct answer is Option (3) → Rs. 20,000
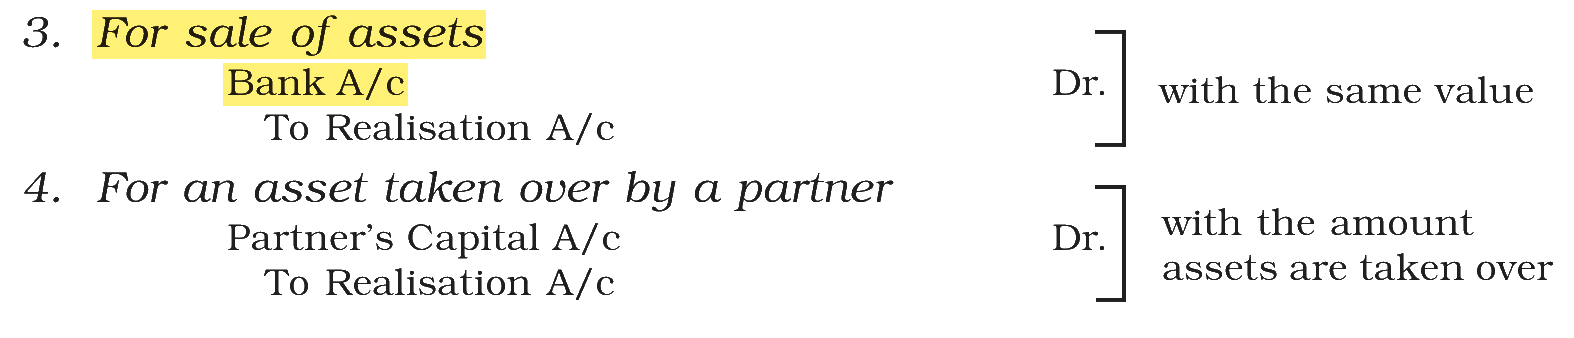
On dissolution, stock is either sold for cash or taken over by a partner. Only the part that is sold brings cash into the firm. The part a partner takes over is settled through his capital account (Partner’s Capital A/c Dr., To Realisation A/c), so no cash changes hands for it.
Working:
Book value of stock = Rs. 50,000
Half of the stock = Rs. 50,000 × 1/2 = Rs. 25,000
Sold at a discount of 20%, so 80% is received
Cash received = Rs. 25,000 × 80/100 = Rs. 20,000
The other half, taken over by the partner at 10% less, is worth Rs. 22,500 to the firm, but it is debited to that partner’s capital account, not received in cash. Adding it to the cash figure gives Rs. 42,500, the figure in Option (2).
NCERT (2026-27 edition):
|