Self - generated goodwill
Answer & explanation
Correct answer: option 2
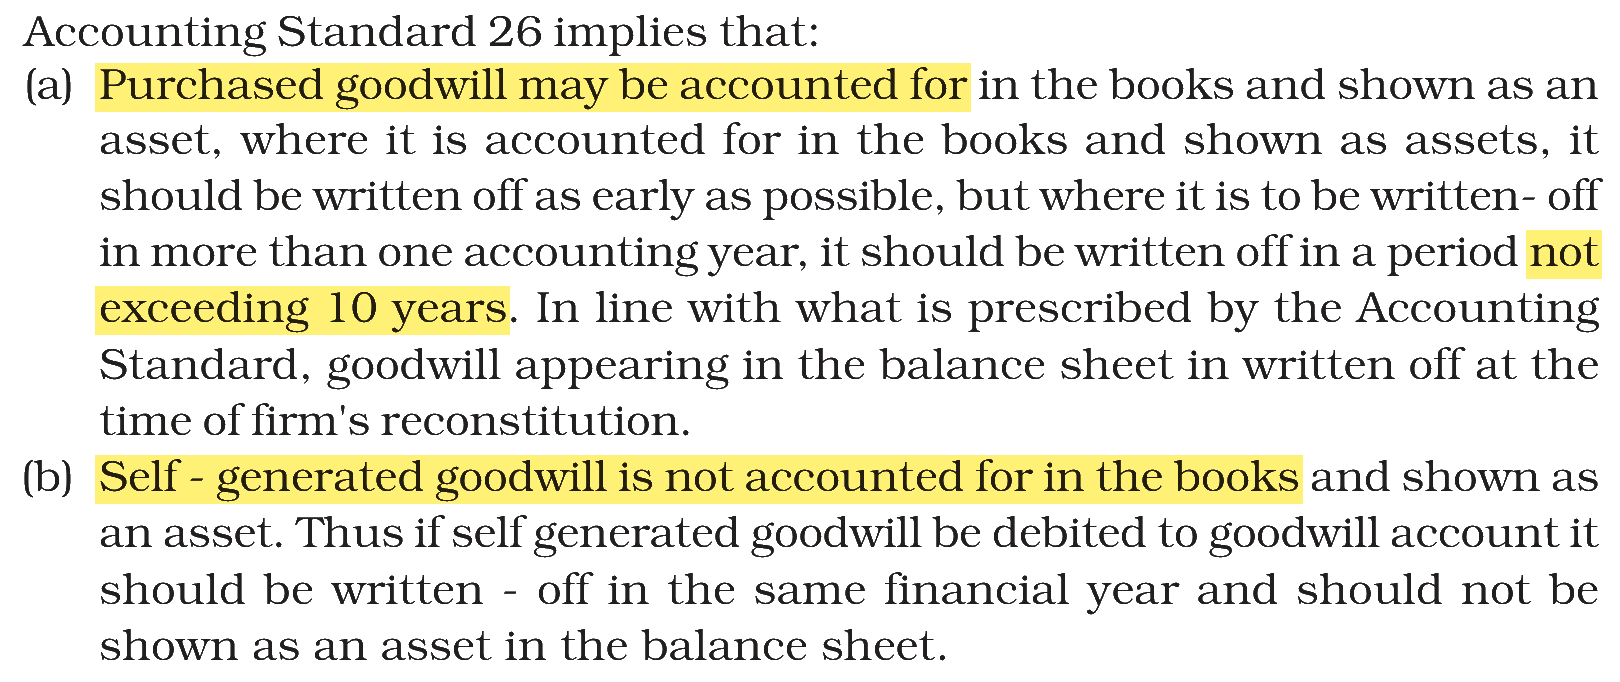
The correct answer is Option (2) → Is not accounted for in the books.
Self-generated goodwill is the reputation a firm builds up itself, without paying anyone for it. Under Accounting Standard 26 it is not recorded in the books as an asset. Only purchased goodwill, for which the firm has paid, may be shown as an asset.
Why the other options are incorrect
Option (1) Is accounted for in the books and shown as an asset. — Incorrect. This is the treatment of purchased goodwill, not of goodwill the firm has built itself.
Option (3) If it is accounted for in the books and shown as assets, it should be written off as early as possible, but where it is to be written- off in more than one accounting year, it should be written off in a period not exceeding 10 years. — Incorrect. The 10-year rule is for purchased goodwill. Self-generated goodwill, if wrongly debited to a Goodwill account, is written off in the same year.
Option (4) If it is accounted for in the books and shown as assets, it should be written off as early as possible, but where it is to be written- off in more than one accounting year, it should be written off at the time of dissolution of partnership firm — Incorrect. Goodwill in the balance sheet is written off at the time of the firm’s reconstitution, not kept till dissolution, and self-generated goodwill is never carried as an asset.
NCERT (2026-27 edition):
|