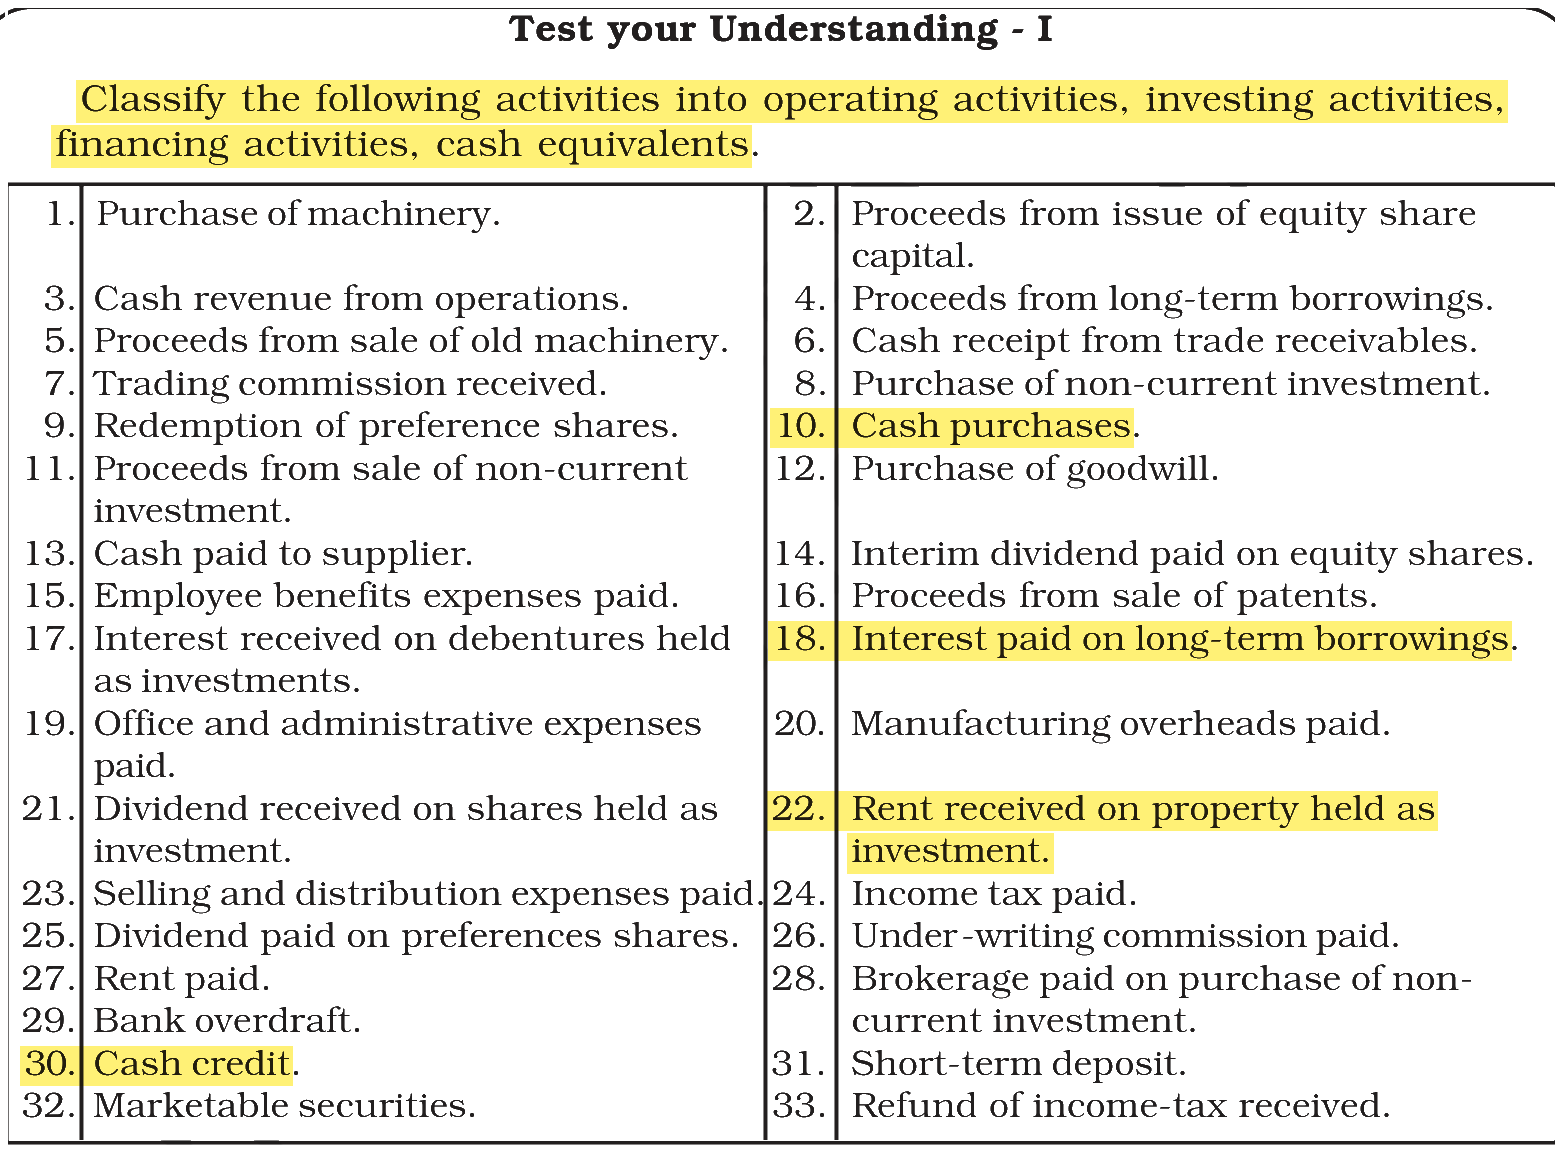
Match List-I with List-II.
| LIST I (Type of Activity) |
LIST II (Transaction) |
| (A) Operating Activity | (I)
Interest Paid on long-term borrowings |
| (B) Financing Activity | (II) Cash Credit |
| (C) Investing Activity | (III) Rent received on property held as investment |
| (D) Cash Equivalents | (IV) Cash purchases |
Choose the correct answer from the options given below:
Answer & explanation
Correct answer: option 4
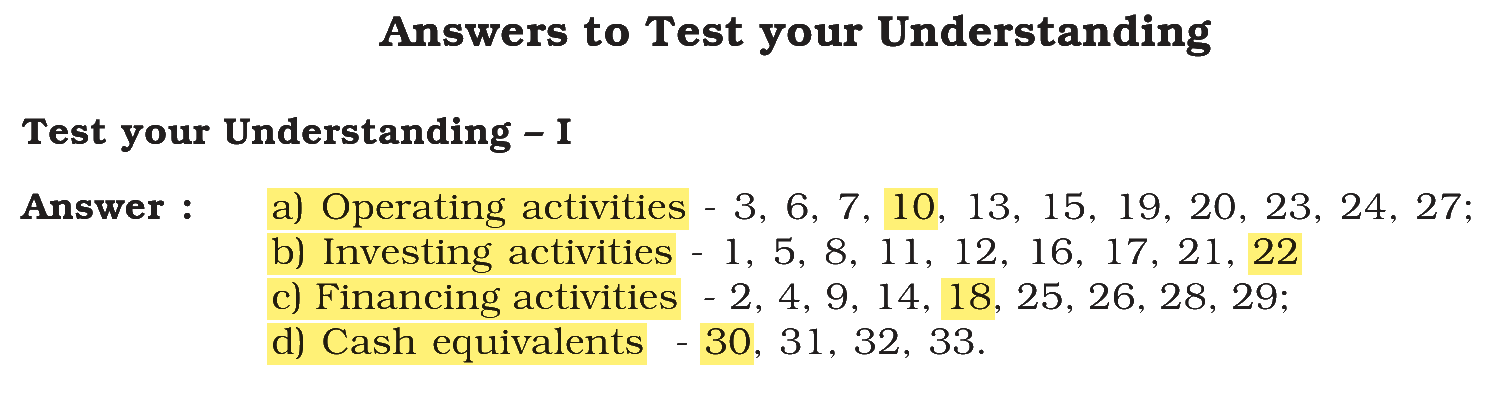
The correct answer is Option (4) → (A)-(IV), (B)-(I), (C)-(III), (D)-(II)
A cash flow statement sorts every cash movement by the activity that caused it: operating (the main revenue activities), investing (buying and selling long-term assets and investments), financing (owners’ capital and borrowings, with their interest and dividends), and cash equivalents (items treated as cash itself).
(A) Operating Activity — this matches (IV) Cash purchases. Buying goods for cash is part of the firm’s main trading activity.
(B) Financing Activity — this matches (I) Interest Paid on long-term borrowings. Interest is the cost of the borrowed funds, so it goes with the borrowing under financing.
(C) Investing Activity — this matches (III) Rent received on property held as investment. The property is an investment, so the income from it is an investing inflow.
(D) Cash Equivalents — this matches (II) Cash Credit. In the book’s classification, cash credit is grouped with short-term deposits and marketable securities as a cash equivalent.
Note: Under AS-3, cash credit is usually treated as a short-term bank borrowing. The book (Test your Understanding - I and its answer key) lists it as a cash equivalent, and the answer here follows the book.
NCERT (2026-27 edition):
|