Match List-I with List-II
| List-I | List-II | ||
|---|---|---|---|
| (A) | Creditors are Paid by Firm at the time of dissolution of Partnership Firm in cash. | (I) | Realization Account Debited and Partner's Capital Account Credited. |
| (B) | Asset are taken over by a partner at the time of dissolution of Partnership Firm. | (II) | No Entry |
| (C) | Bills Payable are paid by giving Furnitures in full settlement. | (III) | Realization Account Debited and Cash Account Credited. |
| (D) | Unrecorded Liability taken over by a partner at the time of dissolution of a Partnership Firm. | (IV) | Partner's Capital Account Debited and Realization Account Credited. |
Choose the correct answer from the options given below:
Answer & explanation
Correct answer: option 2
The correct answer is Option (2) → (A) - (III), (B) - (IV), (C) - (II), (D) - (I)
On dissolution every asset and outside liability is moved to the Realisation Account at its book value, so each later event is entered against that account.
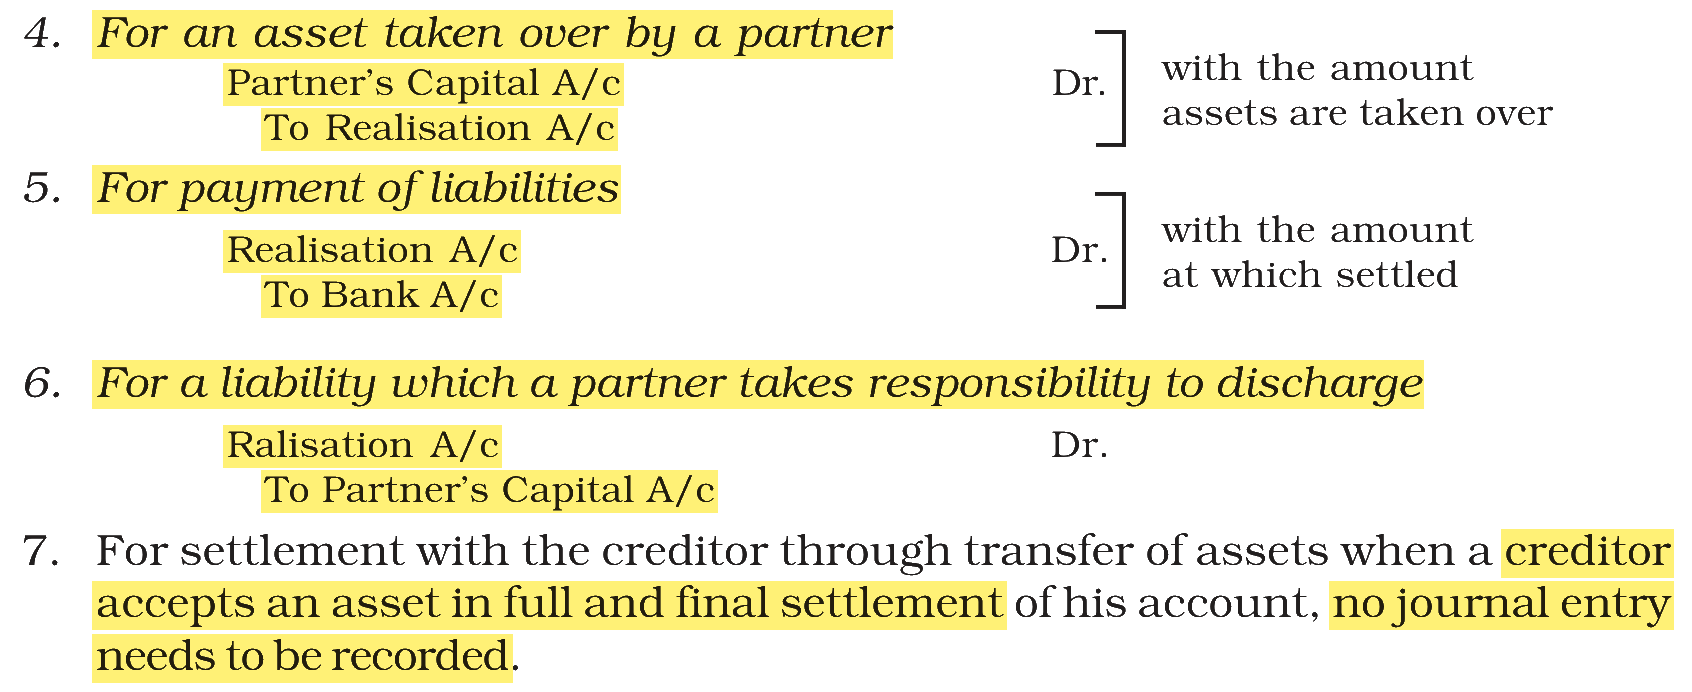
(A) Creditors are paid by the firm in cash — this matches (III) Realization Account Debited and Cash Account Credited. The liability now sits in the Realisation Account, and paying it out takes cash away from the firm.
(B) Assets are taken over by a partner — this matches (IV) Partner’s Capital Account Debited and Realization Account Credited. The partner pays for the asset through his capital, and the Realisation Account is credited as if the asset had been sold.
(C) Bills Payable are paid by giving Furnitures in full settlement — this matches (II) No Entry. Both the bills and the furniture are already in the Realisation Account, so settling one with the other in full needs no separate entry.
(D) Unrecorded Liability taken over by a partner — this matches (I) Realization Account Debited and Partner’s Capital Account Credited. The partner bears the liability, so his capital is credited, and the Realisation Account takes the charge.
NCERT (2026-27 edition):
|