Which account would be debited for being deceased partner's share of loss for the intervening period in the books of account?
Answer & explanation
Correct answer: option 3
The correct answer is Option (3) → Deceased Partner’s Capital A/c
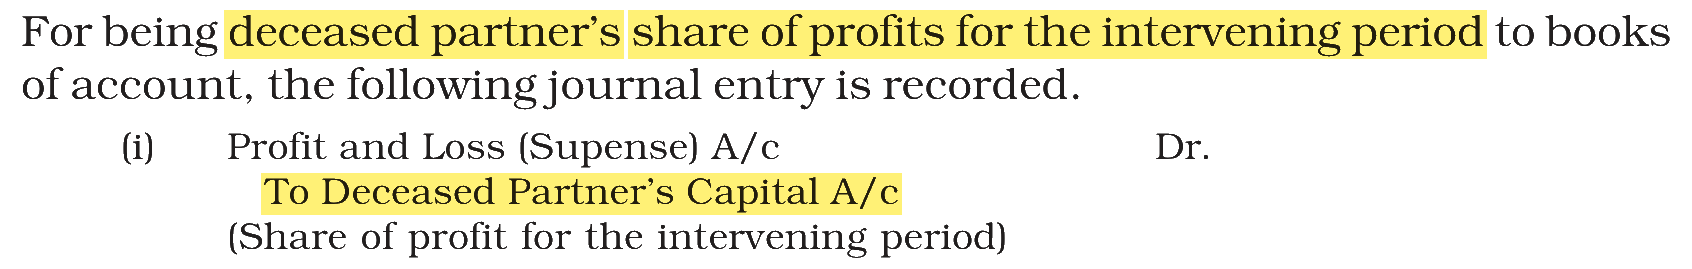
When a partner dies during the year, his share of profit or loss from the last balance sheet date to the date of death (the intervening period) is brought into the books through Profit & Loss (Suspense) A/c. A share of profit is credited to his capital account. A share of loss reduces what is due to him, so it is debited to his capital account:
Deceased Partner’s Capital A/c Dr.
To Profit & Loss (Suspense) A/c
The book gives this entry for a share of profit; for a share of loss the same entry is reversed, so the deceased partner’s capital account is debited.
Why the other options are incorrect
Option (1) Deceased Partner’s Executors A/c — Incorrect. This account is opened only after his capital account is settled, for the final amount payable to his executors.
Option (2) Deceased Partner’s Executors Capital A/c — Incorrect. There is no such account.
Option (4) Profit & Loss (Suspense) A/c — Incorrect. For a share of loss, this account is credited; it is debited only for a share of profit.
NCERT (2026-27 edition):
|