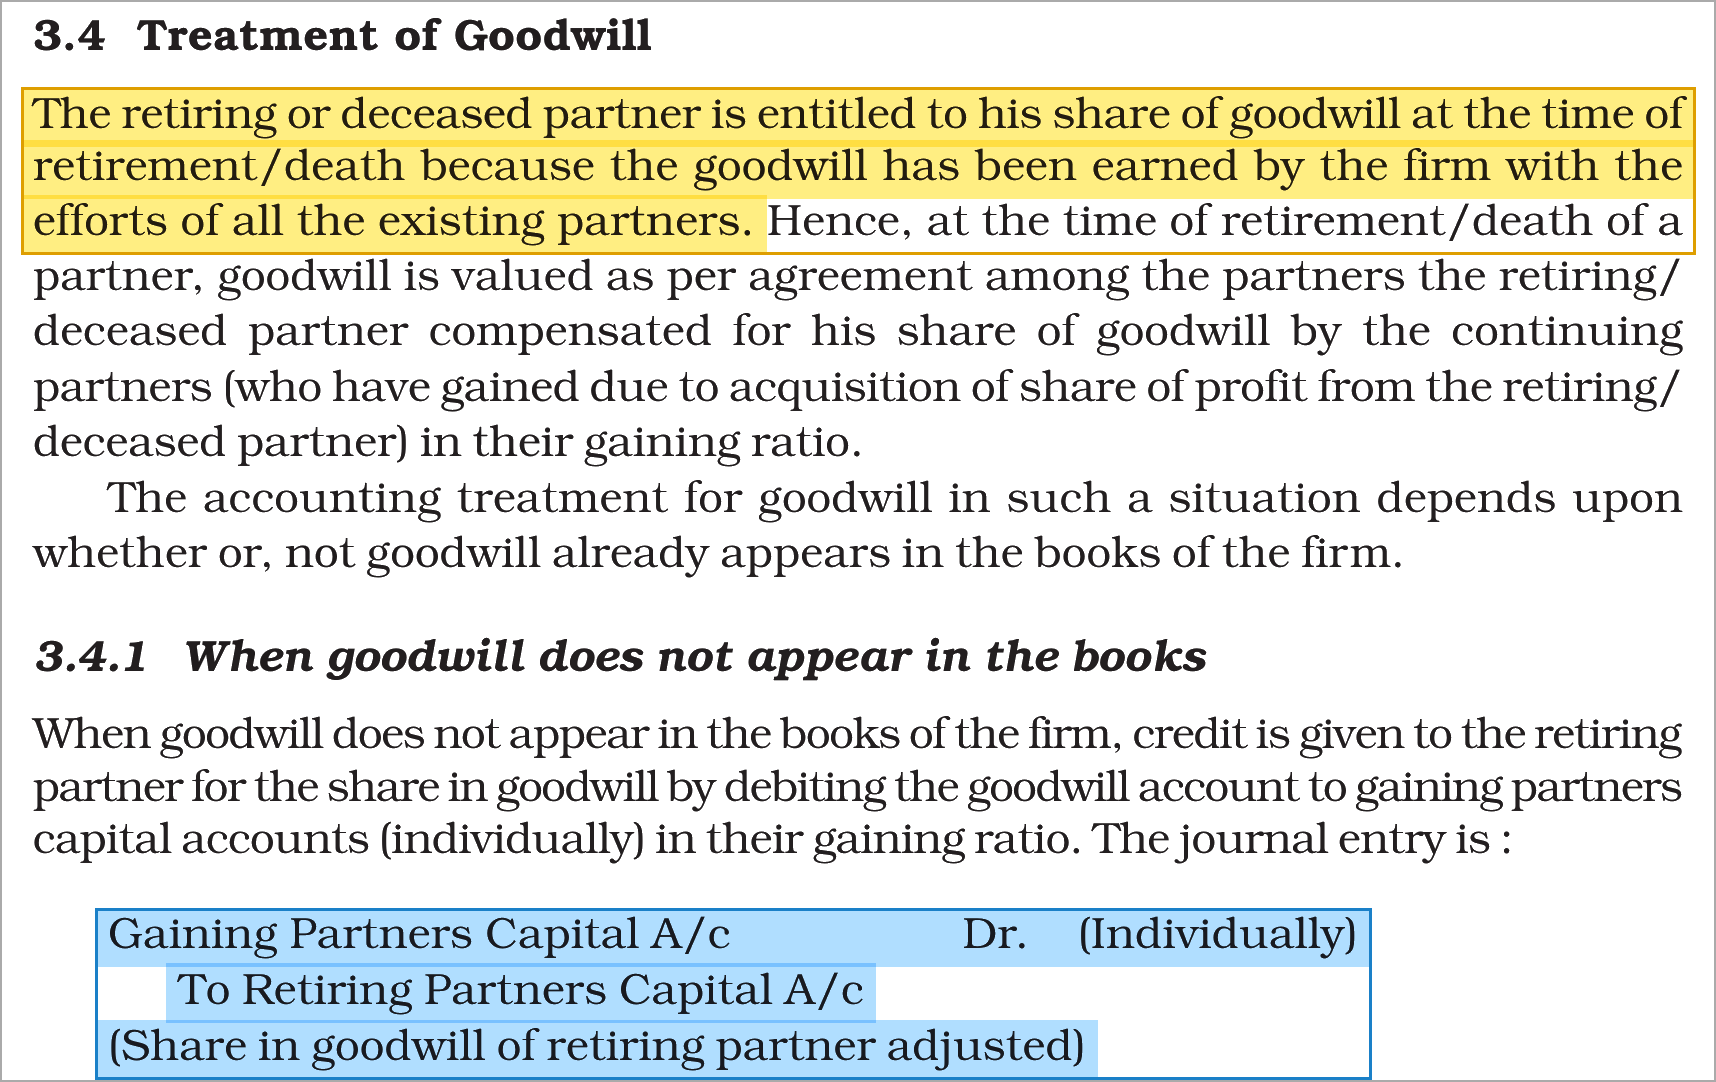
The retiring partner is entitled to his share of goodwill at the time of retirement because goodwill has been earned by the firm through the efforts of all existing partners. If goodwill does not appear in the firm's books of accounts, the correct journal entry for treatment of goodwill in this case is:
Answer & explanation
Correct answer: option 1
The correct answer is Option (1) → Gaining Partners’ Capital A/c Dr., To Retiring Partners’ Capital A/c
Goodwill that is not in the books is never brought into them on a retirement. It is adjusted straight through the partners’ capital accounts, and the direction follows who gains and who leaves.
- The continuing partners take over the retiring partner’s share of profit, so they are the ones who have gained and they are debited, individually, in their gaining ratio.
- The retiring partner parts with that share, so he is credited with his share of the firm’s goodwill.
Raising a Goodwill Account instead would put a self-generated asset on the balance sheet, which is not permitted, so the compensation passes between the capital accounts alone.
Why the other options are incorrect
Option (2) Retiring Partners’ Capital A/c Dr., To Gaining Partners’ Capital A/c — Incorrect. The entry is reversed: it pays the gaining partners out of the account of the man they owe.
Option (3) Sacrificing Partners’ Capital A/c Dr., To Gaining Partners’ Capital A/c — Incorrect. Nobody sacrifices on a retirement; a sacrificing ratio arises when a partner is admitted.
Option (4) Gaining Partners’ Capital A/c Dr., To Old Partners’ Capital A/c — Incorrect. “Old partners” takes in the gaining partners as well, so part of the compensation would return to the very partners who owe it. Only the retiring partner is credited.
NCERT Extract