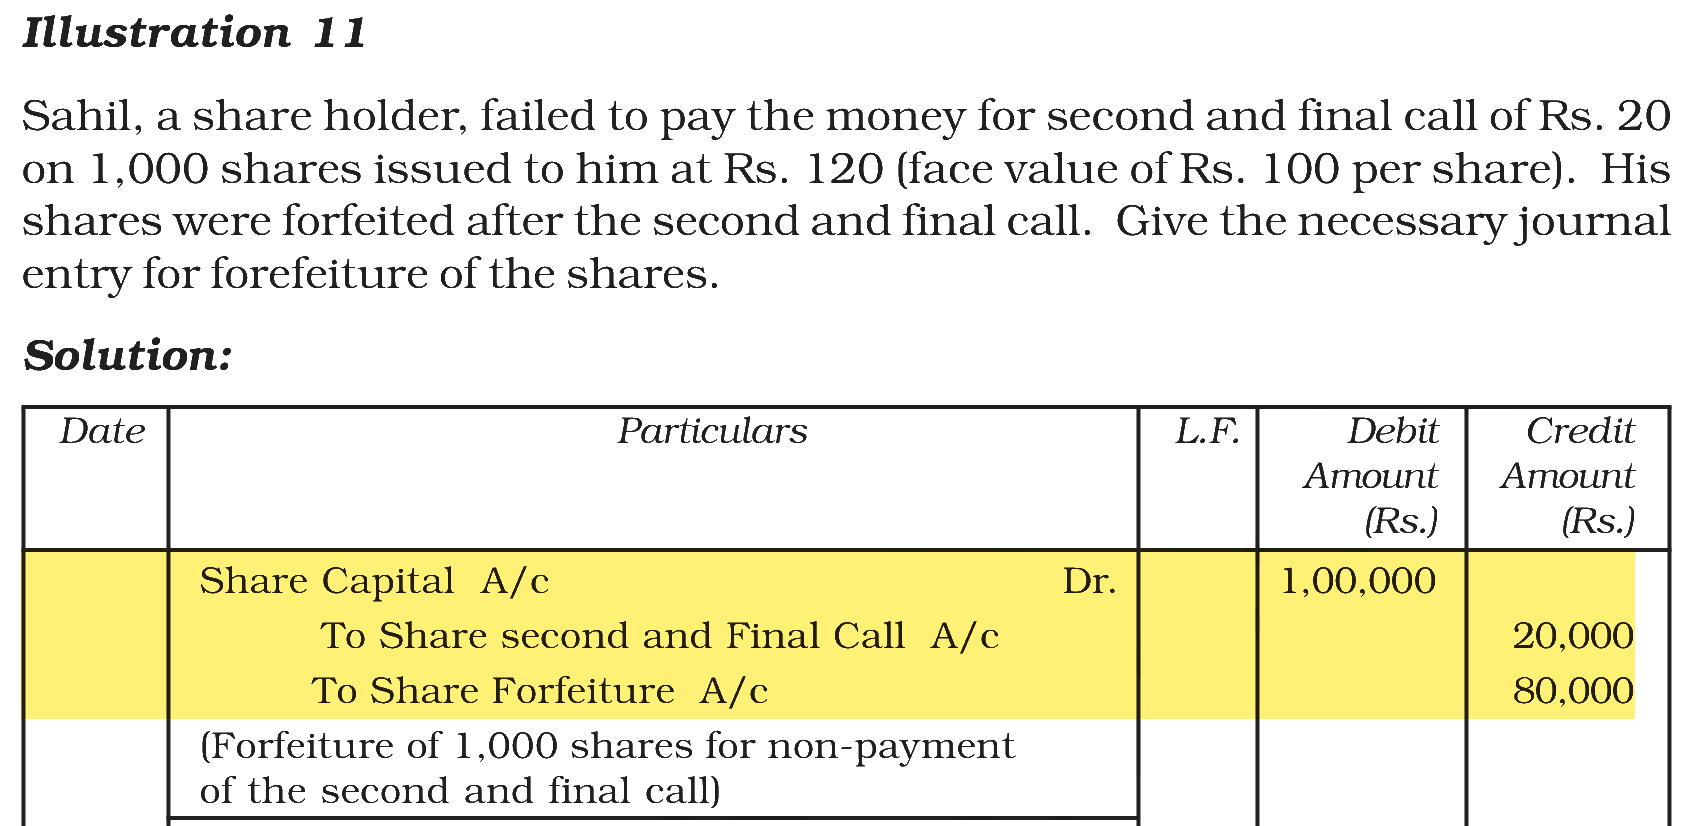
Shubham, a share holder, failed to pay the money for second and final call of Rs. 20 on 1,000 shares issued to him at Rs. 120 (face value of Rs. 100 per share). His shares were forfeited after the second and final call. What will be the journal entry for forfeiture of shares in this case?
Answer & explanation
Correct answer: option 3
The correct answer is Option (3) → Share Capital A/c Dr. 1,00,000; To Share second and Final Call A/c 20,000; To Share Forfeiture A/c 80,000
On forfeiture, the entries already made for the forfeited shares are reversed:
Debit Share Capital A/c with the amount called up on the forfeited shares, Rs. 100 per share (the face value).
Credit Share Second and Final Call A/c with the call the shareholder did not pay.
Credit Share Forfeiture A/c with the amount actually received on share capital.
Securities Premium is not touched: the premium of Rs. 20 per share was already received, so it stays there.
Working:
Share Capital A/c debited = 1,000 × Rs. 100 = Rs. 1,00,000
Unpaid second and final call = 1,000 × Rs. 20 = Rs. 20,000
Share Forfeiture A/c = Rs. 1,00,000 − Rs. 20,000 = Rs. 80,000
Note: This question is from NCERT (2026-27). NTA sets numerical questions from NCERT too, so do not ignore NCERT while practising numericals.
NCERT (2026-27 edition):
|