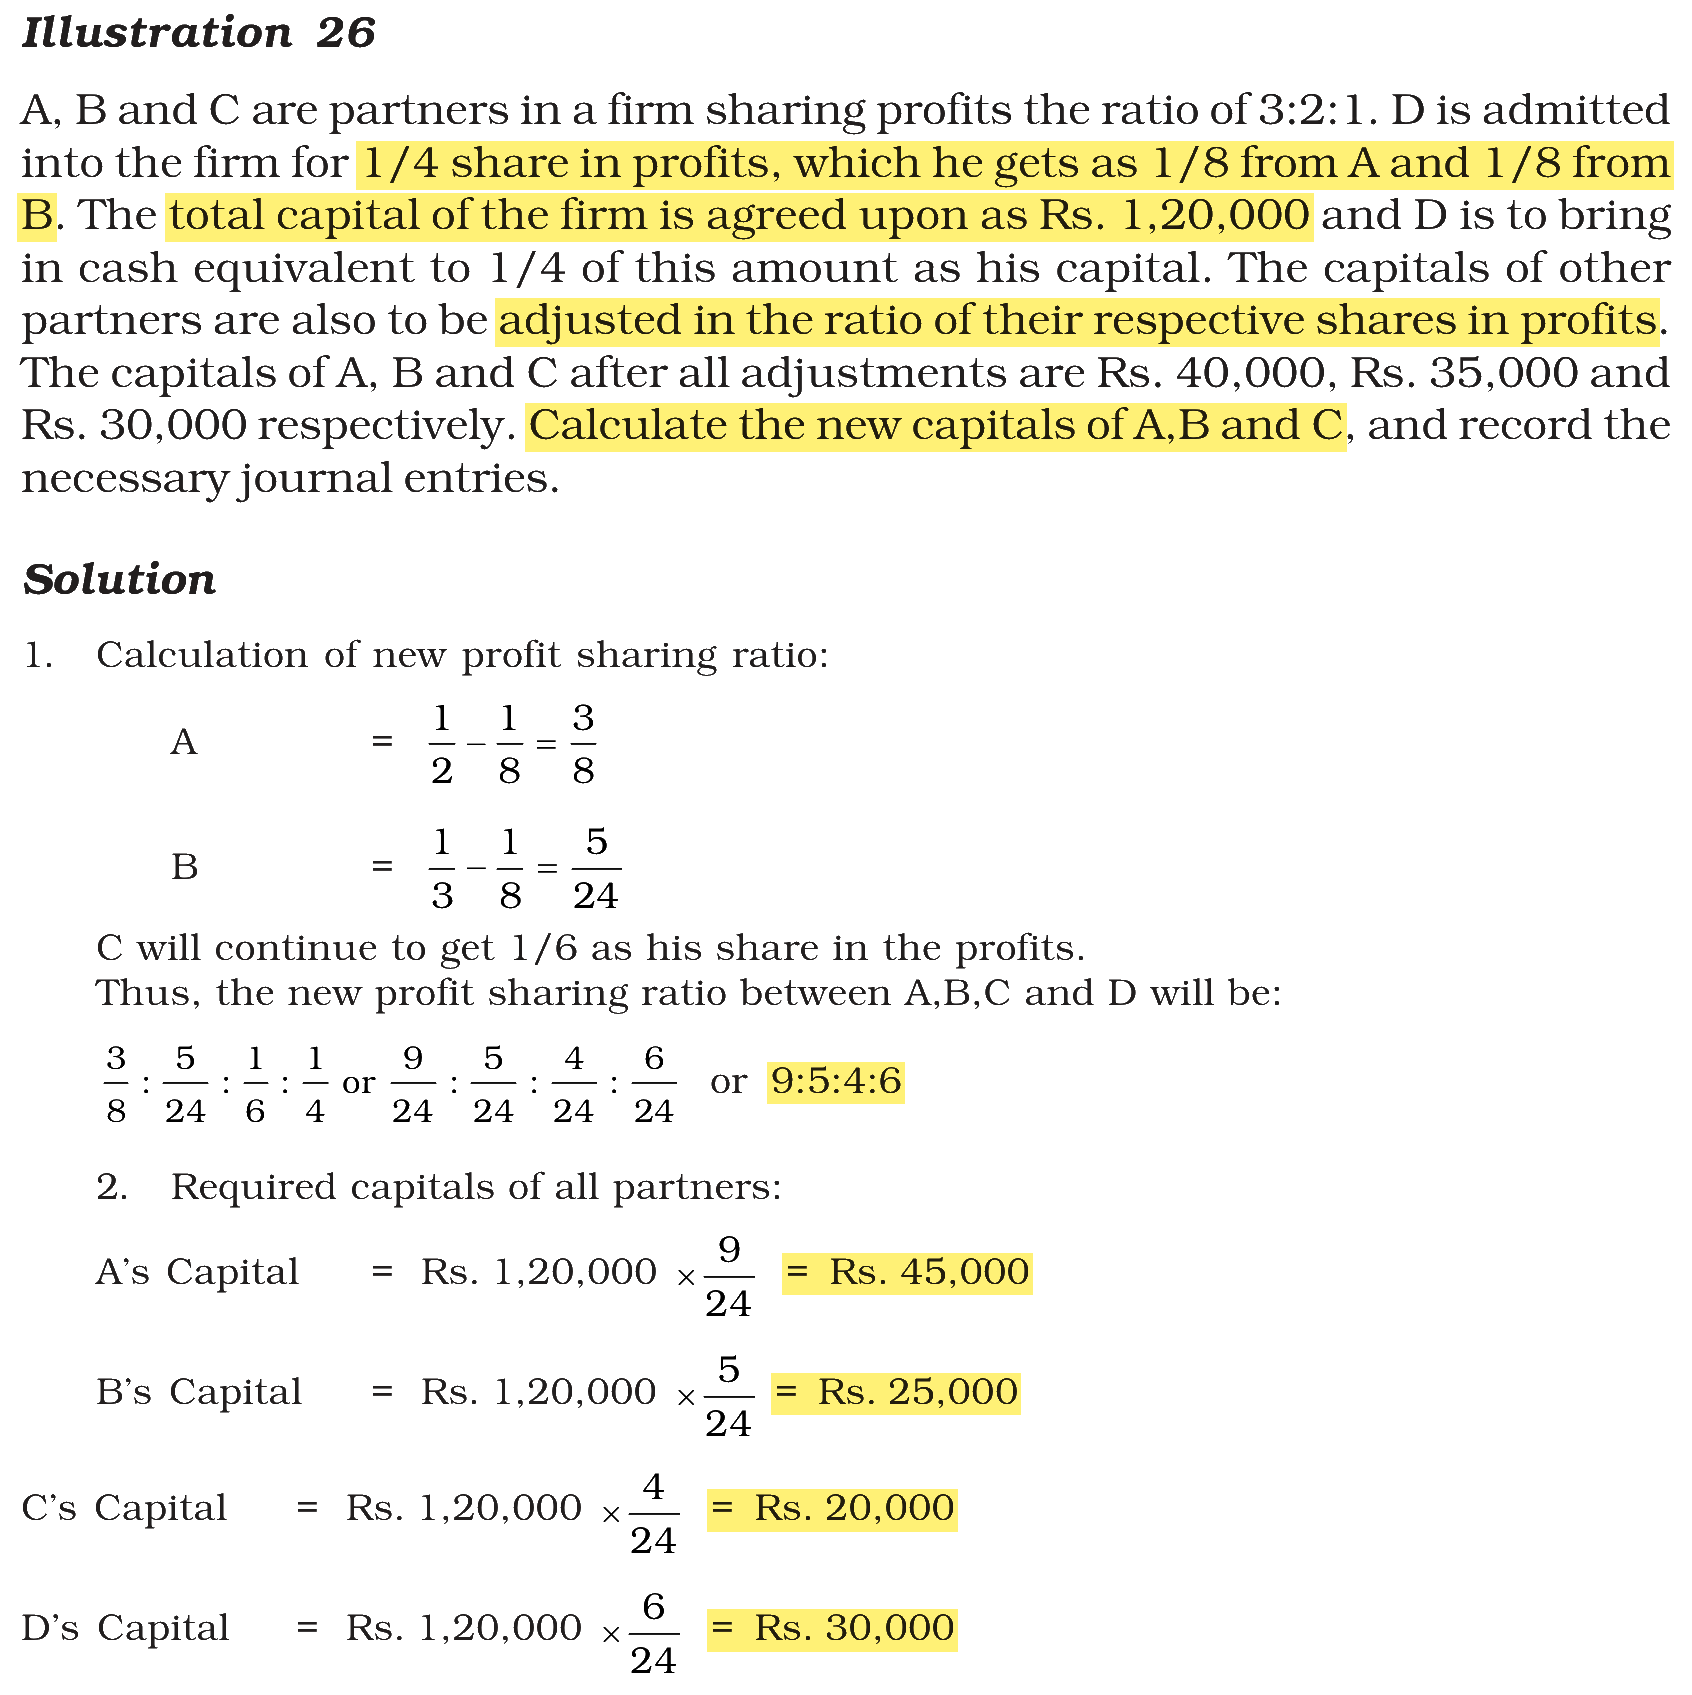
In a partnership firm, A, B and C are partners with a ratio of 3:2:1 having capitals of Rs. 40,000, Rs. 35,000 and Rs. 30,000 respectively. They admitted D into the firm for 1/4 share in profits, which she gets 1/8 from A and 1/8 from B. They agreed upon capital of the new firm to be Rs. 1,20,000 and D is to bring in her share of capital in cash. The capital of other partners are to be adjusted in the ratio of their respective shares in profits. Arrange the following amount of new capital of partners, A, B, C and D respectively, in their correct sequence.
(A) Rs. 20,000
(B) Rs. 25,000
(C) Rs. 30,000
(D) Rs. 45,000
Choose the correct answer from the options given below:
Answer & explanation
Correct answer: option 4
The correct answer is Option (4) → (D), (B), (A), (C)
When the total capital of the new firm is fixed and each partner's capital is to be in the ratio of the profit shares, every partner's capital is total capital × that partner's new share of profit. So the new profit sharing ratio is worked out first.
New shares (A and B each give up 1/8 to D; C gives up nothing):
A: 3/6 − 1/8 = 12/24 − 3/24 = 9/24
B: 2/6 − 1/8 = 8/24 − 3/24 = 5/24
C: 1/6 = 4/24 (unchanged)
D: 1/4 = 6/24
New ratio of A, B, C and D = 9 : 5 : 4 : 6. New capitals out of Rs. 1,20,000:
A: 1,20,000 × 9/24 = Rs. 45,000, item (D)
B: 1,20,000 × 5/24 = Rs. 25,000, item (B)
C: 1,20,000 × 4/24 = Rs. 20,000, item (A)
D: 1,20,000 × 6/24 = Rs. 30,000, item (C)
The old capitals (Rs. 40,000, Rs. 35,000 and Rs. 30,000) do not change these figures. They only decide the adjustment: A brings in Rs. 5,000, while B and C each withdraw Rs. 10,000.
Note: This question is from NCERT (2026-27). NTA sets numerical questions from NCERT too, so do not ignore NCERT while practising numericals.
NCERT (2026-27 edition):
|