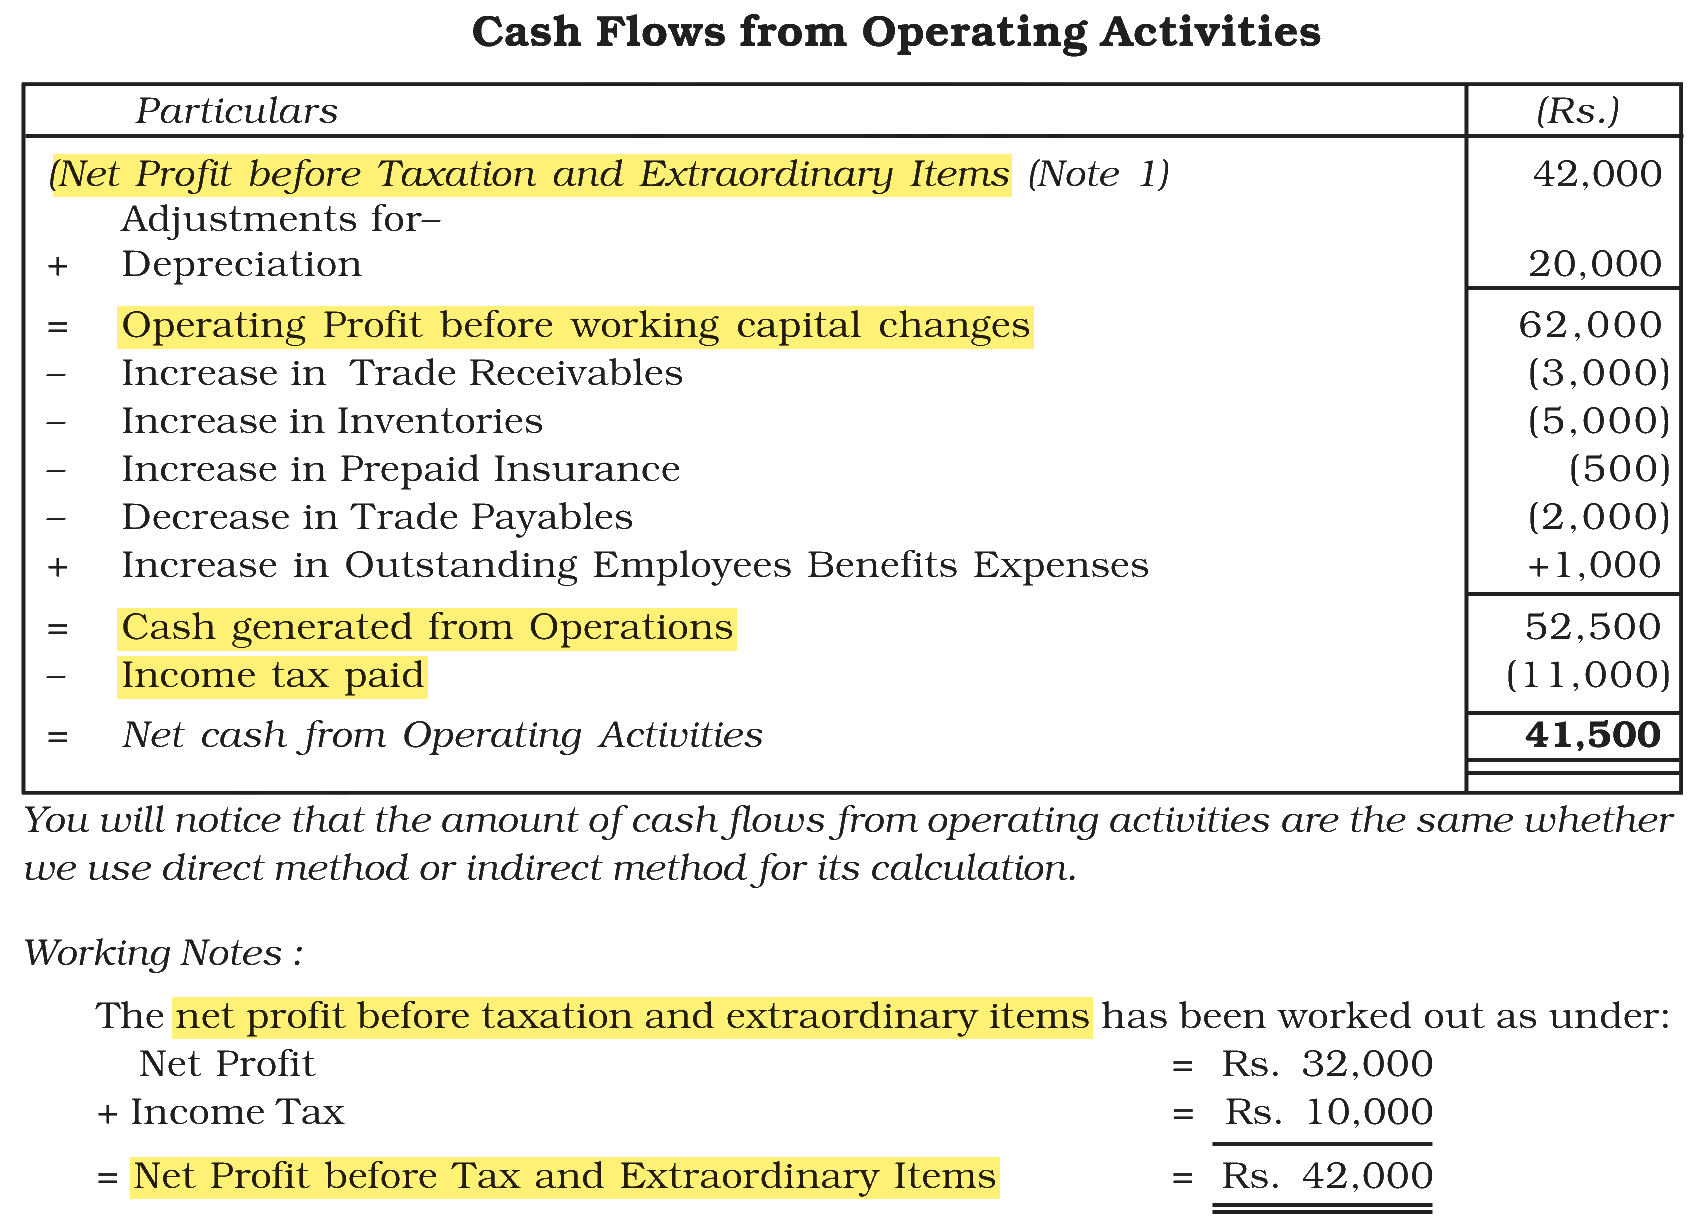
Arrange the following into correct sequence while computing cash flow from operating activities.
(a) Compute Net Profit before tax after making necessary adjustments.
(b) Compute operating profit before working capital changes by making adjustment for non-cash and non-operating activities.
(c) Calculate the difference between opening and closing balance in statement of profit and loss.
(d) Compute operating profit by making adjustment for working capital changes.
(e) Calculate cash generated/cash used from operating activities by deducting tax paid from operating profit.
Choose the correct answer from the options given below :
Answer & explanation
Correct answer: option 4
The correct answer is Option (4) → (c), (a), (b), (d), (e)
Under the indirect method, the work starts from the profit of the year and moves step by step to the net cash flow from operating activities. Each step uses the figure found in the step before it.
(c) Calculate the difference between opening and closing balance in statement of profit and loss. — first. The increase in the balance of the Statement of Profit and Loss gives the net profit of the year.
(a) Compute Net Profit before tax after making necessary adjustments. — second. Items such as income tax and dividend are added back to that profit to get the net profit before tax, the starting point of the indirect method.
(b) Compute operating profit before working capital changes by making adjustment for non-cash and non-operating activities. — third. Non-cash items (depreciation, goodwill written off) and non-operating items (interest, profit on sale of assets) are adjusted to reach the operating profit before working capital changes.
(d) Compute operating profit by making adjustment for working capital changes. — fourth. Changes in current assets and current liabilities are adjusted next. This gives the cash generated from operations.
(e) Calculate cash generated/cash used from operating activities by deducting tax paid from operating profit. — last. Income tax paid is deducted at the end to get the net cash flow from operating activities.
NCERT (2026-27 edition):
|