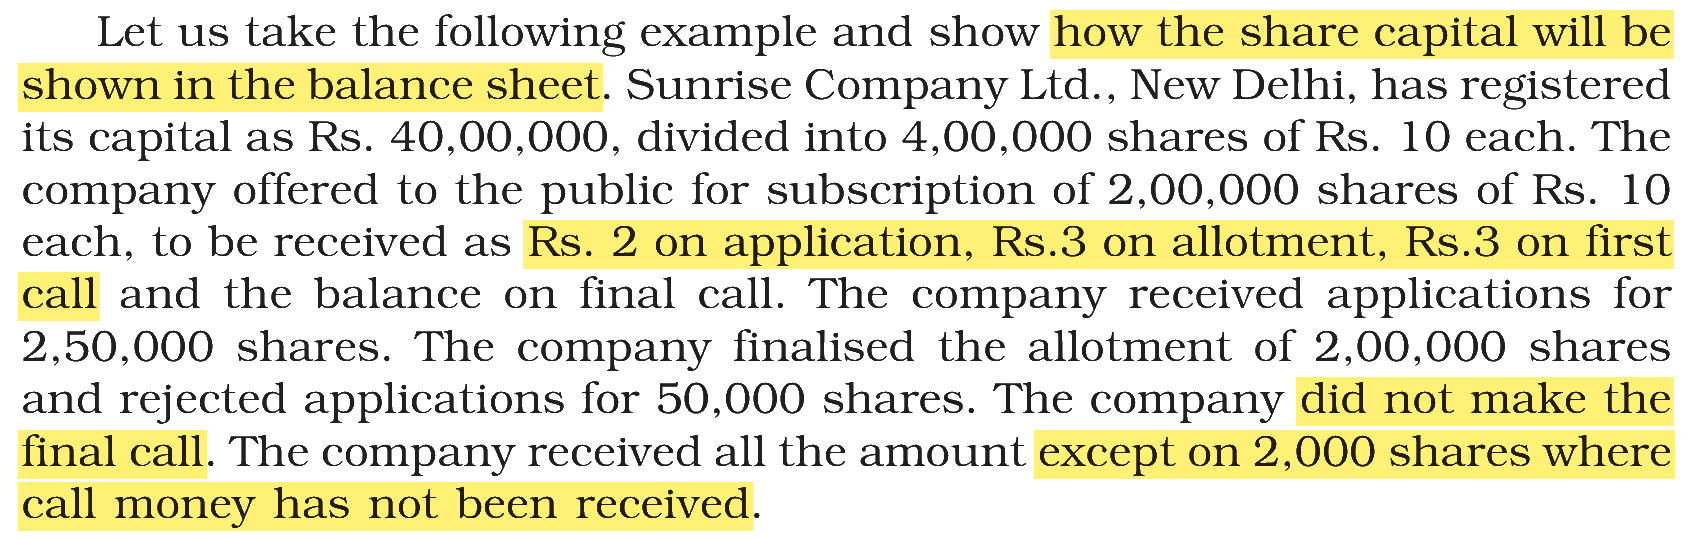
Mukesh Ltd. offered 4,00,000 shares, of Rs. 10 each to the public for subscription, to be received as Rs. 2 on application, Rs. 3 on allotment, Rs. 3 on first call and the balance on final call. The company received applications for 4,50,000 shares. The company finalised the allotment of 4,00,000 shares and rejected applications for 50,000 shares. The company did not make the final call. The company received all the amount except on 20,000 shares where call money has not been received. The amount of share capital that will be shown in the balance sheet of Mukesh Ltd. as:
Answer & explanation
Correct answer: option 4
The correct answer is Option (4) → Rs. 31,40,000
The share capital shown in the balance sheet is the called-up capital less calls in arrears (the subscribed but not fully paid-up capital). Money not yet called, like the final call here, is not counted at all.
Amount called up per share = Rs. 2 + Rs. 3 + Rs. 3 = Rs. 8 (the final call of Rs. 2 was not made)
Shares allotted = 4,00,000 (applications for 50,000 shares were rejected and their money refunded)
Called-up capital = 4,00,000 × Rs. 8 = Rs. 32,00,000
Calls in arrears = 20,000 × Rs. 3 (first call) = Rs. 60,000
Share capital shown = Rs. 32,00,000 − Rs. 60,000 = Rs. 31,40,000
Rs. 40,00,000 is the face value of all the shares allotted; it would appear only after the final call is made and fully paid.
Note: NTA picked this question from an NCERT (2026-27) illustration and changed the figures. Do not ignore NCERT while practising numericals.
NCERT (2026-27 edition):
|