The correct answer is Option (3) → B, C and E only
A retiring partner is paid what the firm owes him up to the date of retirement.
A. Share in profits made by firm after his retirement — False. He has no right to later profits; only if his dues stay unpaid may he choose interest at 6% p.a. or a share of profit earned with his money (Section 37).
B. His share of Goodwill — True. Goodwill was earned with his efforts too.
C. His share in Accumulated Reserve — True. Reserves are transferred to all partners in the old ratio.
D. Share in Employees Provident Fund — False. It is a liability of the firm owed to its employees, not a profit of the partners.
E. Share in Revaluation Gain — True. Revaluation profit goes to all partners, the retiring partner included, in the old ratio.
NCERT (2026-27 edition):
Treatment of Goodwill – “The retiring or deceased partner is entitled to his share of goodwill at the time of retirement/death because the goodwill has been earned by the firm with the efforts of all the existing partners.” NCERT (2026-27 edition):
Adjustment of Accumulated Profits and Losses – “Sometimes, the Balance Sheet of a firm may show accumulated profits in the form of general reserve and/on accumulated losses in the form of profit and loss account debit balance. The retiring/deceased partner is entitled to his/her share in the accumulated profits and is also liable to share the accumulated losses, if any. These accumulated profits or losses belong to all the partners and should be transferred to the capital accounts of all partners in their old profit sharing ratio.” NCERT (2026-27 edition):
Adjustment for Revaluation of Assets and Liabilities – “… As learnt in case of admission of a partner, a Revaluation Account is prepared in order to ascertain net gain (loss) on revaluation of assets and/or liabilities and bringing unrecorded items into firm’s books and the same is transferred to the capital account of all partners including retiring/deceased partners in their old profit sharing ratio.” NCERT (2026-27 edition):
Disposal of Amount Due to Retiring Partner – “The outgoing partner’s account is settled as per the terms of partnership deed i.e., in lumpsum immediately or in various instalments with or without interest as agreed or partly in cash immediately and partly in instalment at the agreed intervals. In the absence of any agreement, Section 37 of the Indian Partnership Act, 1932 is applicable, which states that the outgoing partner has an option to receive either interest @ 6% p.a. till the date of payment or such share of profits which has been earned with his/her money (i.e., based on capital ratio).” NCERT (2026-27 edition):
Illustration 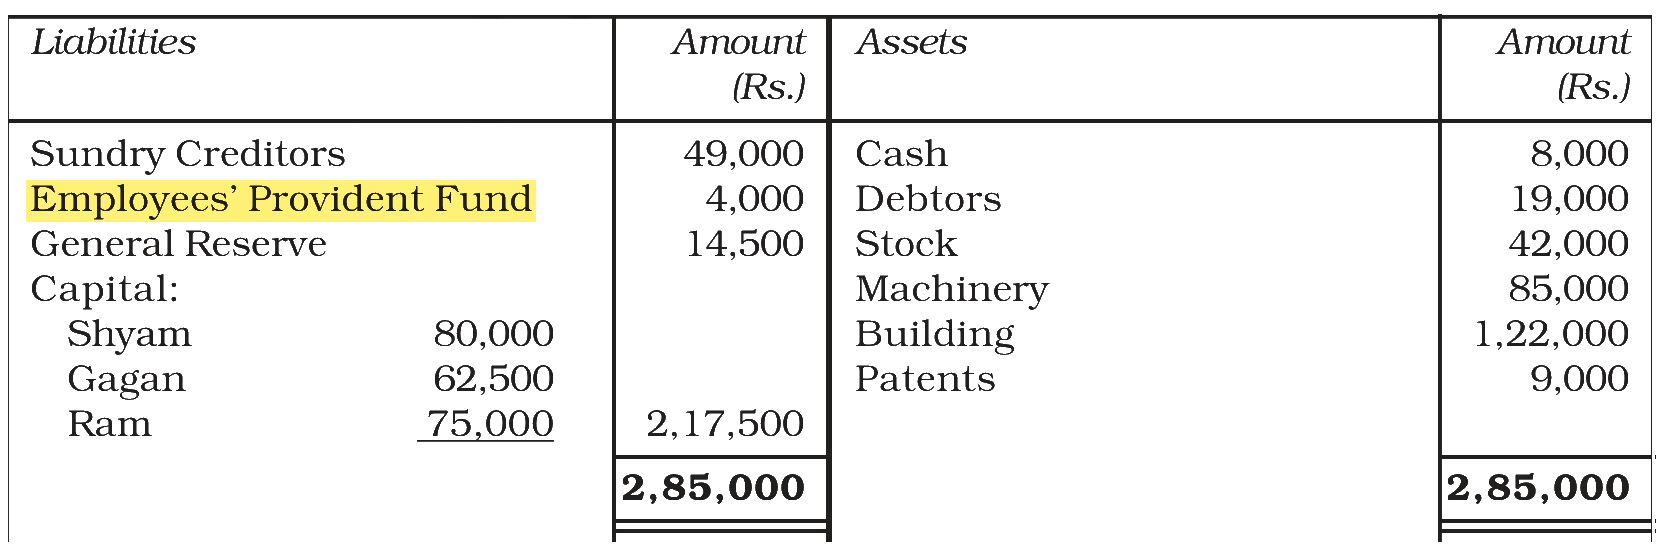
|
