Deferred revenue expenditure appearing in the old Balance Sheet at the time of Dissolution of partnership will be:
Answer & explanation
Correct answer: option 1
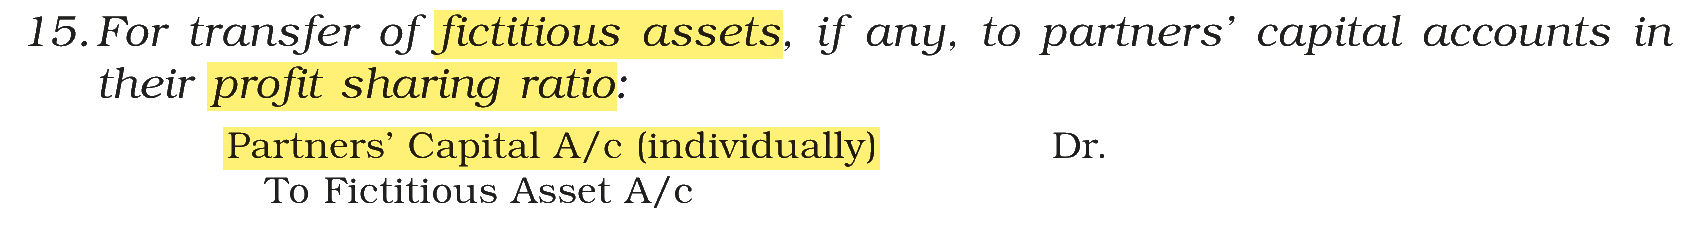
The correct answer is Option (1) → Debited to Partners’ Capital A/c and distributed among all the partners in old ratio.
Deferred revenue expenditure is a fictitious asset: an expense not yet written off, which stands in the Balance Sheet but cannot be sold. On dissolution it is not taken to the Realisation Account; it is a loss of the partners and is written off by debiting their capital accounts in their profit sharing ratio, which is the old ratio, since no new ratio arises when the firm closes.
Why the other options are incorrect
Option (2) Credited to Partners’ Capital A/c and distributed among all the partners in old ratio. — Incorrect. A credit would treat it as a gain, like a reserve. It is a loss to be written off, so the capital accounts are debited.
Option (3) Debited to Partners’ Capital A/c and distributed among all the partners in sacrificing ratio. — Incorrect. The sacrificing ratio is used when a new partner is admitted. On dissolution no partner sacrifices a share to another, so the ratio is the profit sharing ratio.
Option (4) Credited to Partners’ Capital A/c and distributed among all the partners in sacrificing ratio. — Incorrect. It is wrong on both counts: the entry is a debit, and the ratio is the old profit sharing ratio.
NCERT (2026-27 edition):
|