Read the following passage and answer the questions.
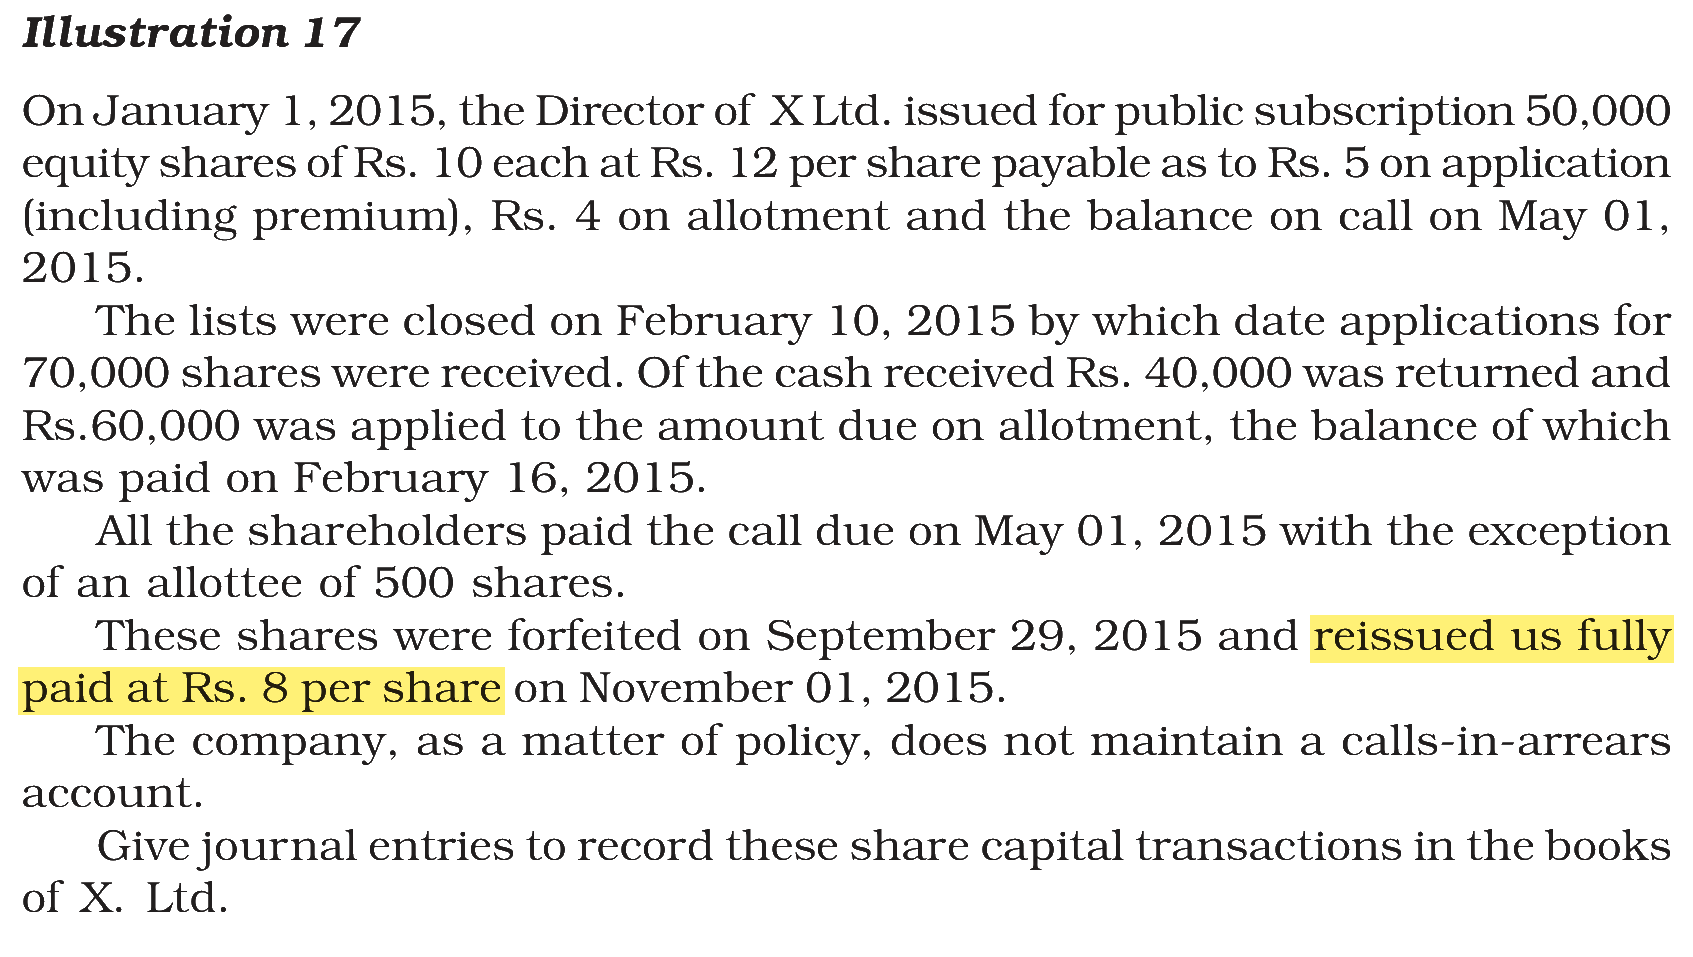
On January 1, 2024, the Director of X Ltd. issued for public subscription 50,000 equity shares of ₹10 each at ₹12 per share payable, ₹5 on application (including premium), ₹4 on allotment and the balance on call on May 01, 2024. The issue was closed on February 10, 2024 by which date applications for 70,000 shares were received. Of the cash received ₹40,000 was returned and ₹60,000 was applied to the amount due on allotment, the balance of which was paid on February 16, 2024. All the shareholders paid the call due on May 01, 2024 with the exception of an allottee of 500 shares. These shares were forfeited on September 29, 2024 and reissued as fully paid at ₹8 per share on November 01, 2024. The company, as a matter of policy, does not maintain a calls-in-arrears account.
On Reissue of 500 forfeited shares as fully paid at ₹8 per share, what amount will be debited to Shares Forfeiture Account?
Answer & explanation
Correct answer: option 1
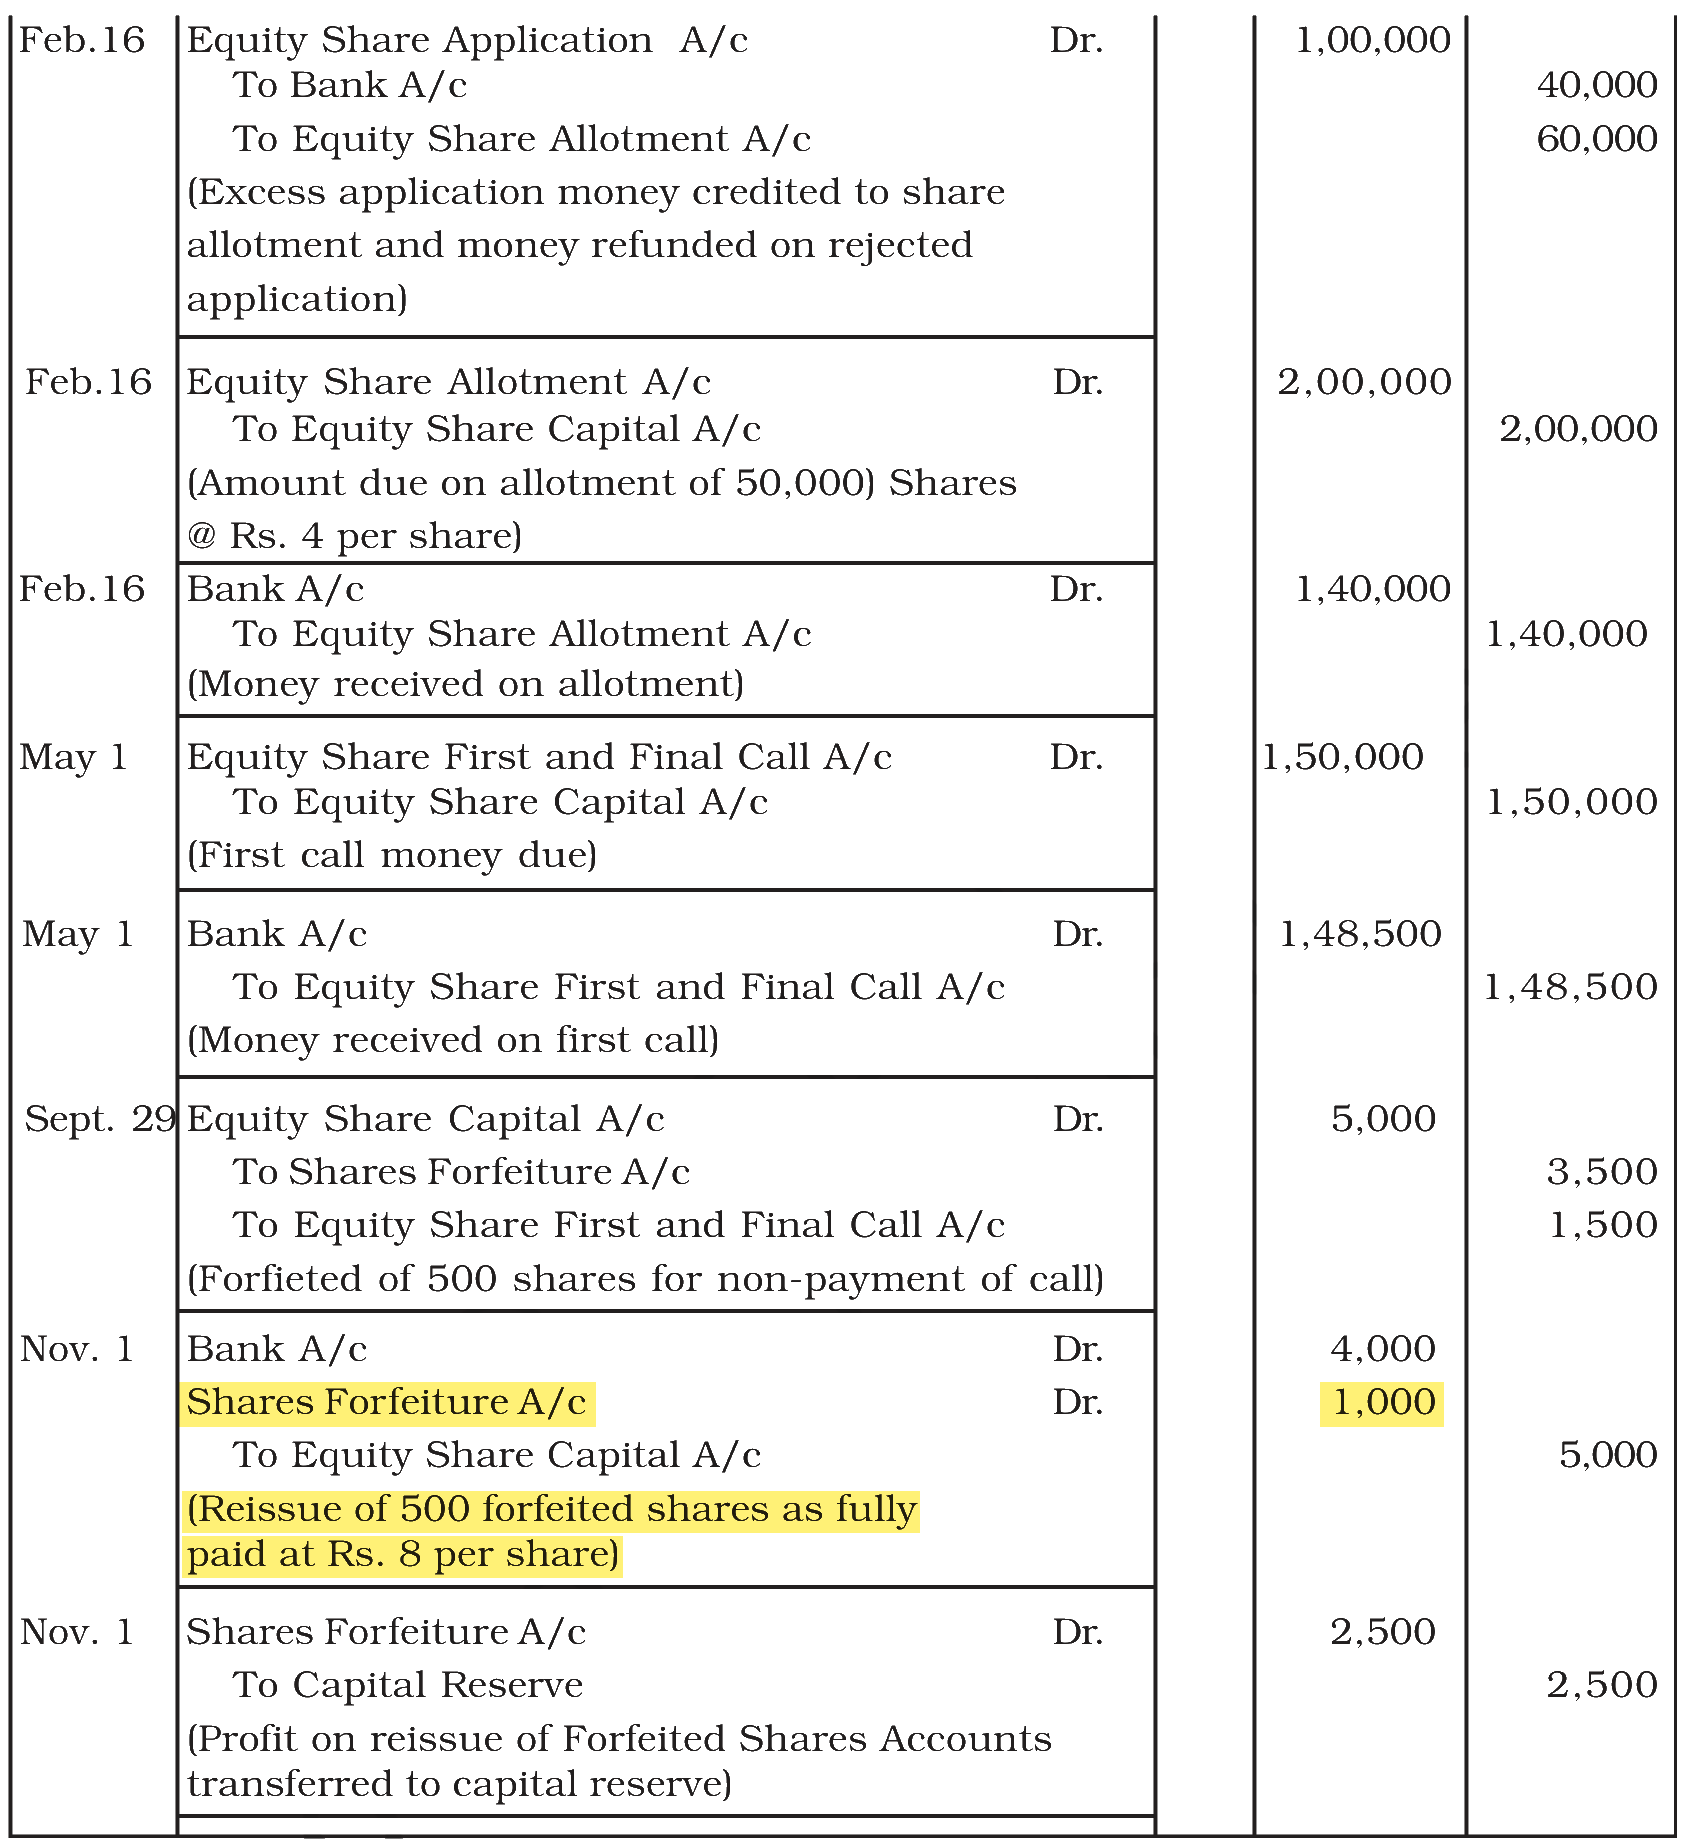
The correct answer is Option (1) → Rs. 1,000
Forfeited shares may be reissued at a discount, but the discount on reissue is debited to Shares Forfeiture Account, and it cannot exceed the amount forfeited on those shares.
Face value credited to Share Capital = 500 × Rs. 10 = Rs. 5,000
Cash received = 500 × Rs. 8 = Rs. 4,000
Discount on reissue = Rs. 5,000 − Rs. 4,000 = Rs. 1,000, debited to Shares Forfeiture A/c
The entry: Bank A/c Dr. Rs. 4,000; Shares Forfeiture A/c Dr. Rs. 1,000; To Equity Share Capital A/c Rs. 5,000. The Rs. 1,000 is well within the Rs. 3,500 forfeited on these shares.
NCERT (2026-27 edition):
NCERT (2026-27 edition):
|