Read the passage carefully and answer the questions based on the passage:
Long Run Costs
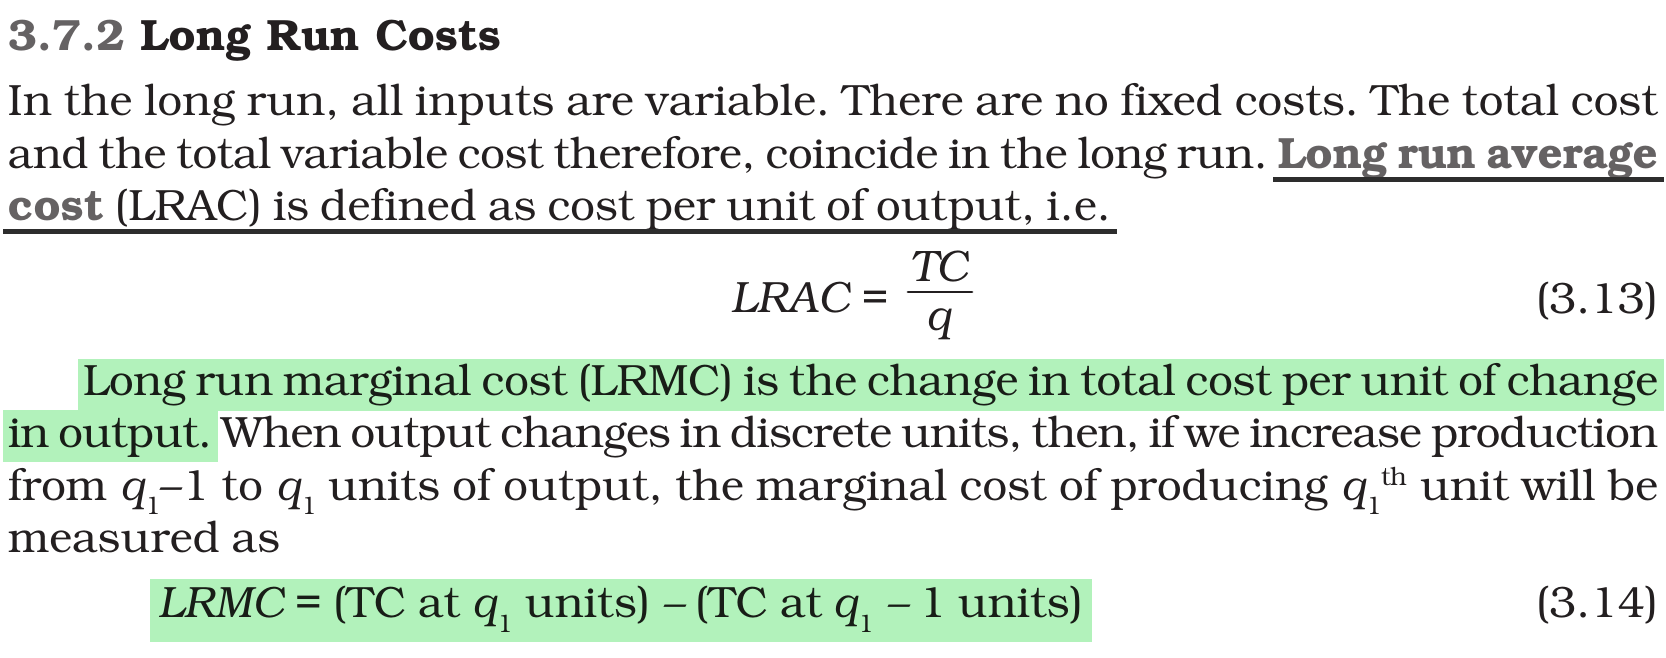
In the long run, all inputs are variable. There are no fixed costs. The total cost and the total variable cost therefore, coincide in the long run. Long run marginal cost is the change in total cost per unit of change in output. Increasing returns to scale implies that if we increase all the inputs by a certain proportion, output increases by more than that proportion. Decreasing returns to scale implies that if we want to increase the output by a certain proportion, inputs need to be increased by more than that proportion. Constant returns to scale implies a proportional increase in inputs resulting in a proportional increase in output. So the average cost remains constant as long as CRS operates. The LRAC curve is a 'U'-shaped curve. Its downward sloping part corresponds to IRS and upward rising part corresponds to DRS. At the minimum point of the LRAC curve, CRS is observed. For the first unit of output, both LRMC and LRAC are the same. Then, as output increases, LRAC initially falls, and then, after a certain point, it rises. As long as average cost is falling, marginal cost must be less than the average cost. When the average cost is rising, marginal cost must be greater than the average cost. LRMC cuts the LRAC curve from below at the minimum point of the LRAC.
The equation of long-run marginal cost is .................
Answer & explanation
Correct answer: option 2
The correct answer is Option (2) → (TC at \( q_1 \) units) − (TC at \( q_1 - 1 \) units)
Long run marginal cost (LRMC) is the change in total cost per unit of change in output. Let output rise by one unit, from \( q_1 - 1 \) to \( q_1 \). LRMC is then the total cost (TC) at the new output minus the TC at the old output.
Option (1) TC/q — Incorrect. Total cost divided by output is the long run average cost, the cost per unit of all the units together.
Option (2) (TC at \( q_1 \) units) − (TC at \( q_1 - 1 \) units) — Correct. It gives the extra cost of the last unit.
Option (3) TVC/q — Incorrect. Total variable cost (TVC) divided by output is the average variable cost. In the long run TVC and TC coincide, so this too is the average cost.
Option (4) TFC/q — Incorrect. Total fixed cost (TFC) divided by output is the average fixed cost, a short run idea. In the long run all inputs are variable, so there is no fixed cost.
NCERT (2026-27): Introductory Microeconomics — Chapter 3: Production and Costs
|