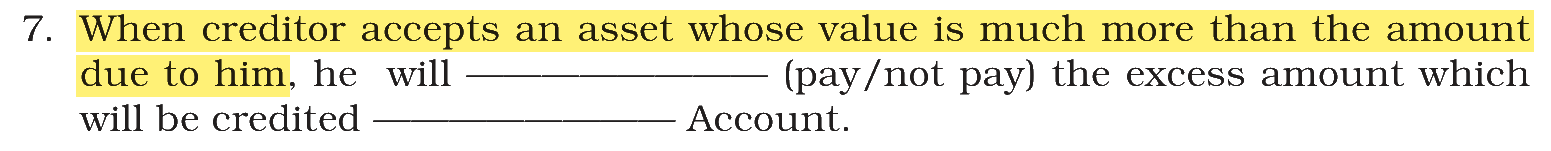Meena and Tina are partners in a firm and share profit as 3:2. They decided to dissolve their firm on March 31, 2017, when their Balance Sheet was as follows:
Balance Sheet Meena and Tina as of March 31,2017
| Liabilities | Amount (₹) | Assets | Amount (₹) |
| Capital: | Machinery | 70,000 | |
| Meena 90,000 | Investments | 50,000 | |
| Tina 80,000 | 1,70,000 | Stock | 22,000 |
| Sundry creditors | 60,000 | Sundry Debtors | 1,03,000 |
| Bills payable | 20,000 | Cash at bank | 5,000 |
| 2,50,000 | 2,50,000 |
The assets and liabilities were disposed off as follows:
a) Machinery were given to creditors in full settlement of their account and stock were given bills payable in full settlement.
b) Investment were took over by Tina at book value. Sundry debtors of book value ₹50,000 took over by Meena at 10% less and remaining debtors realised ₹51,000.
c) Realisation expenses amount to ₹2,000.
When a creditor accepts an asset whose value is more than the amount due to him, he will..............the excess amount which will be credited to.............Account.
Answer & explanation
Correct answer: option 3
The correct answer is Option (3) → Pay, Realisation
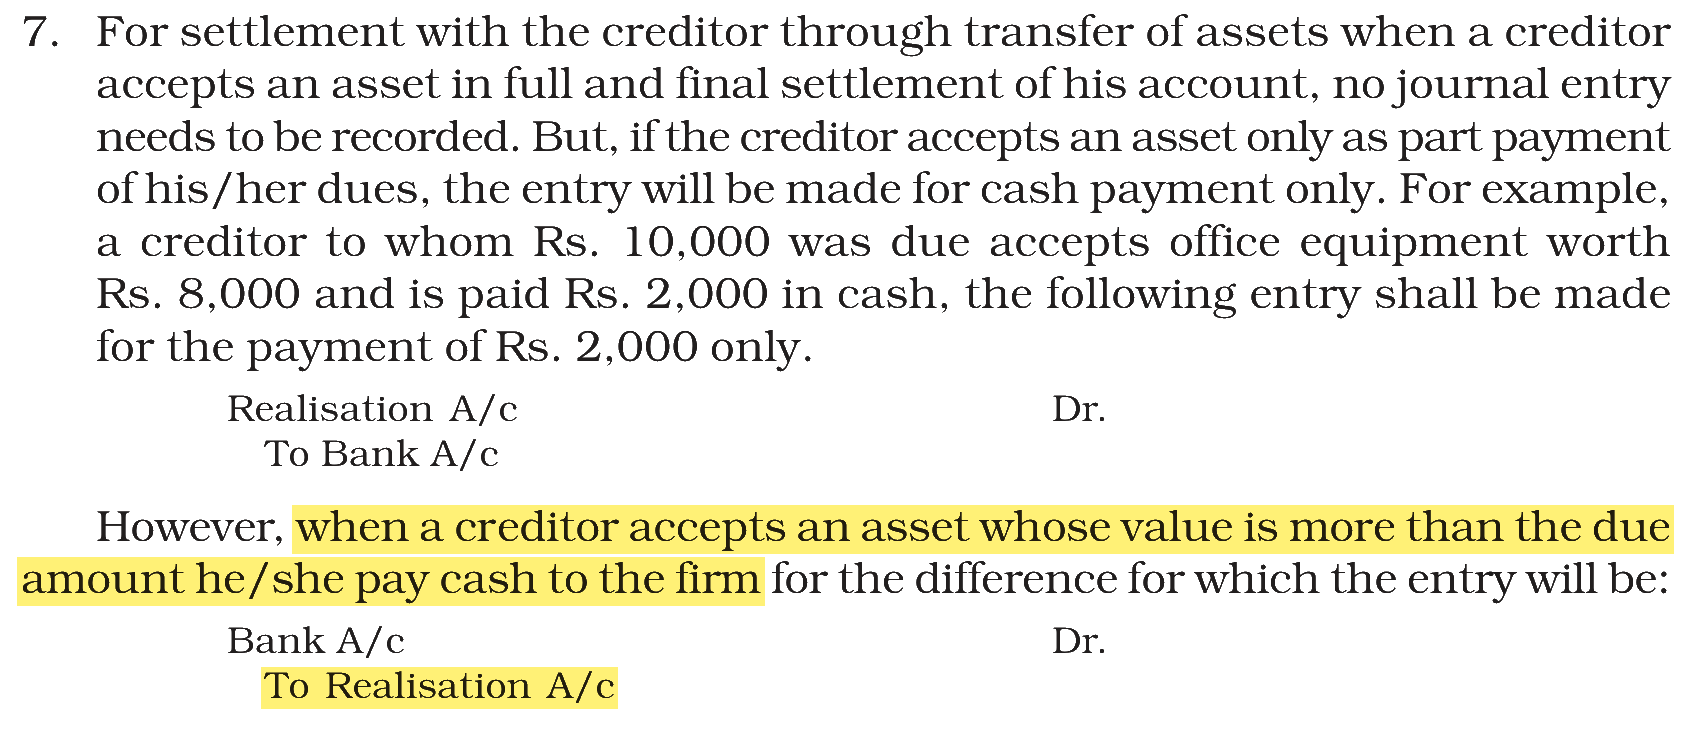
If the asset a creditor accepts is worth more than his dues, he must make up the difference, so he pays cash to the firm. The firm receives cash on realisation, so the entry is Bank A/c Dr. To Realisation A/c.
Why the other options are incorrect
Option (1) Pay, Bank — Incorrect. The cash received is debited to Bank; the credit, the account the excess is credited to, is Realisation.
Option (2) Not pay, Creditors — Incorrect. The creditor gets more than he is owed, so he cannot keep the excess free; and the Creditors Account is already closed by transfer to Realisation.
Option (4) Not pay, Realisation — Incorrect. Realisation is the right account, but the creditor does pay the excess.
NCERT (2026-27 edition):
|