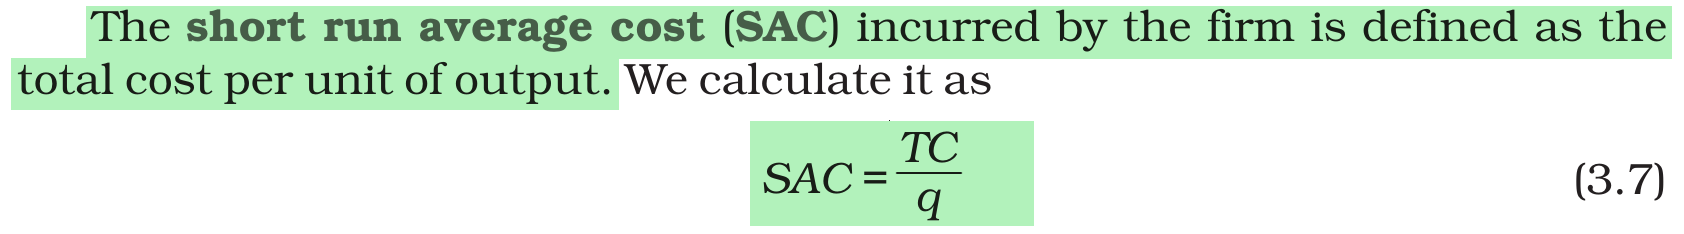
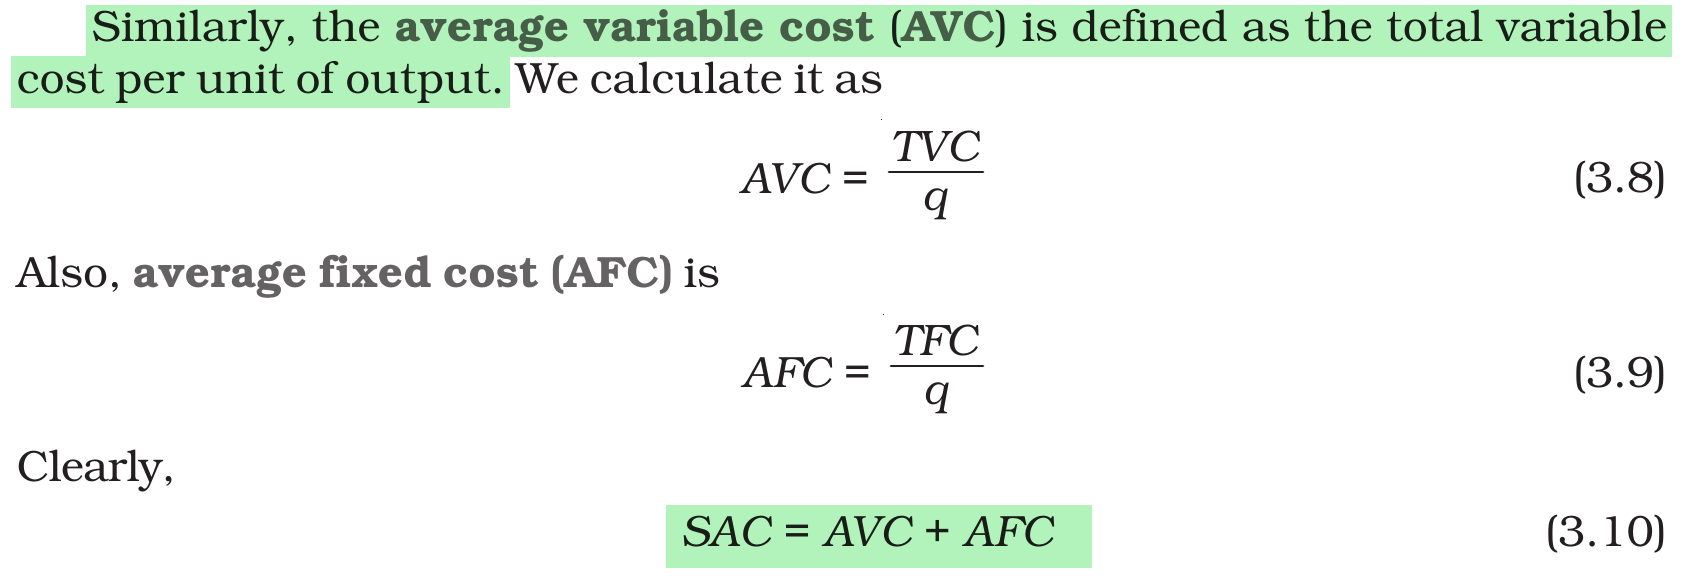
Choose the correct options with reference to short-run average costs.
(A) Average total cost = total cost/quantity of output
(B) Average total cost = average variable cost + average fixed cost
(C) Average variable cost = average total cost - average fixed cost
(D) Average fixed cost = average variable cost - average cost
Choose the correct answer from the options given below:
Answer & explanation
Correct answer: option 2
The correct answer is Option (2) → (A), (B) and (C) only
Average total cost is also called short run average cost. Total cost is made up of total variable cost and total fixed cost. Dividing each by output gives the average costs.
(A) Average total cost = total cost/quantity of output — Correct. Average total cost is the total cost per unit of output.
(B) Average total cost = average variable cost + average fixed cost — Correct. Total cost is variable cost plus fixed cost. Dividing both sides by output gives this relation.
(C) Average variable cost = average total cost - average fixed cost — Correct. This is relation (B) with average fixed cost moved to the other side.
(D) Average fixed cost = average variable cost - average cost — Incorrect. From (B), average fixed cost = average cost − average variable cost. The statement has the subtraction the wrong way round, and it would make fixed cost negative.
NCERT (2026-27): Introductory Microeconomics — Chapter 3: Production and Costs
|