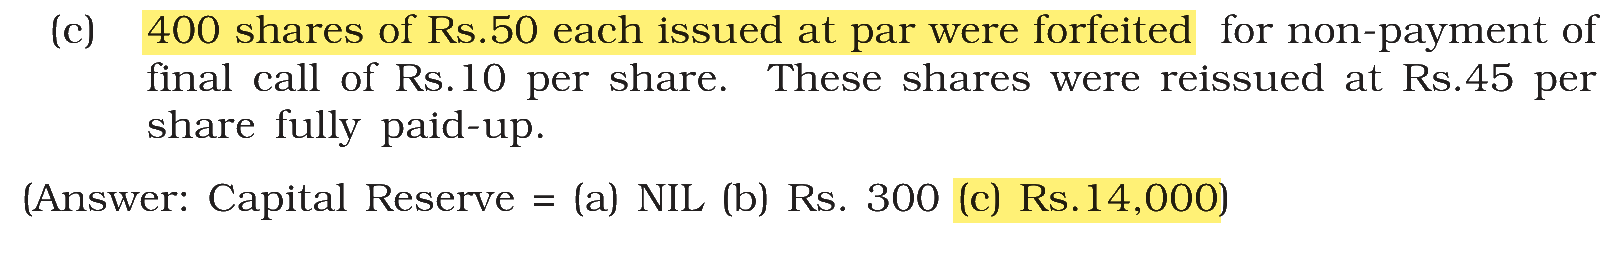
400 shares of ₹50 each issued at par were forfeited for non-payment of the final call of ₹10 per share. These shares were reissued at ₹45 per share as fully paid-up. The amount transferred to capital reserve:
Answer & explanation
Correct answer: option 2
The correct answer is Option (2) → ₹14,000
Capital reserve = amount forfeited on the shares reissued − discount allowed on reissue.
Amount received per share before forfeiture = ₹50 − ₹10 = ₹40
Amount forfeited = 400 × ₹40 = ₹16,000
Discount on reissue per share = ₹50 − ₹45 = ₹5
Total discount = 400 × ₹5 = ₹2,000
Capital reserve = ₹16,000 − ₹2,000 = ₹14,000
₹16,000 is the whole amount forfeited; only what is left after meeting the discount on reissue is a capital profit.
NCERT (2026-27 edition):
|