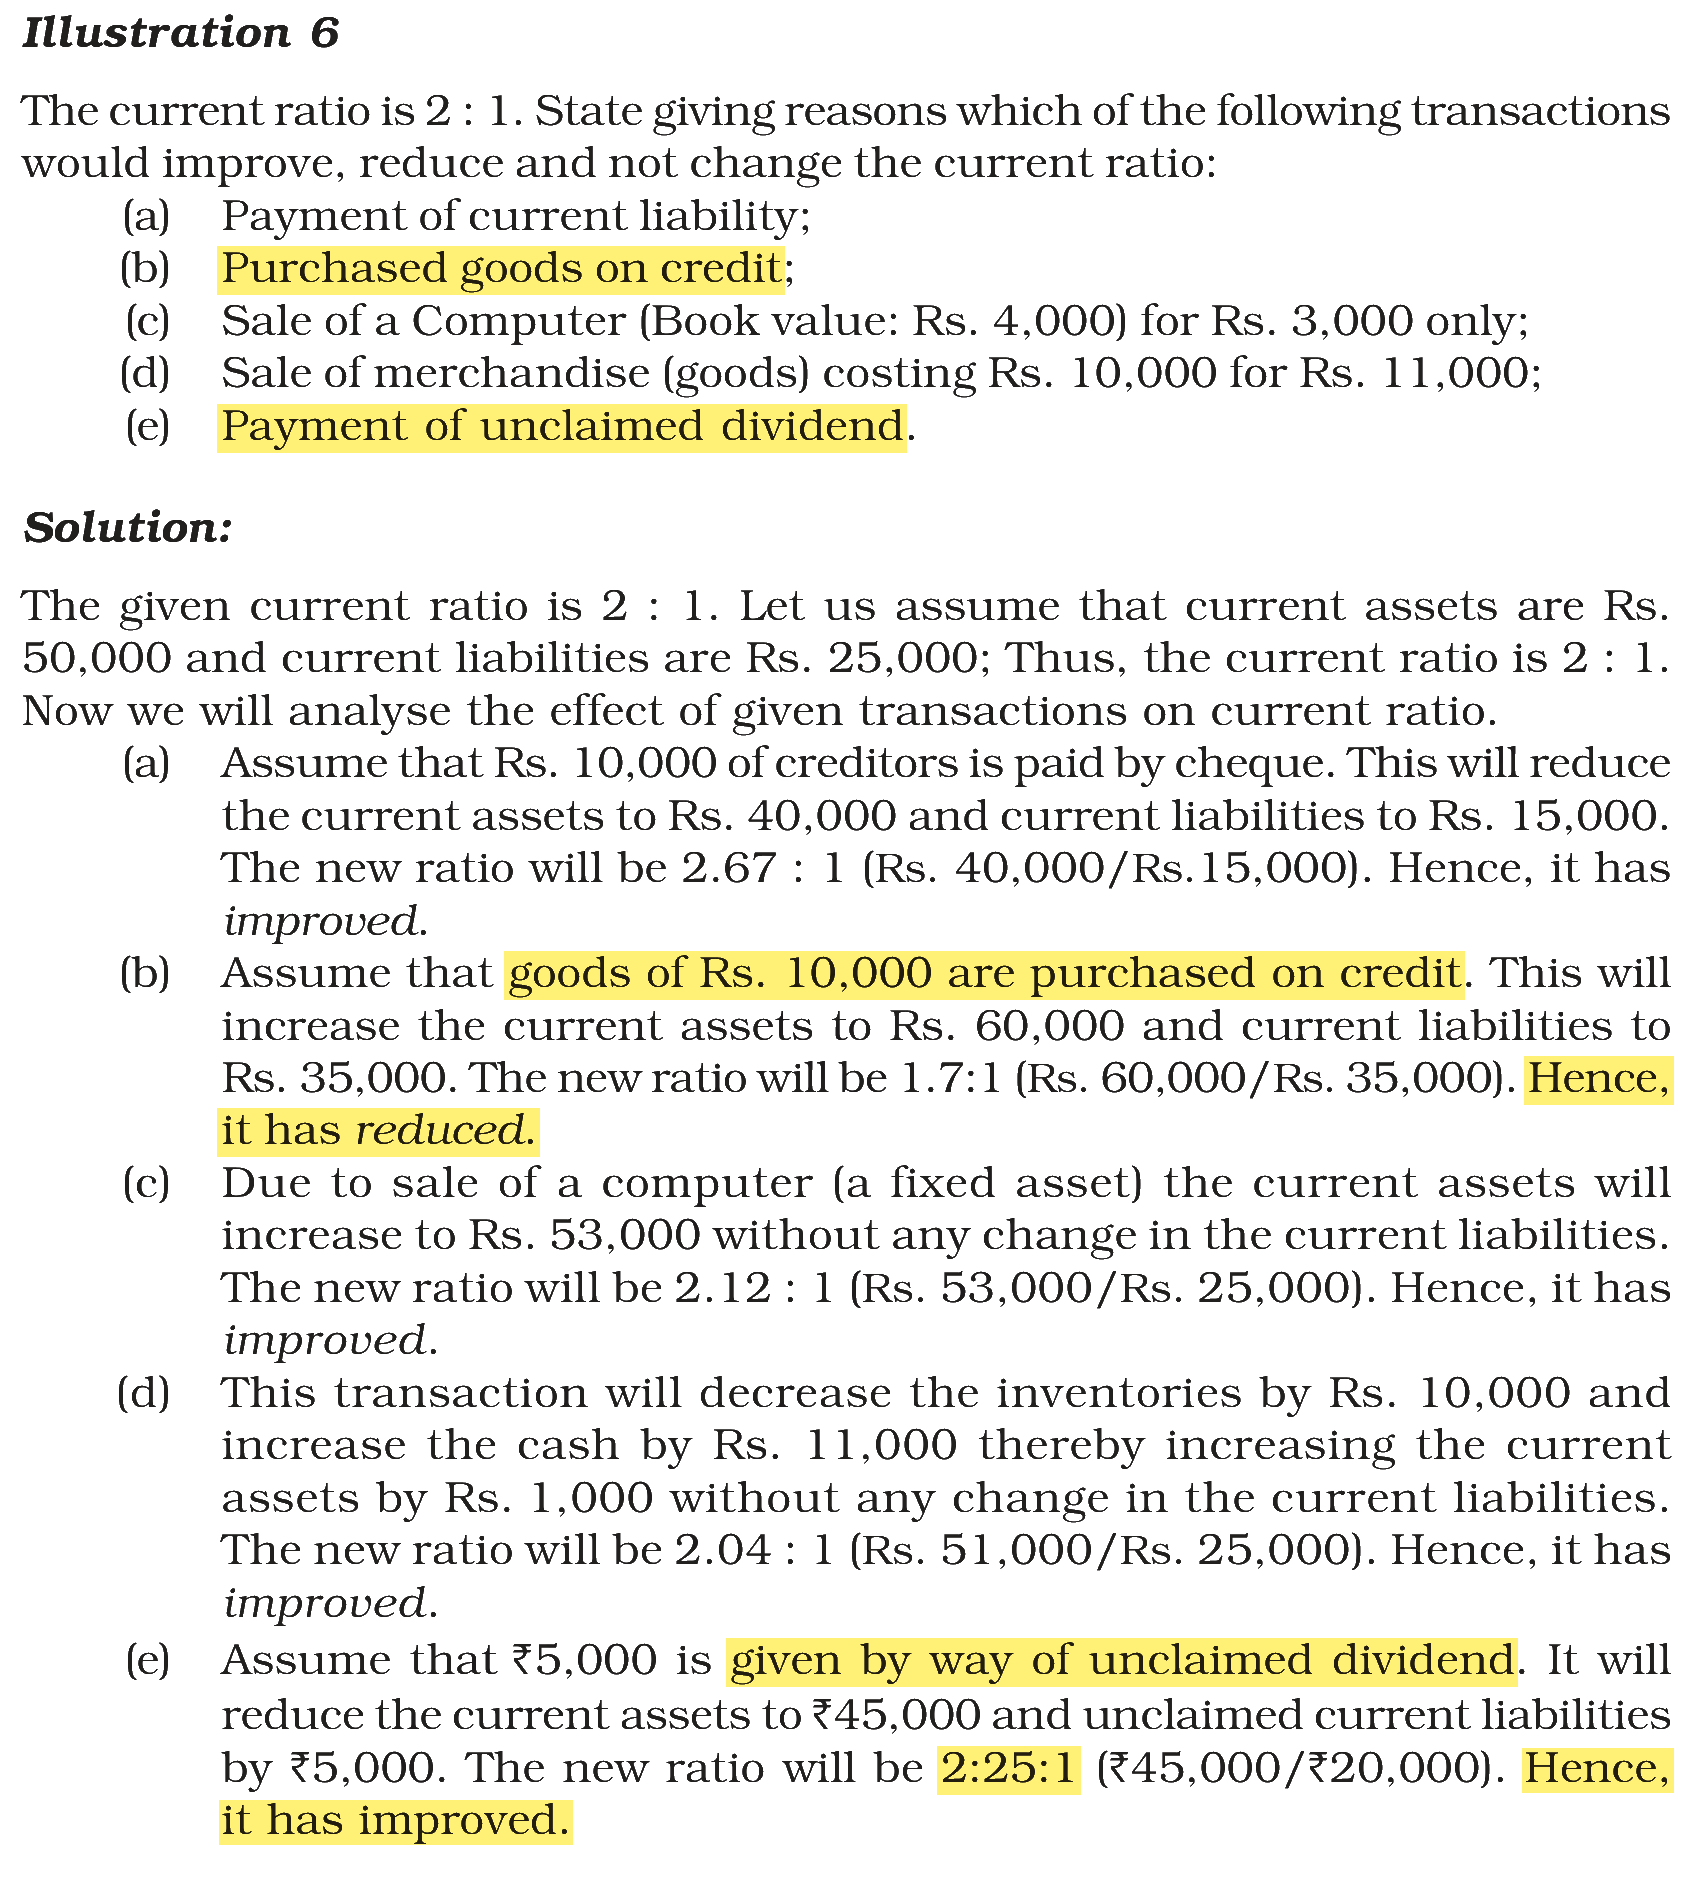
The current ratio is 2 : 1. Which of the following transactions would improve, reduce or change the current ratio? Match List-I with List-II
List-I
(A) Payment of unclaimed dividend
(B) Purchase of Machinery against Issue of Shares
(C) Sale of goods on credit
(D) Purchased goods on credit
List-II
(I) Improve
(II) Reduce
(III) Will not be recorded
(IV) Does not Change
Choose the correct answer from the options given below:
Answer & explanation
Correct answer: option 2
The correct answer is Option (2) → (A) - (I), (B) - (III), (C) - (IV), (D) - (II)
The current ratio is current assets ÷ current liabilities. When it is more than 1 (here 2 : 1), an equal fall in both sides raises it and an equal rise in both sides lowers it. A transaction that touches neither side leaves it unchanged.
(A) Payment of unclaimed dividend — this matches (I) Improve. Cash (a current asset) and unclaimed dividend (a current liability) fall by the same amount. Taking Rs. 50,000 : Rs. 25,000 and a payment of Rs. 5,000, the ratio becomes Rs. 45,000 : Rs. 20,000 = 2.25 : 1.
(B) Purchase of Machinery against Issue of Shares — this matches (III) Will not be recorded. Machinery is a fixed asset and share capital is not a current liability, so the transaction does not enter the current ratio at all.
(C) Sale of goods on credit — this matches (IV) Does not Change. Inventory goes out and debtors come in, both current assets; taken at cost, current assets stay the same and so does the ratio.
(D) Purchased goods on credit — this matches (II) Reduce. Inventory and creditors rise by the same amount. With Rs. 10,000 of goods, the ratio becomes Rs. 60,000 : Rs. 35,000 = 1.7 : 1.
Note: (B) can also be matched with (IV) “Does not Change”, because the purchase is recorded in the books but touches no current asset or current liability; and (C) can also be matched with (I) “Improve” if the goods are sold at a profit, as in the book’s example of goods costing Rs. 10,000 sold for Rs. 11,000. The answer given by NTA follows the pairing used above.
NCERT (2026-27 edition):
|