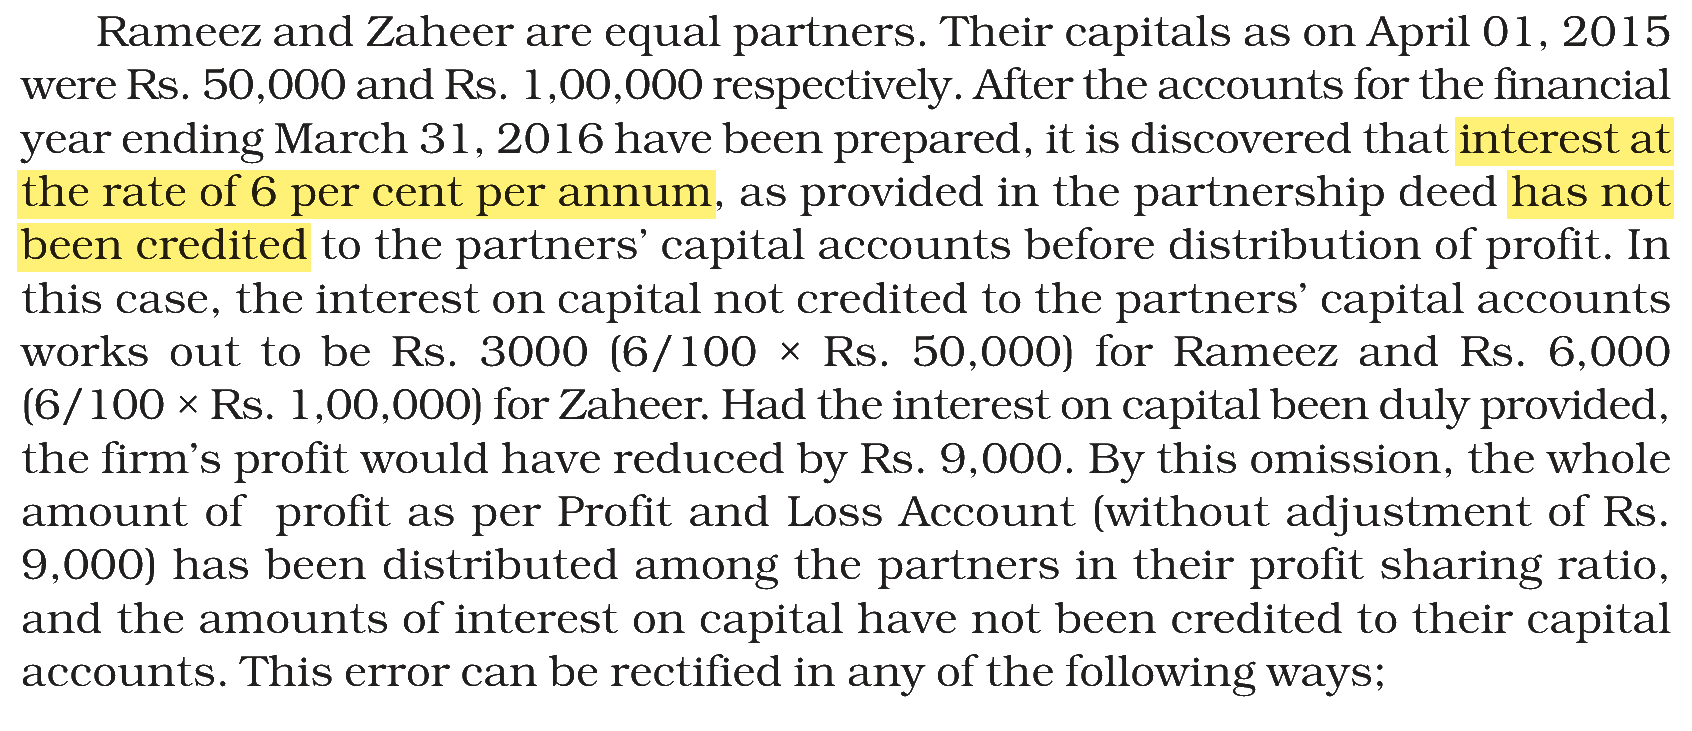
Ramesh and Naresh are equal partners. Their capitals as on April 01, 2025 were Rs. 50,000 and Rs. 1,00,000 respectively. After the accounts for the financial year ending March 31, 2026 have been prepared, it is discovered that interest at the rate of 6 per cent per annum, as provided in the partnership deed has not been credited to the partners' capital accounts. Choose the correct adjusting entry from the options given below.
Answer & explanation
Correct answer: option 1
The correct answer is Option (1) → Ramesh's Capital Account debited and Naresh's Capital Account credited with Rs. 1,500
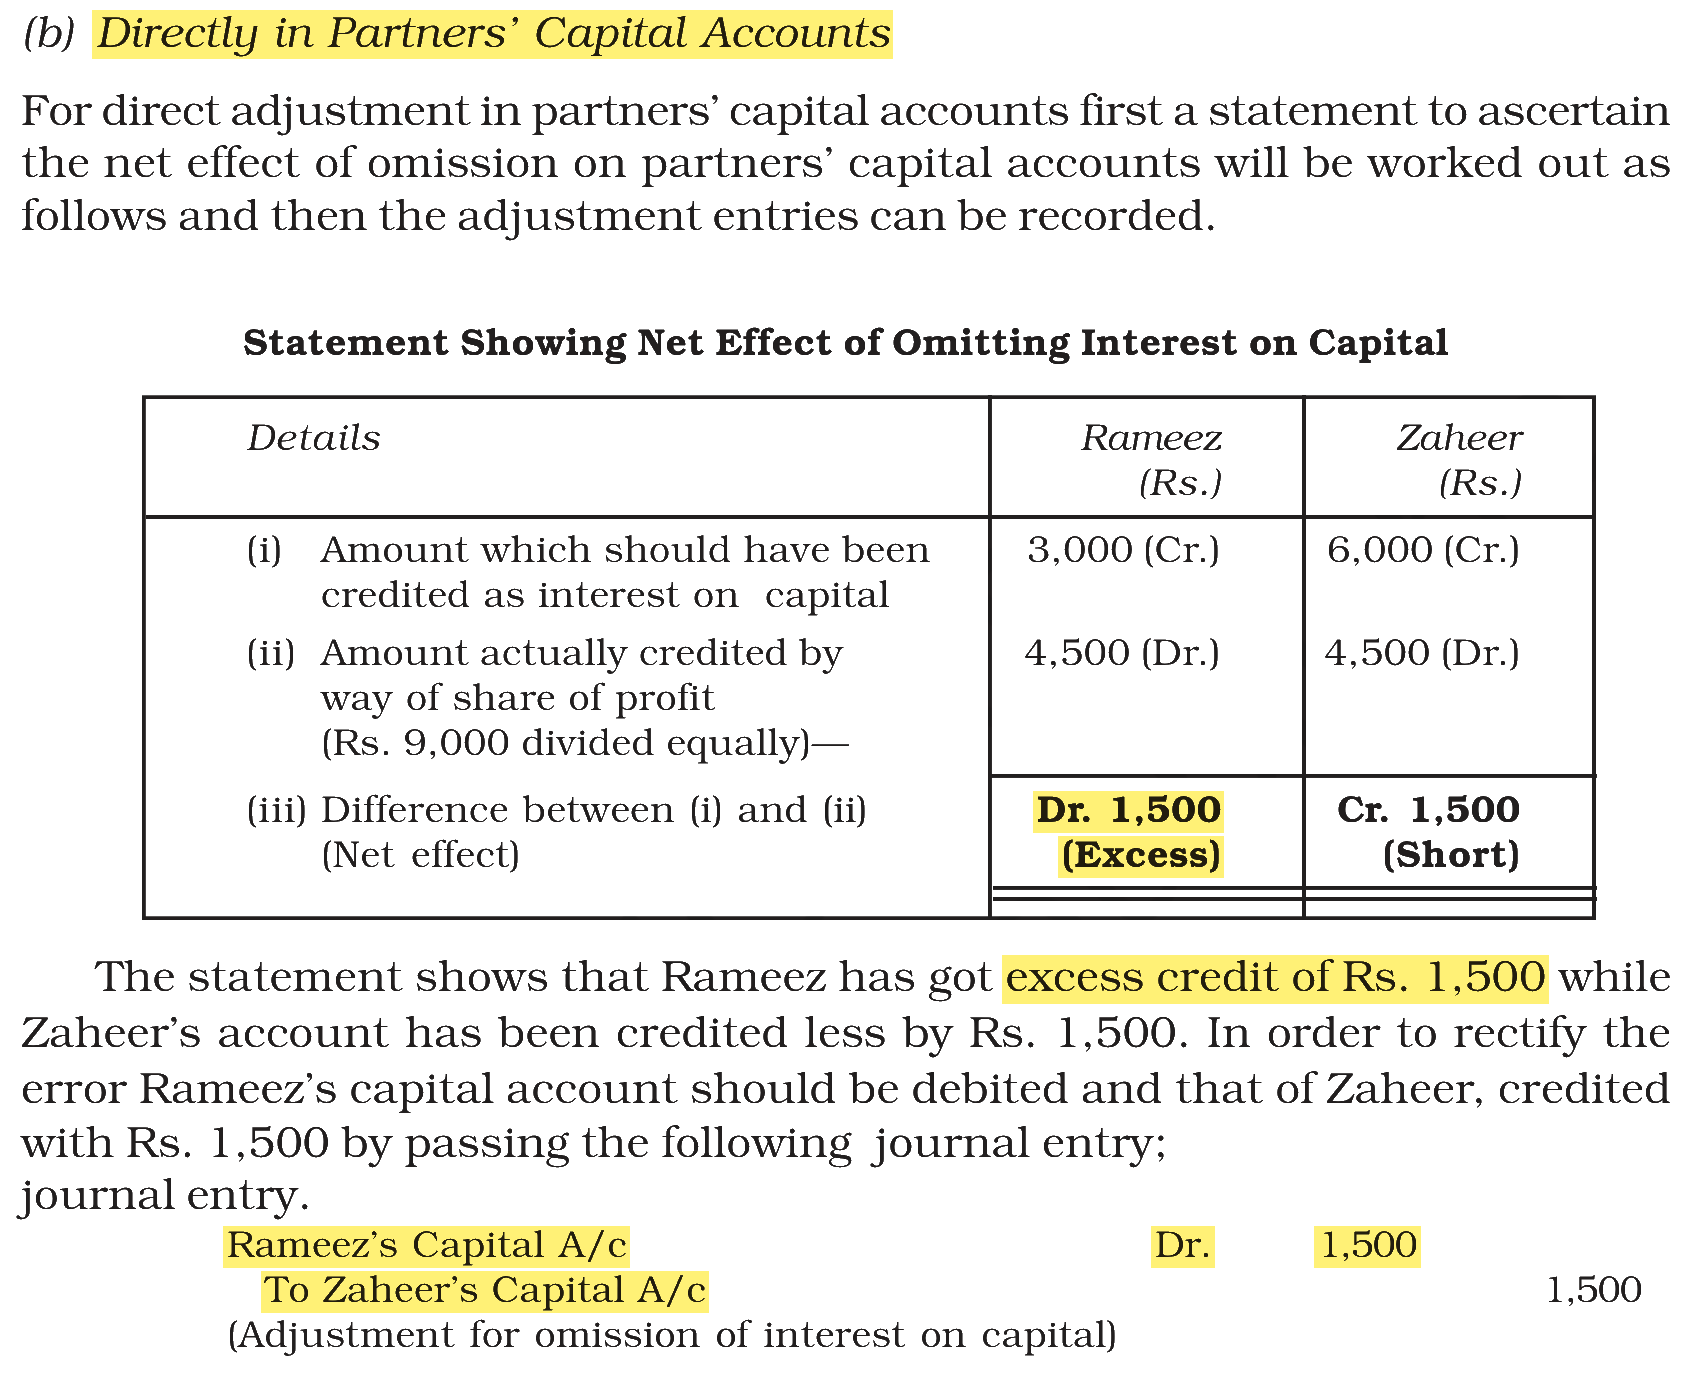
When interest on capital is left out after the profit has been divided, each partner should get his interest, and the profit shared out should be lower by the same total. The adjusting entry records only the net effect on each partner.
Interest due to Ramesh = Rs. 50,000 × 6% = Rs. 3,000
Interest due to Naresh = Rs. 1,00,000 × 6% = Rs. 6,000
Total interest = Rs. 9,000, so the profit shared out was too high by Rs. 9,000
Excess profit taken by each (equal partners) = Rs. 4,500
Ramesh: Rs. 3,000 − Rs. 4,500 = Rs. 1,500 excess credit
Naresh: Rs. 6,000 − Rs. 4,500 = Rs. 1,500 short credit
So Ramesh's Capital A/c is debited and Naresh's Capital A/c is credited with Rs. 1,500:
Ramesh's Capital A/c Dr. 1,500
To Naresh's Capital A/c 1,500
Note: This question is from NCERT (2026-27). NTA sets numerical questions from NCERT too, so do not ignore NCERT while practising numericals.
NCERT (2026-27 edition):
|