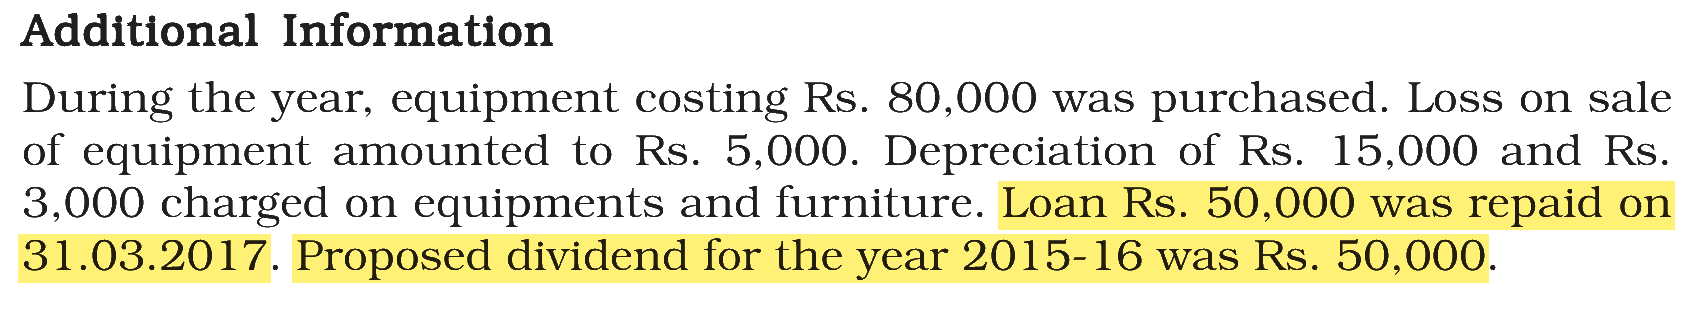Based on the following, answer the question:
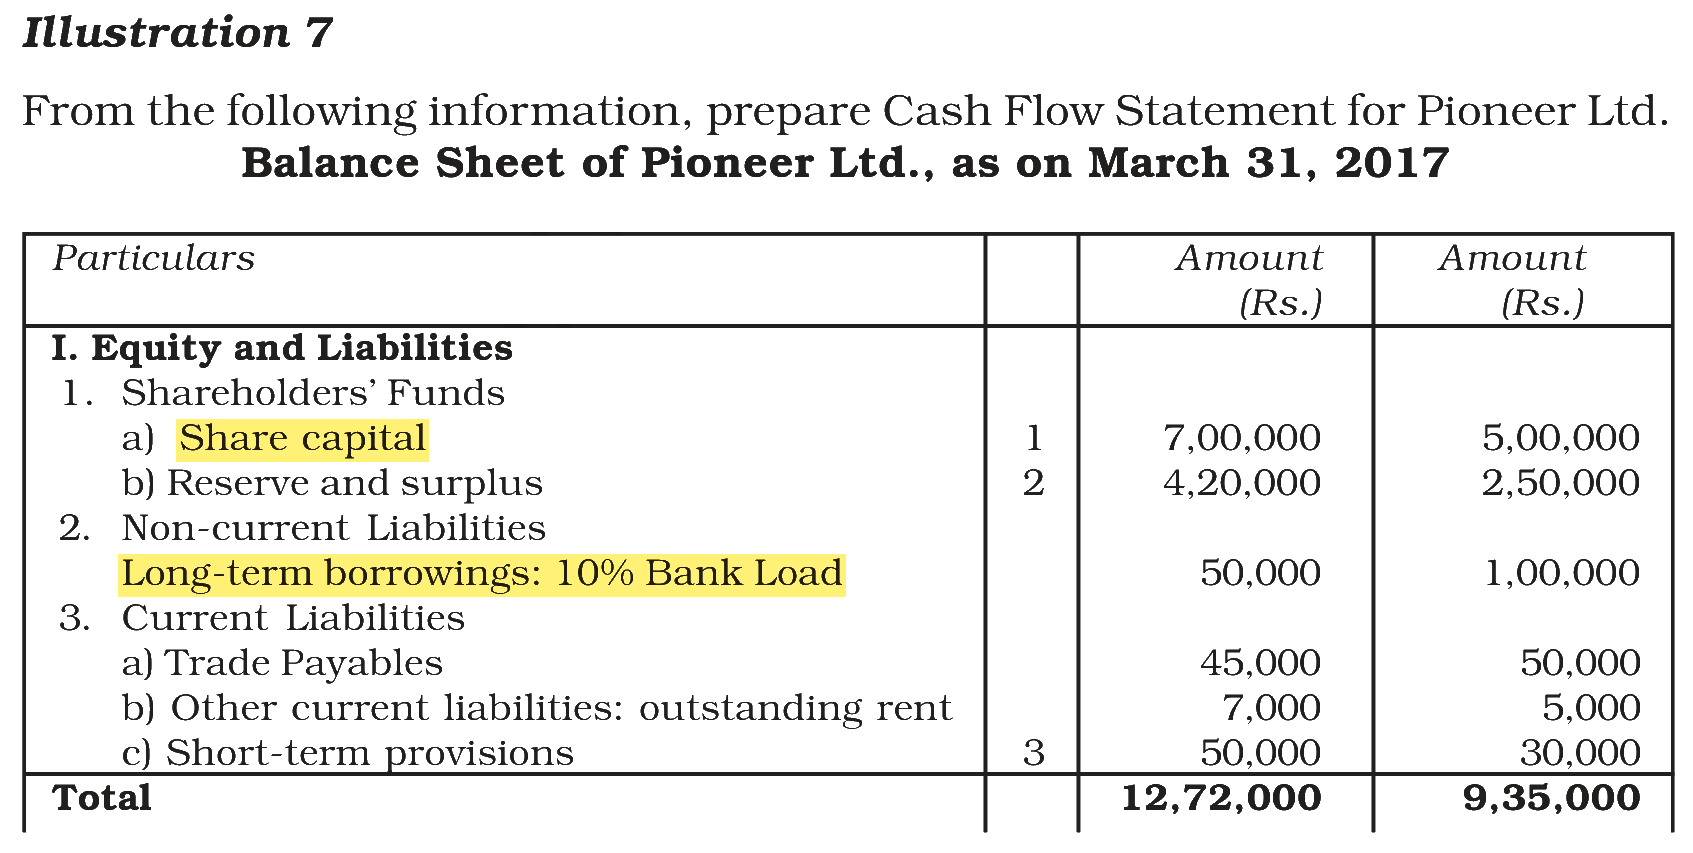
Balance Sheet of Pioneer Ltd., as on March 31, 2017
|
Particulars |
Note |
31st March 2017 (₹) |
31st March 2016 (₹) |
|
I. Equity and Liabilities |
|
|
|
|
1. Shareholders Funds |
|
|
|
|
a) Share Capital |
1 |
7,00,000 |
5,00,000 |
|
b) Reserve and Surplus |
2 |
4,20,000 |
2,50,000 |
|
2. Non-current Liabilities |
|
|
|
|
Long term borrowings: Bank Loan |
|
50,000 |
1,00,000 |
|
3. Current Liabilities |
|
|
|
|
a) Trade payables |
|
45,000 |
50,000 |
|
b) Other current liabilities: Outstanding rent |
|
7,000 |
5,000 |
|
c) Short-term provisions |
3 |
50,000 |
30,000 |
|
Total |
|
12,72,000 |
9,35,000 |
|
II. Assets |
|
|
|
|
1. Non-current assets |
|
|
|
|
a) Fixed assets |
|
|
|
|
(i) Tangible assets |
4 |
5,00,000 |
5,00,000 |
|
(ii) Intangible assets |
5 |
95,000 |
1,00,000 |
|
b) Non-current investments |
|
1,00,000 |
…. |
|
2. Current assets |
|
|
|
|
a) Inventories |
|
1,30,000 |
50,000 |
|
b) Trade receivables |
|
1,20,000 |
80,000 |
|
c) Cash and Cash equivalents |
6 |
3,27,000 |
2,05,000 |
|
Total |
|
12,72,000 |
9,35,000 |
Notes to Accounts:
|
Particulars |
31st March 2017 (₹) |
31st March 2016 (₹) |
|
1. Equity share capital |
7,00,000 |
5,00,000 |
|
2. Reserve and Surplus |
|
|
|
Surplus: i.e., Balance in statement of Profit and Loss |
4,20,000 |
2,50,000 |
|
3. Short term provision: |
|
|
|
Provision for Taxation |
50,000 |
30,000 |
|
4. Fixed Assets |
|
|
|
Tangible assets |
|
|
|
- Equipment |
2,30,000 |
2,00,000 |
|
- Furniture |
2,70,000 |
3,00,000 |
|
|
5,00,000 |
5,00,000 |
|
5. Intangible Assets |
|
|
|
Patents |
95,000 |
1,00,000 |
|
6. Cash and Cash equivalents |
|
|
|
i) Cash |
27,000 |
5,000 |
|
ii) Bank balance |
3,00,000 |
2,00,000 |
|
|
3,27,000 |
2,05,000 |
During the year, equipment costing ₹80,000 was purchased. Loss on sale of equipment amounted to ₹5,000. Depreciation of ₹15,000 and ₹30,000 charged on equipment and furniture respectively. Proposed Dividend for the year 2015-16 was ₹50,000, which was paid during the year.
Calculate the amount of cash flow from financing activities.
Answer & explanation
Correct answer: option 1
The correct answer is Option (1) → Inflow of ₹1,00,000
Financing activities are those that change the owners’ capital and the long-term borrowings.
Issue of equity share capital (₹7,00,000 − ₹5,00,000) = ₹2,00,000 inflow
Repayment of bank loan (₹1,00,000 − ₹50,000) = ₹50,000 outflow
Payment of the proposed dividend of 2015-16 = ₹50,000 outflow
Net cash flow from financing activities = 2,00,000 − 50,000 − 50,000 = ₹1,00,000 inflow
Note 1: In the NCERT illustration the loan is a 10% bank loan (the book prints “Bank Load” for “Bank Loan”), so its solution also shows interest of ₹10,000 paid and a financing inflow of ₹90,000. This question gives no rate of interest on the bank loan, so no interest is taken.
Note 2: The book prints “Rs. 3,000” for the depreciation on furniture; its own working uses Rs. 30,000 (Rs. 3,00,000 − Rs. 2,70,000), the figure given in this question.
NCERT (2026-27 edition):
NCERT (2026-27 edition):
|