Read the following passage and answer the questions.
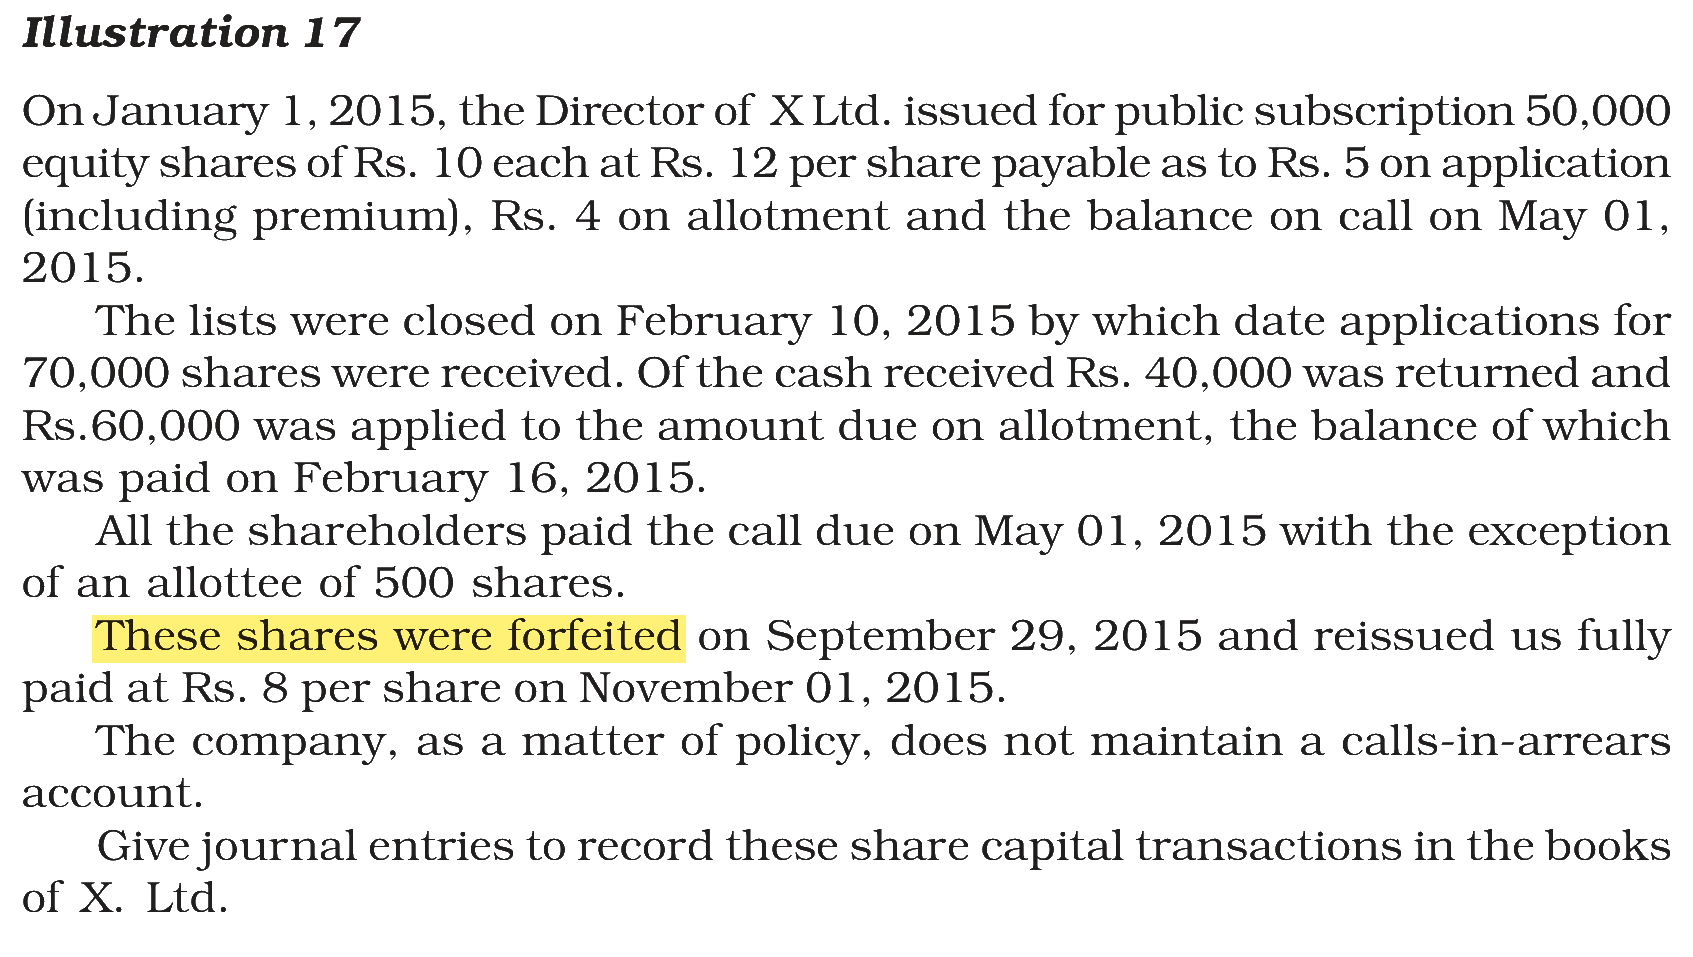
On January 1, 2024, the Director of X Ltd. issued for public subscription 50,000 equity shares of ₹10 each at ₹12 per share payable, ₹5 on application (including premium), ₹4 on allotment and the balance on call on May 01, 2024. The issue was closed on February 10, 2024 by which date applications for 70,000 shares were received. Of the cash received ₹40,000 was returned and ₹60,000 was applied to the amount due on allotment, the balance of which was paid on February 16, 2024. All the shareholders paid the call due on May 01, 2024 with the exception of an allottee of 500 shares. These shares were forfeited on September 29, 2024 and reissued as fully paid at ₹8 per share on November 01, 2024. The company, as a matter of policy, does not maintain a calls-in-arrears account.
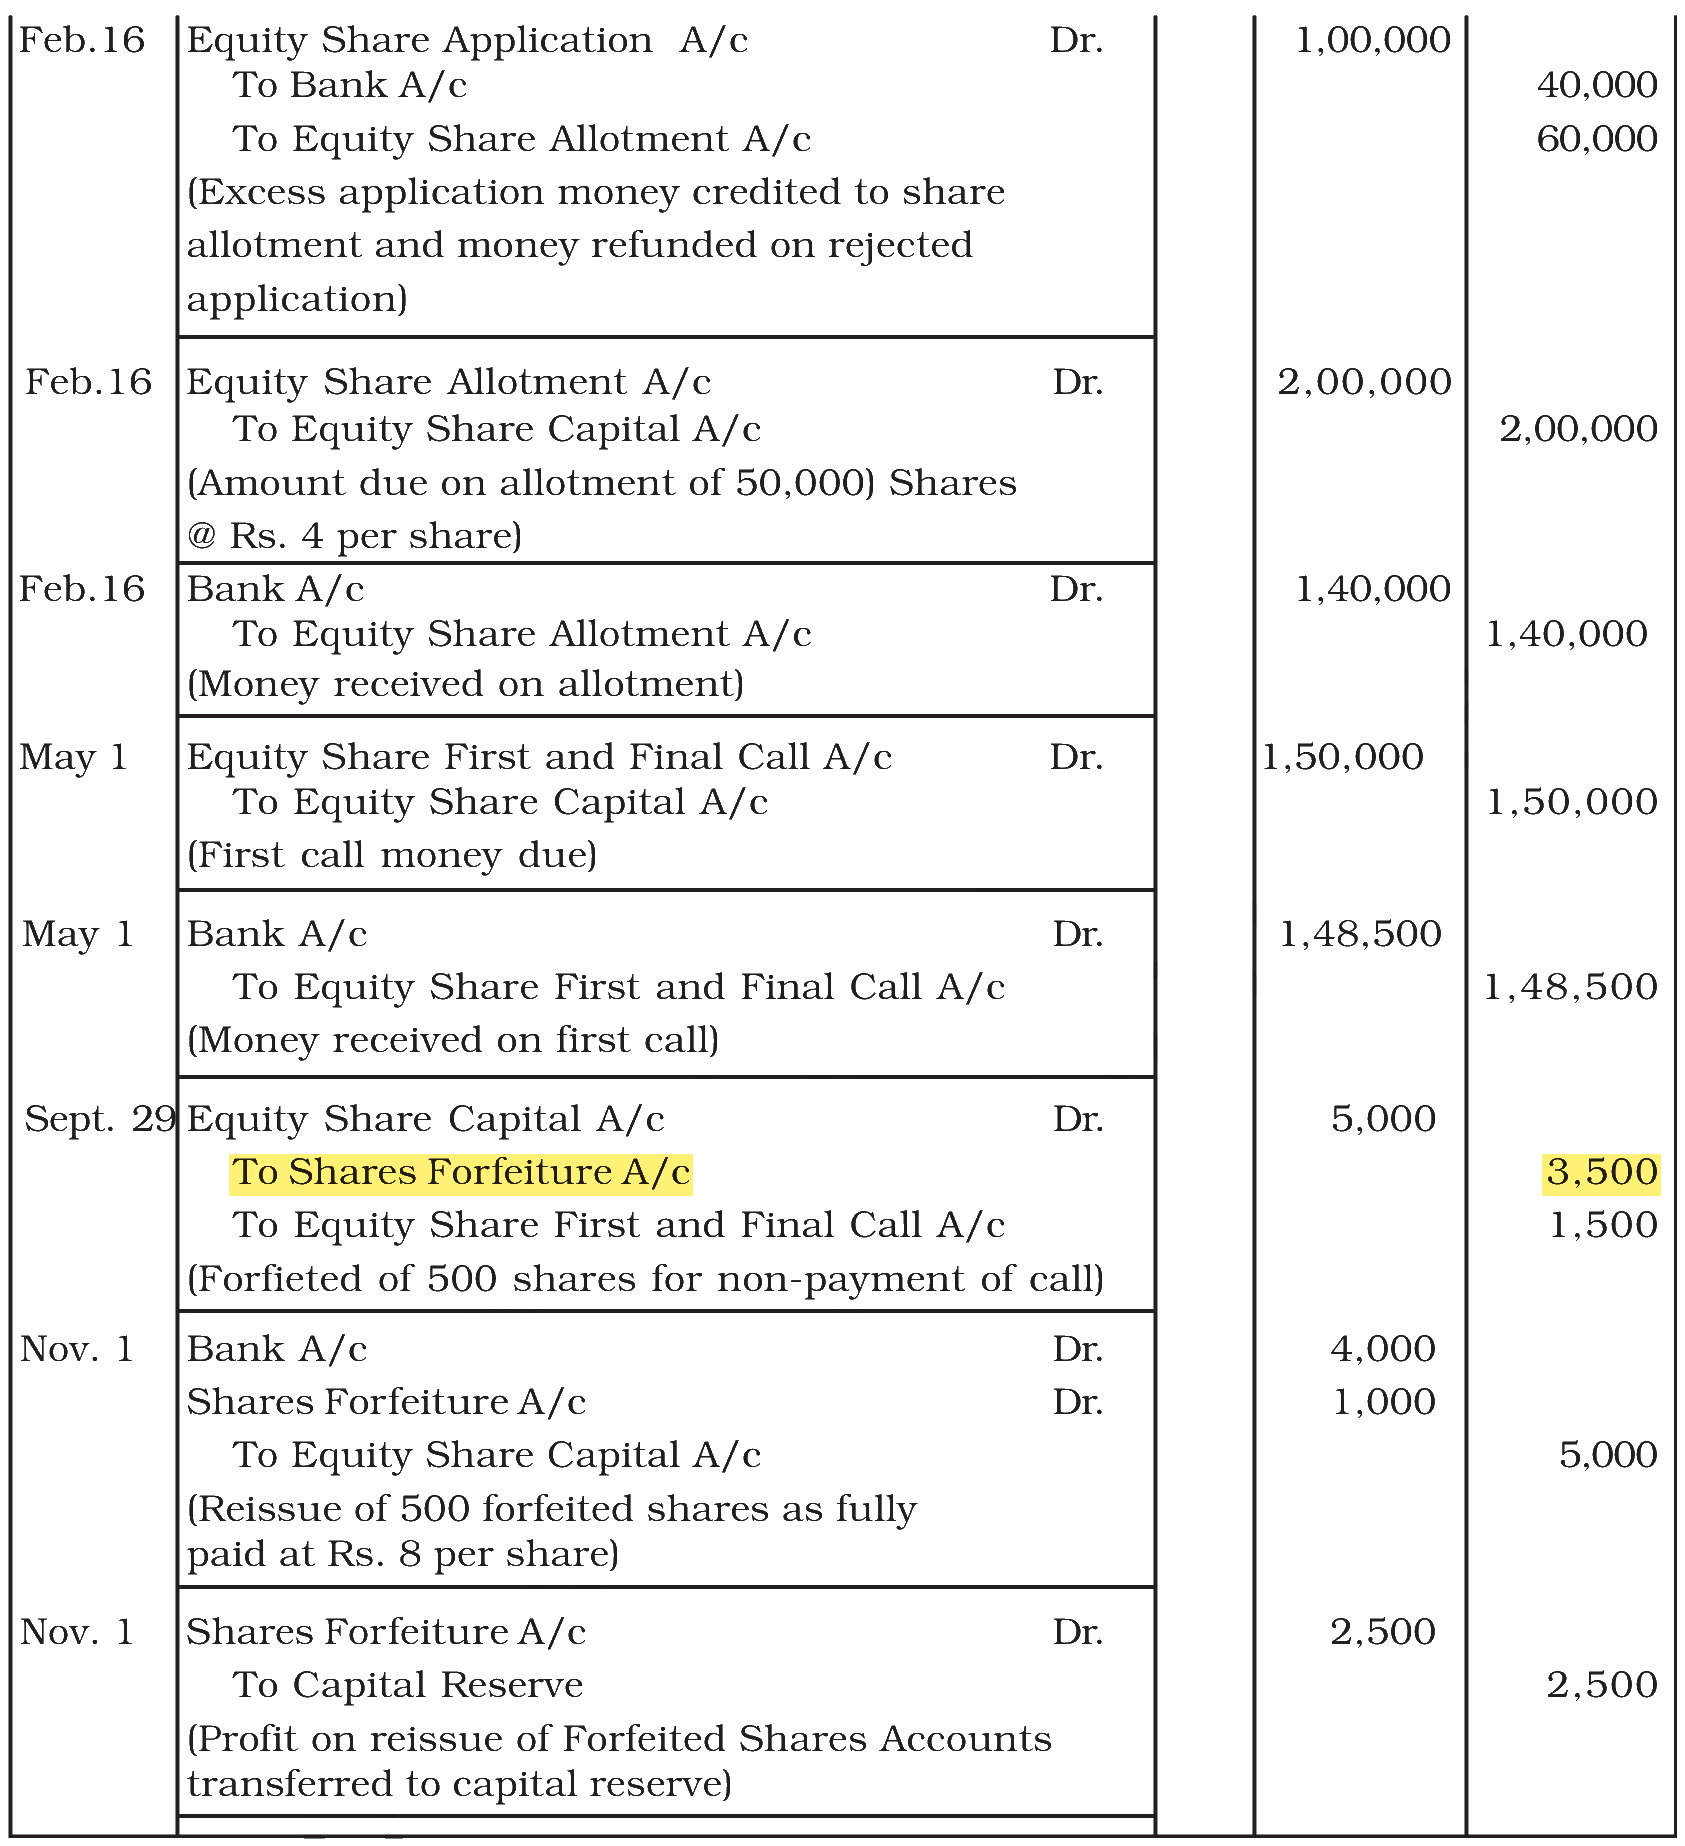
On forfeiture of 500 shares for non-payment of call money, what amount will be credited to Shares Forfeiture Account?
Answer & explanation
Correct answer: option 2
The correct answer is Option (2) → Rs. 3,500
When shares are forfeited, Share Capital is debited with the amount called up on them, the unpaid call is credited to the call account, and the amount already received on those shares is credited to Shares Forfeiture Account. The premium already received stays in Securities Premium Reserve and is not reversed.
Working for 500 shares (issue price Rs. 12 = Rs. 10 face value + Rs. 2 premium):
Called up per share = Rs. 10 (the full face value, since the call is the last instalment)
Call unpaid per share = Rs. 12 − Rs. 5 − Rs. 4 = Rs. 3
Received towards capital per share = Rs. 10 − Rs. 3 = Rs. 7
Shares Forfeiture A/c = 500 × Rs. 7 = Rs. 3,500
NCERT (2026-27 edition):
NCERT (2026-27 edition):
|