Read the passage carefully and answer the questions based on the passage:
Short run Costs
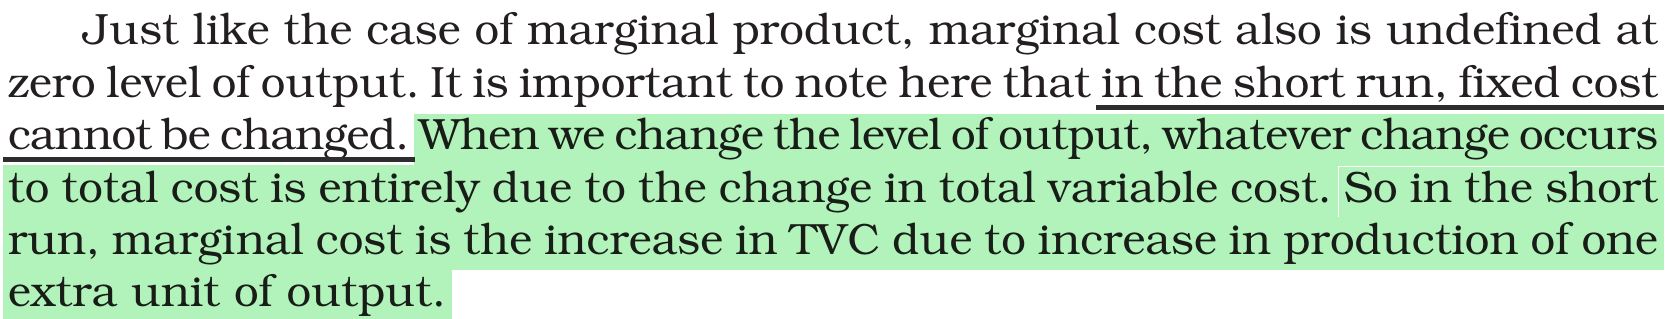
In the short run, some of the factors of production cannot be varied. The cost that a firm incurs to employ fixed inputs is called the total fixed cost. Whatever amount of output the firm produces, this cost remains fixed for the firm. To produce any required level of output, the firm, in the short run, can adjust only variable inputs. Accordingly, the cost that a firm incurs to employ these variable inputs is called the total variable cost. Adding the fixed and the variable costs, we get the total cost of a firm. In order to increase the production of output, the firm must employ more of the variable inputs. As a result, the total variable cost and total cost will increase. Therefore, as output increases, the total variable cost and total cost increase. Marginal cost is the increase in total variable cost due to an increase in production of one extra unit of output. For any level of output, the sum of marginal costs up to that level gives us the total variable cost at that level.
An increase in production of one extra unit of output will lead to an increase in ____.
Answer & explanation
Correct answer: option 3
The correct answer is Option (3) → Total Variable Cost.
To produce one extra unit, the firm must employ more of the variable inputs. So its total variable cost (TVC) rises. The passage calls this rise in TVC the marginal cost.
Option (1) Marginal Cost. — Incorrect. Marginal cost is the name of that increase in TVC. It first falls and then rises as output grows, so one extra unit does not always raise it.
Option (2) Total Fixed Cost. — Incorrect. This is the cost of the fixed inputs. It stays the same whatever the output.
Option (3) Total Variable Cost. — Correct. More output needs more variable inputs, so this cost always goes up.
Option (4) Average Cost. — Incorrect. Average cost is the cost per unit of output. Its curve is ‘U’-shaped, so it first falls and then rises as output grows.
Note: The passage of this question is taken from the section on short run costs in the chapter ‘Production and Costs’ of the NCERT book (Introductory Microeconomics). Learn the short run cost definitions word by word, because NTA turns them into several questions.
NCERT (2026-27): Introductory Microeconomics — Chapter 3: Production and Costs
|