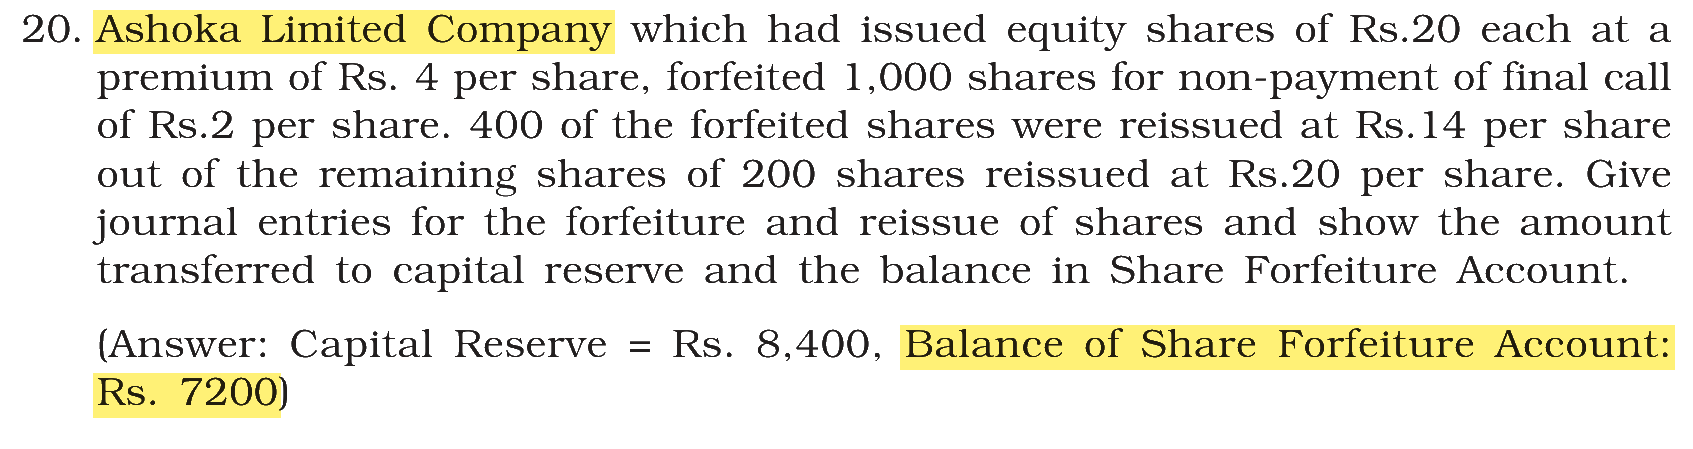Ashoka Limited Company, which had issued equity shares of Rs. 20 each at a premium of Rs. 4 per share, forfeited 1,000 shares for non-payment of final call of Rs. 2 per share. 400 of the forfeited shares were reissued at Rs. 14 per share out of the remaining shares of 200 shares reissued at Rs. 20 per share. Balance of Share Forfeiture Account after reissue of shares will be:
Answer & explanation
Correct answer: option 3
The correct answer is Option (3) → Rs. 7,200
On forfeiture, Share Forfeiture Account is credited with the amount received on the shares, excluding the premium. On reissue, any discount is met from it, and the balance relating to the shares reissued goes to Capital Reserve. What remains is the forfeited amount on the shares not yet reissued.
Amount received per share (excluding premium) = Rs. 20 − Rs. 2 (final call unpaid) = Rs. 18
Forfeited on 1,000 shares = 1,000 × Rs. 18 = Rs. 18,000
Shares reissued = 400 + 200 = 600; shares not reissued = 400
Discount on 400 shares reissued at Rs. 14 = 400 × Rs. 6 = Rs. 2,400; no discount on 200 shares reissued at Rs. 20
Transferred to Capital Reserve = 600 × Rs. 18 − Rs. 2,400 = Rs. 8,400
Balance of Share Forfeiture Account = Rs. 18,000 − Rs. 2,400 − Rs. 8,400 = Rs. 7,200 (400 × Rs. 18)
NCERT (2026-27 edition):
|