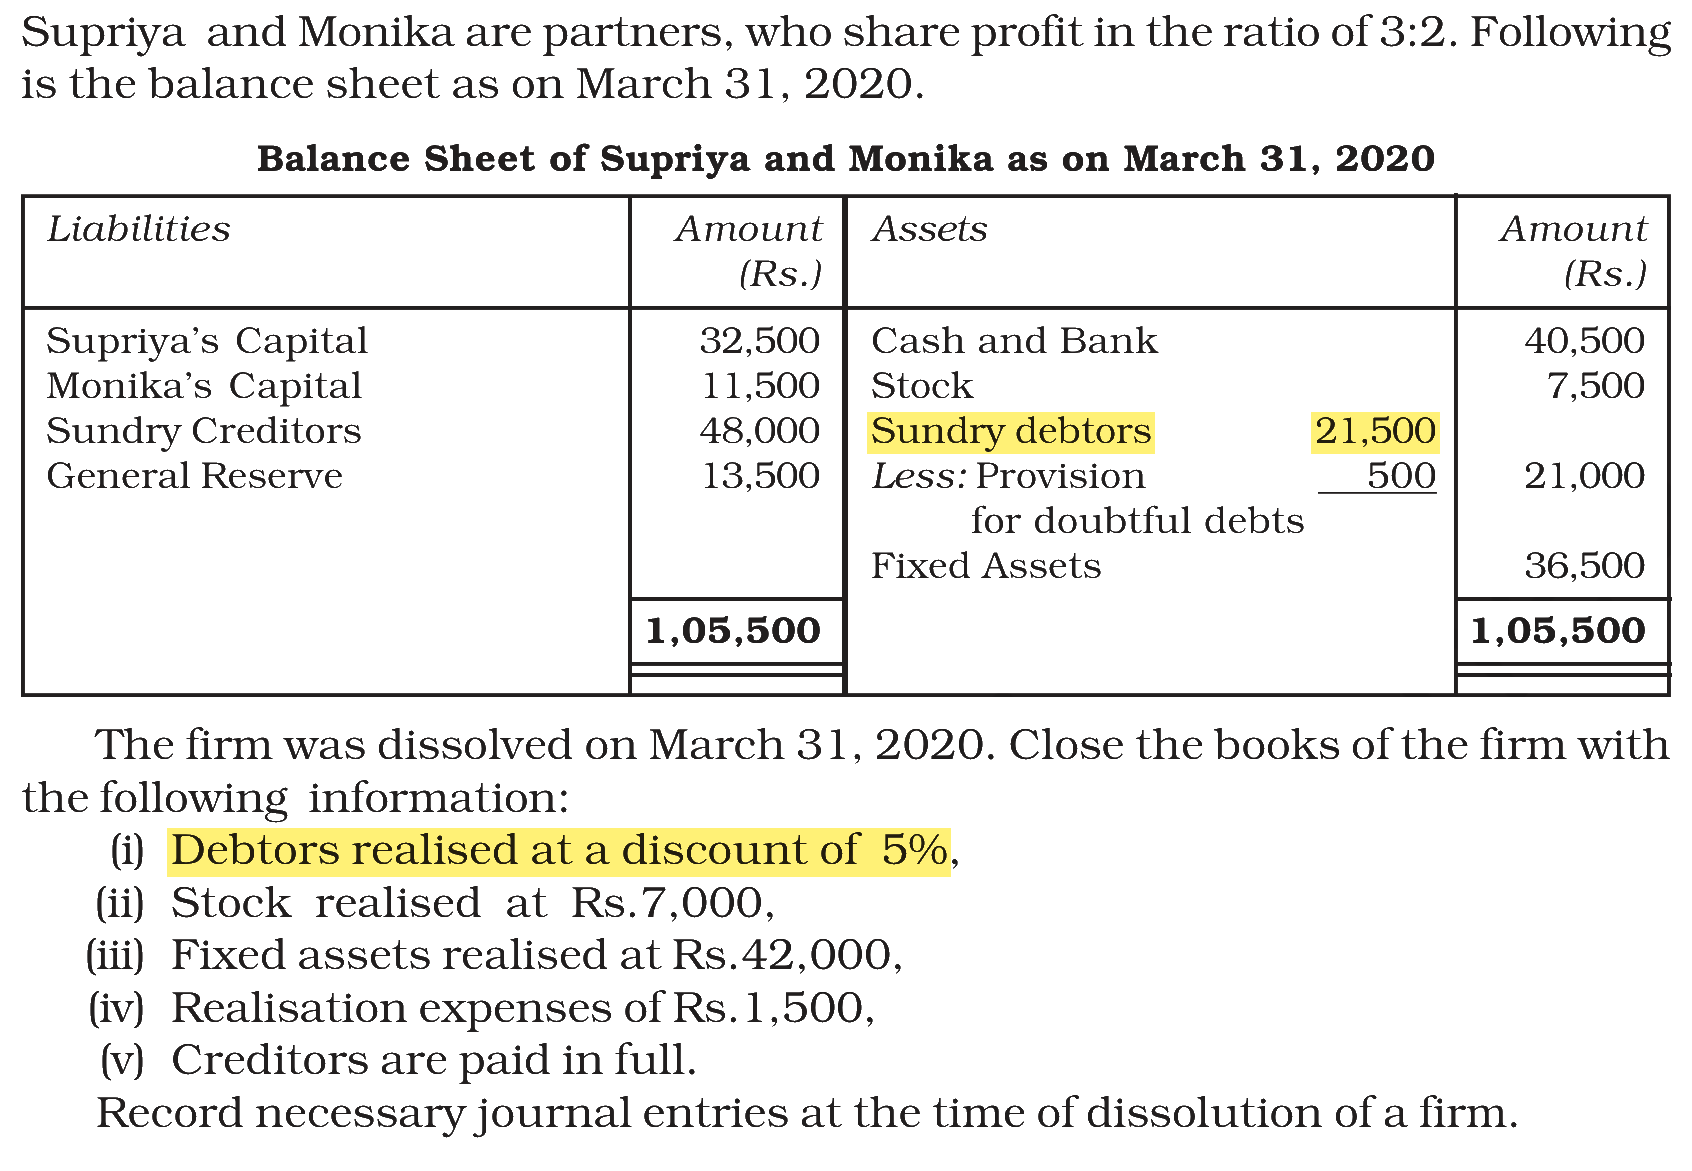
At the time of dissolution of firm, the following information is provided
| Sundry debtors | 21,500 |
| Less: Provision for doubtful debts | 500 |
| 21,000 |
Debtors realised at a discount of 5%,
Journal entry for realisation of debtors would be :
Answer & explanation
Correct answer: option 3
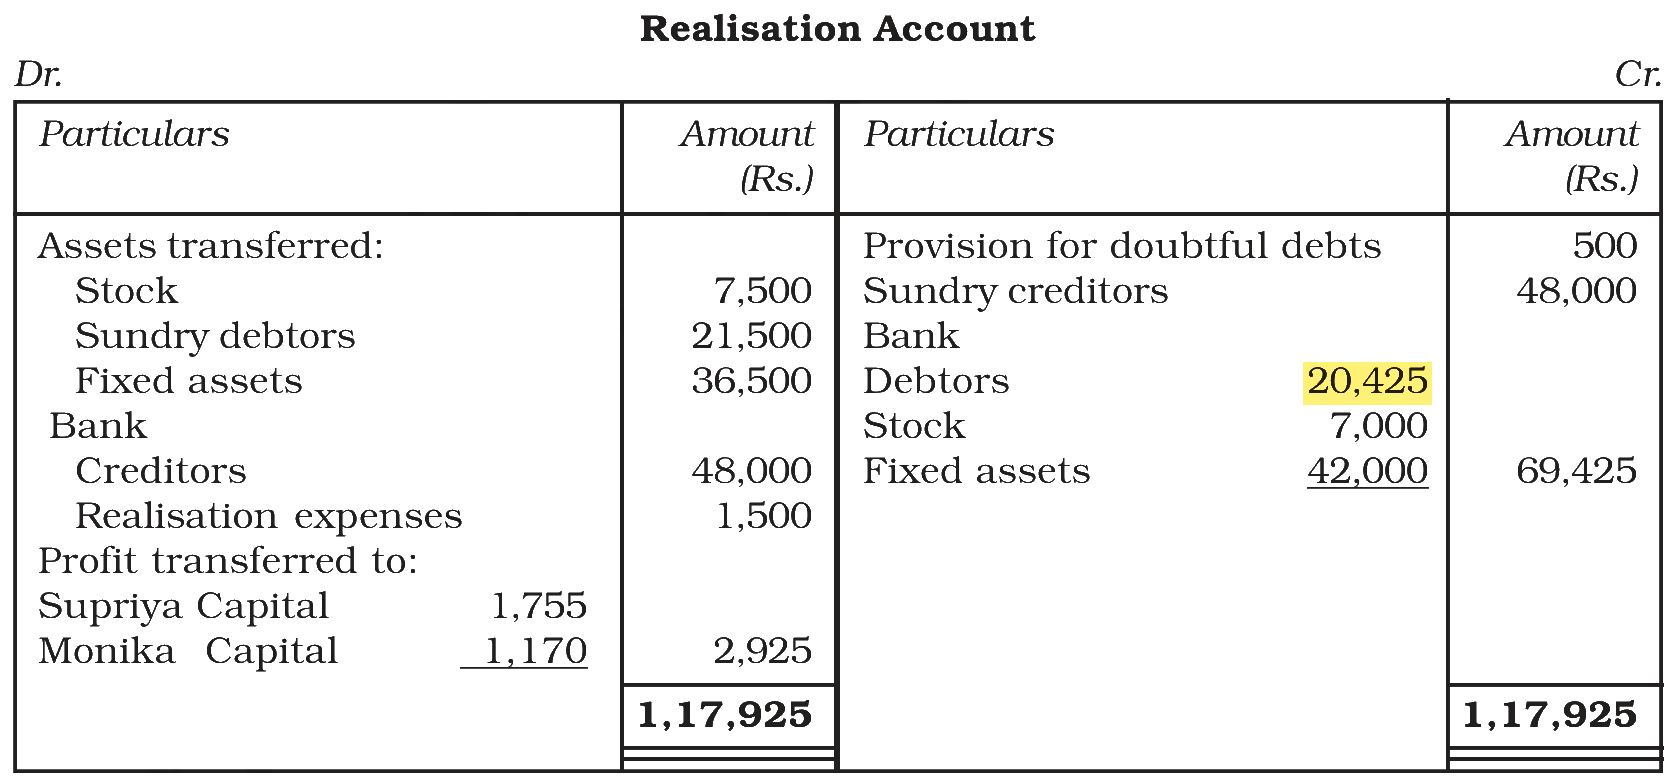
The correct answer is Option (3) → Bank / Cash A/c Dr. 20,425, To Realisation A/c 20,425
On dissolution, sundry debtors go to the Realisation Account at their gross value, and the provision for doubtful debts goes separately to its credit side. So the discount is worked on the gross debtors, not on the net Rs. 21,000.
Sundry debtors (gross) = Rs. 21,500
Discount at 5% = Rs. 21,500 × 5/100 = Rs. 1,075
Cash realised = Rs. 21,500 − Rs. 1,075 = Rs. 20,425
The entry is:
Bank / Cash A/c Dr. 20,425
To Realisation A/c 20,425
The Rs. 500 provision is not set off in this entry; it has already been credited to the Realisation Account with the liabilities. Working 5% on Rs. 21,000 (Rs. 19,950) counts the provision twice.
Note: This question is from NCERT (2026-27). NTA sets numerical questions from NCERT too, so do not ignore NCERT while practising numericals.
NCERT (2026-27 edition):
|