On the death of a partner, his share of loss in the firm from the last balance sheet till the date of his death is transferred to:
Answer & explanation
Correct answer: option 4
The correct answer is Option (4) → Credit of Profit & Loss Suspense Account
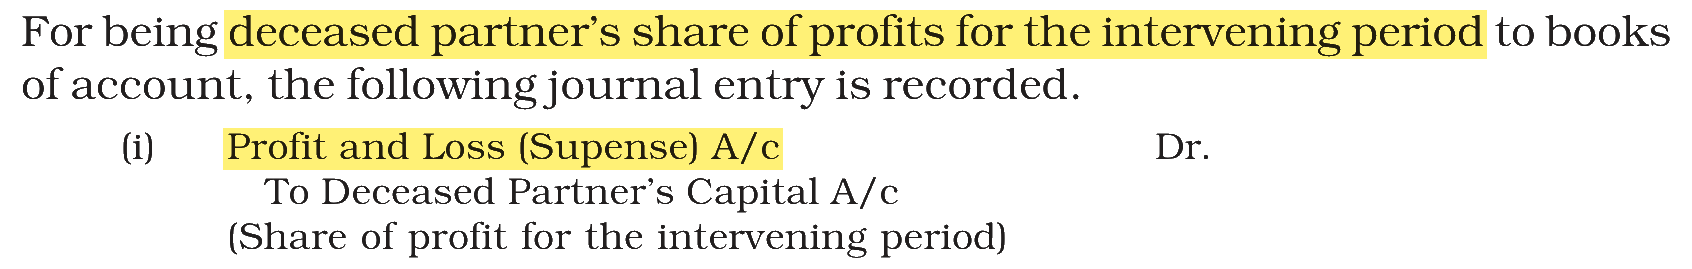
The books are not closed on the day a partner dies, so the firm’s profit or loss from the last balance sheet to the date of death is not yet in the accounts. A Profit & Loss Suspense Account stands in for the profit and loss account of that short period.
Share of profit: Profit & Loss Suspense A/c Dr., To Deceased Partner’s Capital A/c
Share of loss: the entry is reversed, Deceased Partner’s Capital A/c Dr., To Profit & Loss Suspense A/c
A loss reduces what is due to the deceased partner, so his capital account is debited and the suspense account is credited.
Why the other options are incorrect
Option (1) Debit of Profit & Loss Account — Incorrect. The profit and loss account of the year is not prepared on the date of death, so it cannot carry the share of the intervening period.
Option (2) Credit of Profit & Loss Account — Incorrect. For the same reason the profit and loss account is not used; the suspense account takes its place.
Option (3) Debit of Profit & Loss Suspense Account — Incorrect. The suspense account is debited for a share of profit; for a share of loss it is credited.
NCERT (2026-27 edition):
|