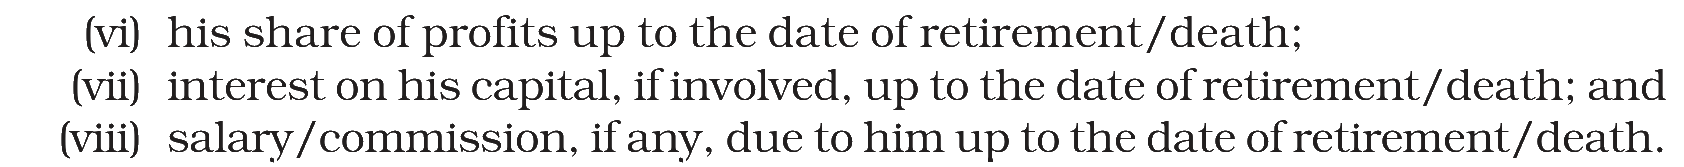In the event of retirement of partner, following deduction has to be made from his/her share.:
Answer & explanation
Correct answer: option 1
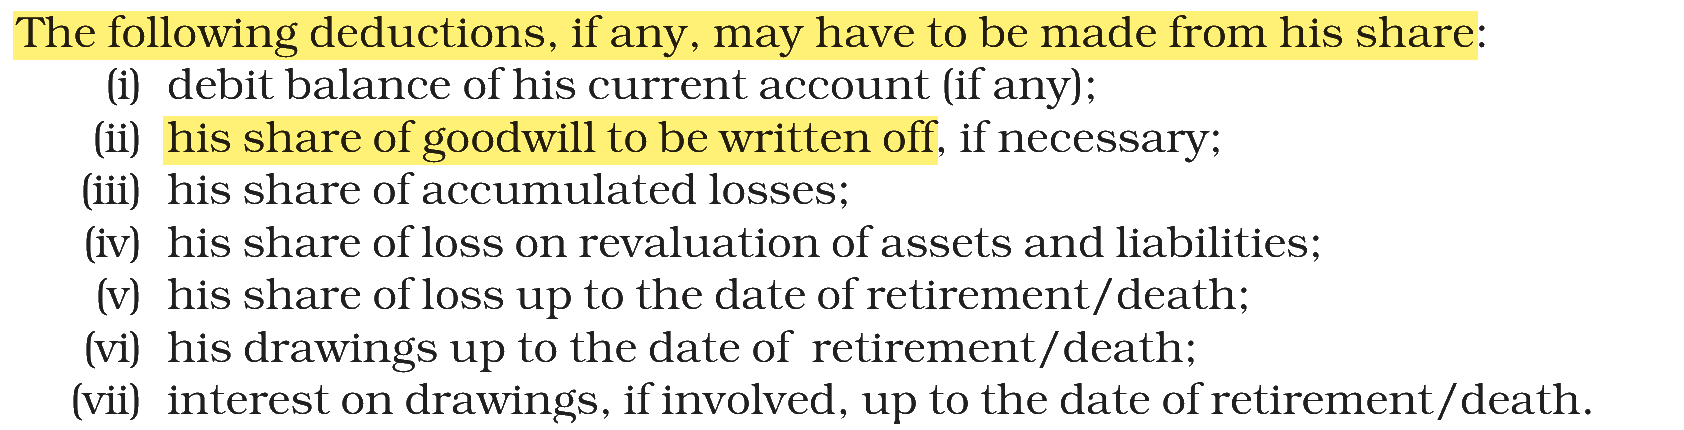
The correct answer is Option (1) → Goodwill to be written off (if any)
The amount due to a retiring partner is built up from what he is owed (credit items) less what he owes or must bear (deductions). Goodwill already shown in the books is written off among all the partners, so the retiring partner’s share of goodwill written off is a deduction from his share.
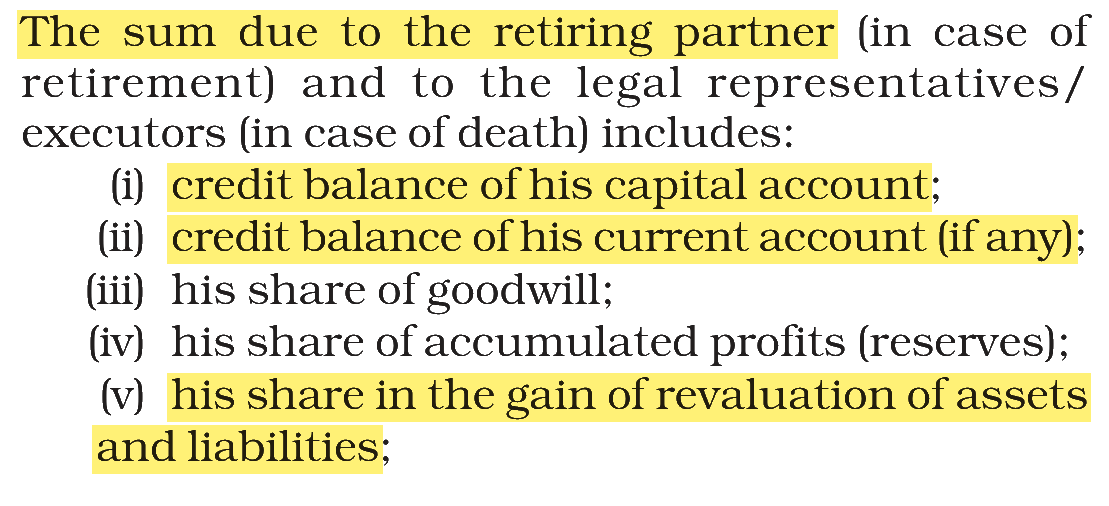
Option (2) Credit balance of his capital account — Incorrect. A credit balance is money the firm owes to him, so it is added, not deducted.
Option (3) Credit balance of his current account (if any) — Incorrect. This too is an amount due to him; only a debit balance of the current account is deducted.
Option (4) His/Her share of profit on revaluation of assets — Incorrect. A gain on revaluation is credited to the retiring partner; only a loss on revaluation is deducted.
NCERT (2026-27 edition):
|