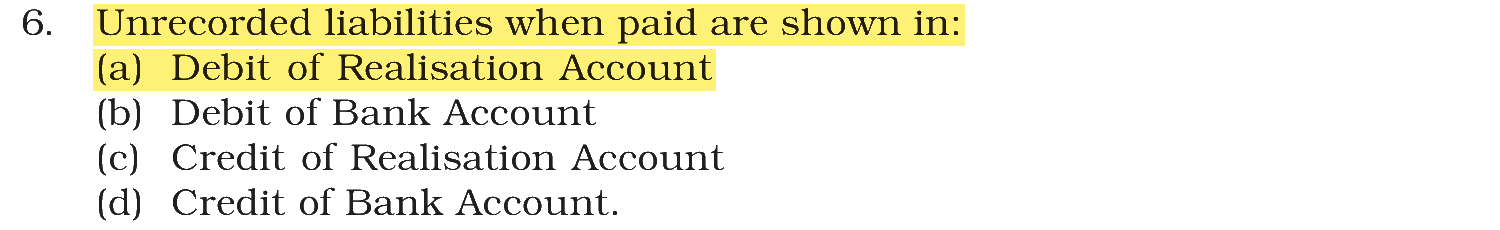
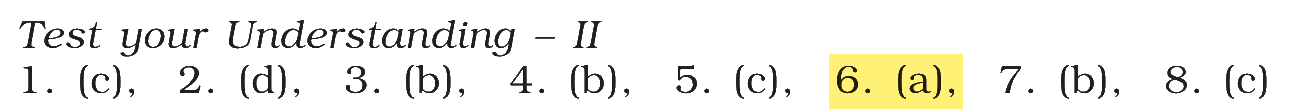Unrecorded liabilities when paid are shown in:
Answer & explanation
Correct answer: option 1
The correct answer is Option (1) → Debit of Realisation Account
On dissolution, every liability is settled through the Realisation Account. A liability that was not recorded in the books, when paid, is a loss on realisation, so the entry is Realisation A/c Dr., To Bank/Cash A/c.
Why the other options are incorrect
Option (2) Debit of Bank Account — Incorrect. Paying money reduces the bank balance, so the Bank Account is credited, not debited.
Option (3) Credit of Realisation Account — Incorrect. The credit side of the Realisation Account records liabilities transferred and assets realised; a payment is a debit.
Option (4) Debit of Revaluation Account — Incorrect. A Revaluation Account is prepared on admission, retirement or death, when the firm goes on. On dissolution the firm closes, and the Realisation Account takes its place.
Note: The NTA answer key accepted two answers for this question, Option (1) and Option (4). As per the textbook, only Option (1) is correct: the book records the settlement of any unrecorded liability as Realisation A/c Dr., To Bank A/c, a debit to the Realisation Account, and the Revaluation Account has no part in that entry. So only one answer is supported by the textbook.
NCERT (2026-27 edition):
NCERT (2026-27 edition): |