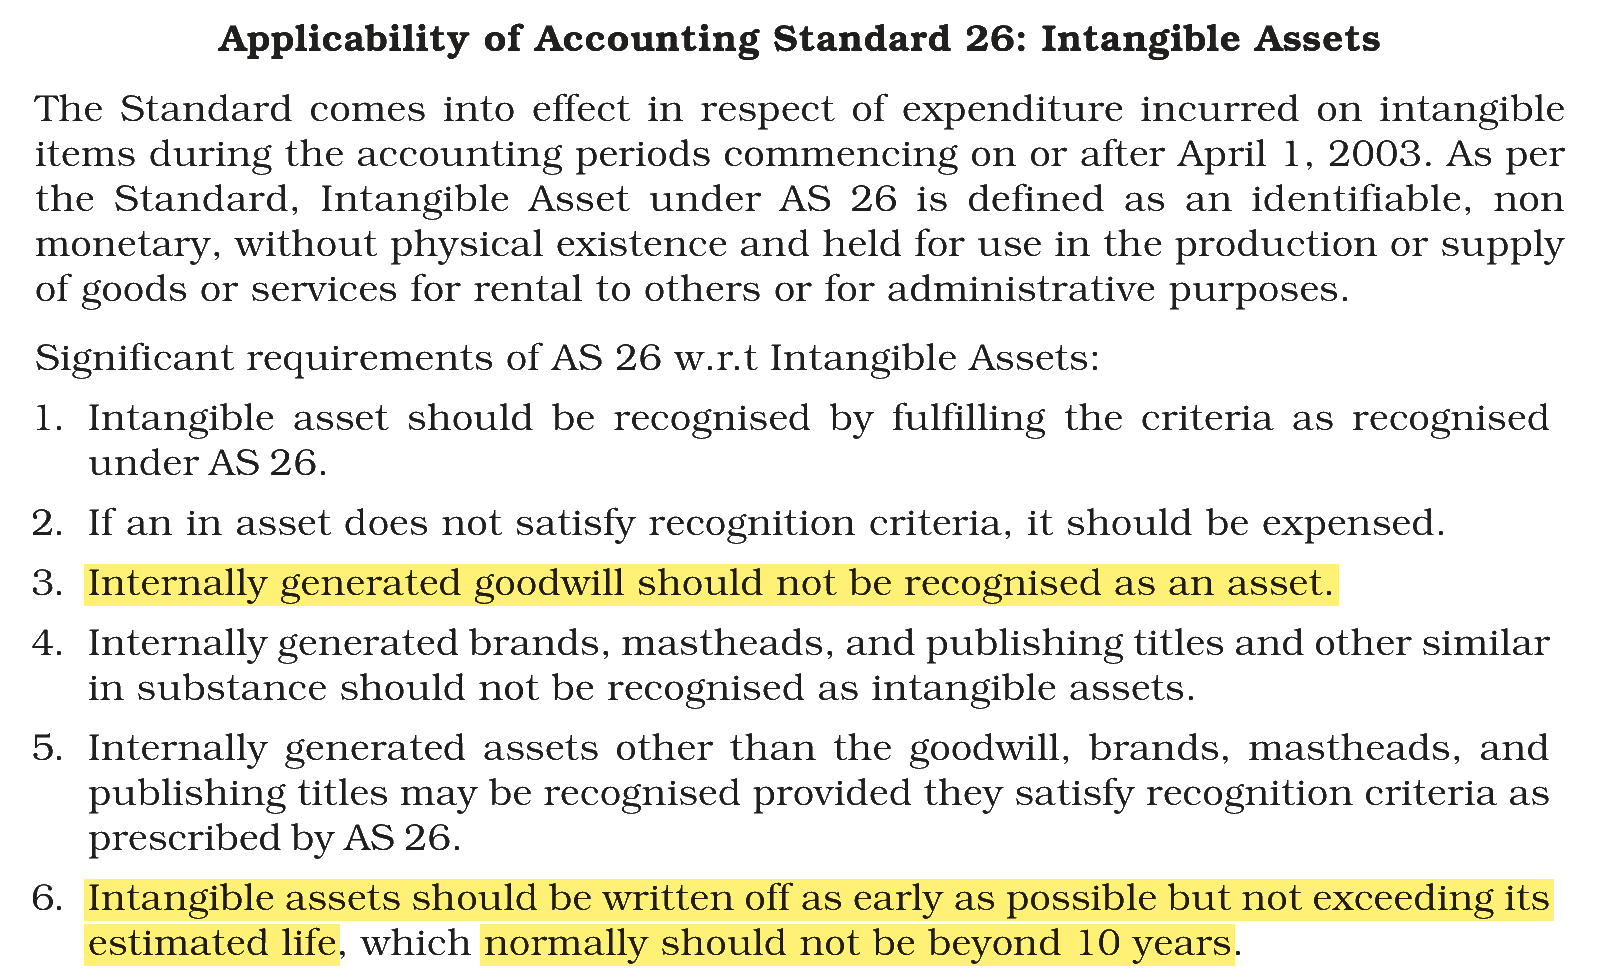
According to AS-26 on Intangible Assets.
(A) Internally generated goodwill should not be recognised as an asset
(B) Self generated goodwill is accounted for in the books and shown as asset
(C) Intangible assets should be written off as early as possible but not exceeding its estimated life.
(D) Purchased goodwill is not recognised as asset
(E) Can be written off even beyond 10 years depending upon the nature of asset
Choose the correct answer from the options given below.
Answer & explanation
Correct answer: option 4
The correct answer is Option (4) → (A) and (C) only
AS-26 deals with when goodwill and other intangible assets may be shown as assets and how long they may stay in the books.
(A) Internally generated goodwill should not be recognised as an asset — True. Self-generated goodwill cannot be measured reliably.
(B) Self generated goodwill is accounted for in the books and shown as asset — False. It is not accounted for or shown as an asset.
(C) Intangible assets should be written off as early as possible but not exceeding its estimated life. — True. This is the AS-26 rule on writing off.
(D) Purchased goodwill is not recognised as asset — False. Purchased goodwill may be shown as an asset, because a price was paid for it.
(E) Can be written off even beyond 10 years depending upon the nature of asset — False. The estimated life normally should not be beyond 10 years.
NCERT (2026-27 edition):
NCERT (2026-27 edition): |