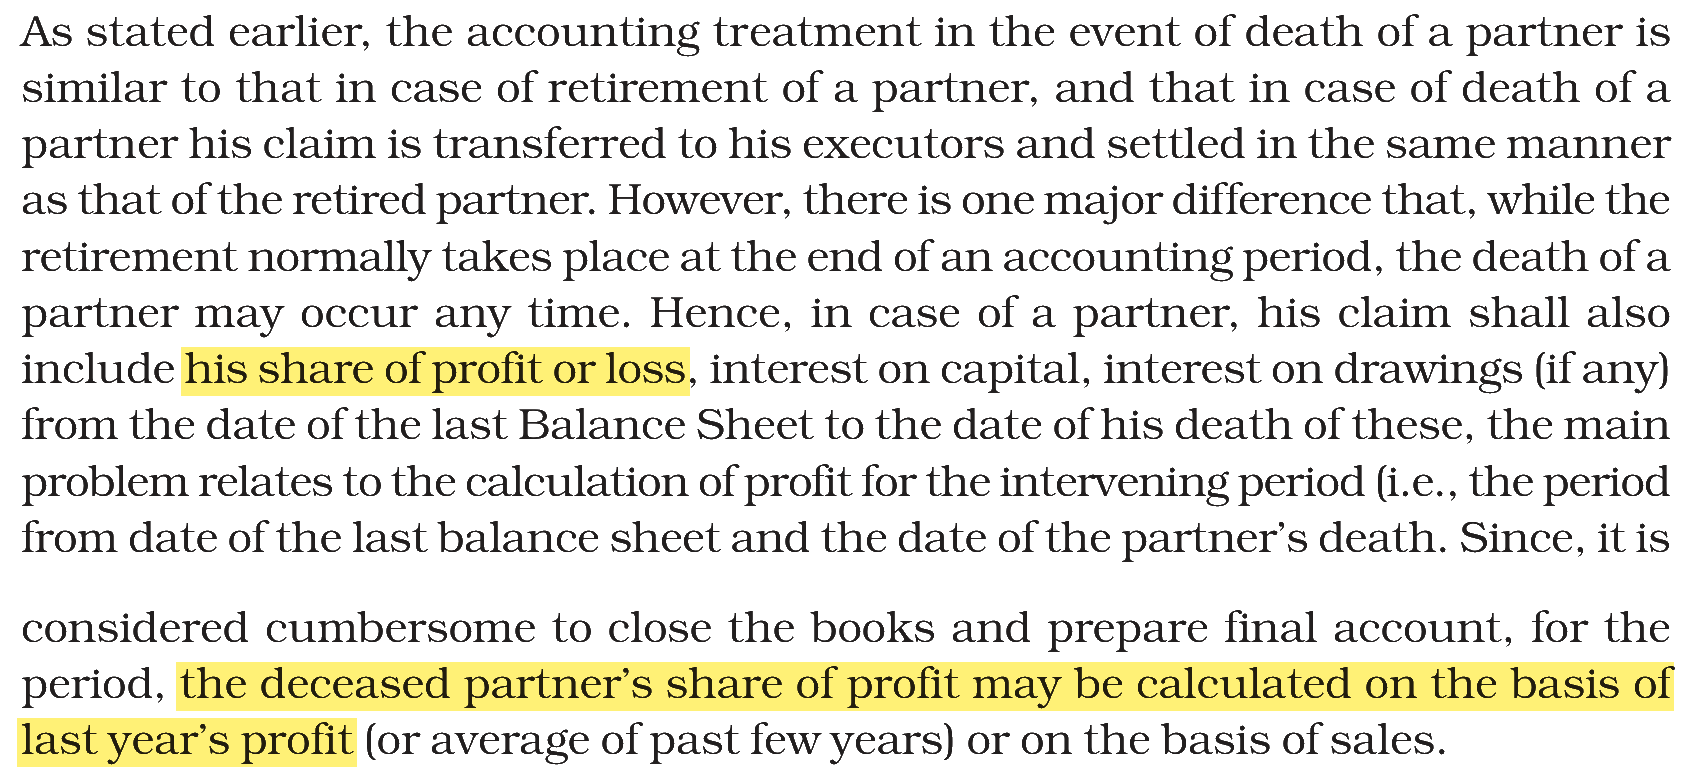
Share of loss of deceased partner, calculated on the basis of previous years profit is:
Answer & explanation
Correct answer: option 2
The correct answer is Option (2) → Debited to his capital account
A deceased partner shares the result of the firm up to the date of his death. When the previous year’s figures show a loss, his share of that loss is a deduction from what is due to him, so it is debited to his capital account. The other side of the entry goes to the Profit and Loss Suspense Account, which is credited and later closed to the gaining partners’ capital accounts.
Why the other options are incorrect
Option (1) Credited to his capital account — Incorrect. A capital account is credited with a share of profit; a share of loss reduces his claim.
Option (3) Debited to profit and loss suspense account — Incorrect. The suspense account is debited when the deceased partner gets a share of profit; for a share of loss the entry is reversed and the suspense account is credited.
Option (4) Debited to profit and loss account — Incorrect. The share for the broken period is not put through the Profit and Loss Account; it goes through the Profit and Loss Suspense Account.
NCERT (2026-27 edition): NCERT (2026-27 edition):
|