Match List I with List II
| List I | List II |
| A. Excess of purchase consideration over value of net assets |
I. Issue debentures as collateral security |
| B. Excess of net assets over purchase consideration | II. Goodwill |
| C. Debenture suspense Account | III. Issue of debentures for consideration other than cash |
| D. Assets received against debentures | IV. Capital reserve |
Choose the correct answer from the options given below:
Answer & explanation
Correct answer: option 2
The correct answer is Option (2) → A-II, B-IV, C-I, D-III
A. Excess of purchase consideration over value of net assets — this matches II. Goodwill. Paying more than the net assets are worth means paying for goodwill, which is debited.
B. Excess of net assets over purchase consideration — this matches IV. Capital reserve. Getting net assets for less than their value is a capital profit, credited to capital reserve.
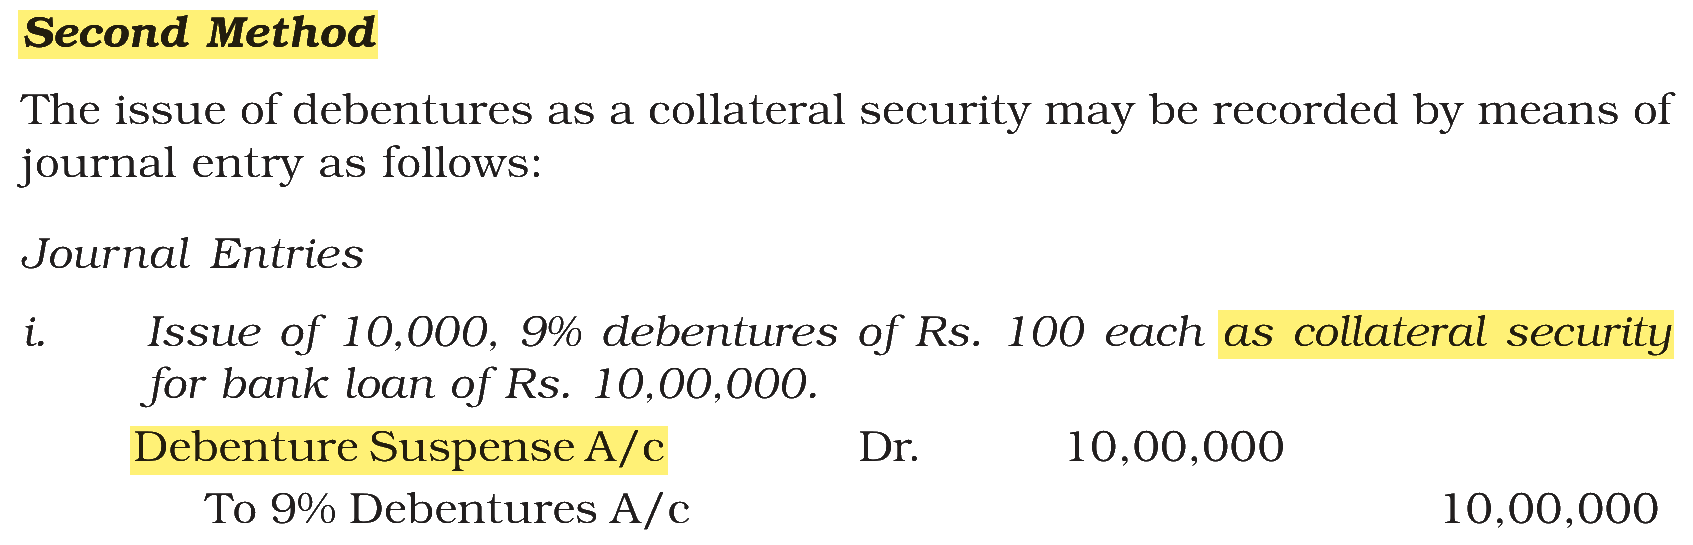
C. Debenture suspense Account — this matches I. Issue debentures as collateral security. When debentures issued as collateral security are recorded in the books, Debenture Suspense Account is debited and the Debentures Account credited.
D. Assets received against debentures — this matches III. Issue of debentures for consideration other than cash. Debentures issued to a vendor in payment for assets are issued for consideration other than cash.
NCERT (2026-27 edition): NCERT (2026-27 edition):
NCERT (2026-27 edition): |