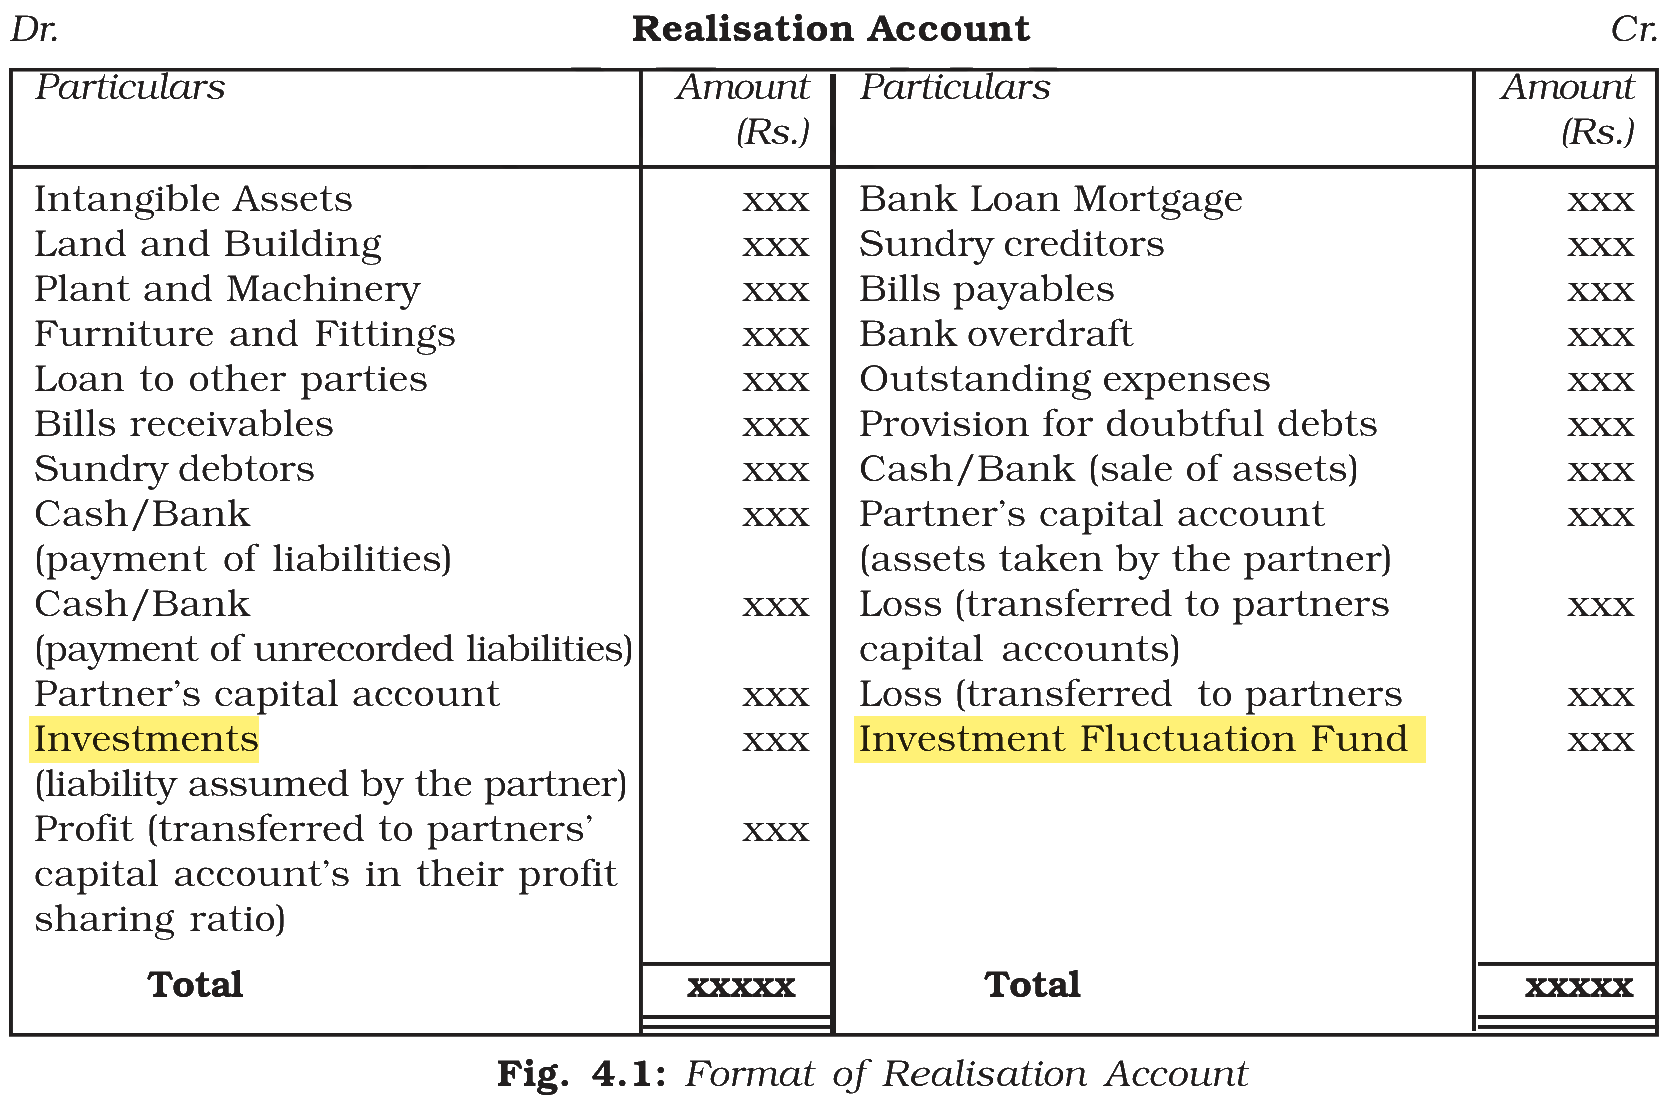
On dissolution of a firm, Investment and Investment Fluctuation Fund appeared in the balance sheet. These will be transferred to:
Answer & explanation
Correct answer: option 3
The correct answer is Option (3) → Investment on the debit side of Realisation account and Investment Fluctuation Fund on the credit side of Realisation account
On dissolution, every asset except cash and bank is closed by transferring it to the debit of Realisation Account at its book value, and every outside liability goes to its credit. An Investment Fluctuation Fund is kept only to meet a fall in the value of the investments, so it is set against them and is credited to Realisation Account. The account then shows the true gain or loss when the investments are realised.
Why the other options are incorrect
Option (1) Investment on the credit side of Realisation account and Investment Fluctuation Fund on the debit side of Realisation account — Incorrect. Both sides are reversed: an asset is debited and the fund set against it is credited.
Option (2) Investment on the debit side of Realisation account and Investment Fluctuation Fund on the credit side of partners’ capital account — Incorrect. The investment side is right, but the fund belongs with the investment it covers and goes to Realisation Account. Only the part not needed would reach the partners, through the realisation gain.
Option (4) Difference between Investment and Investment Fluctuation Fund on the debit side of Realisation account — Incorrect. Each balance is transferred at its own full amount; the two are not netted into one figure.
NCERT (2026-27 edition):
|