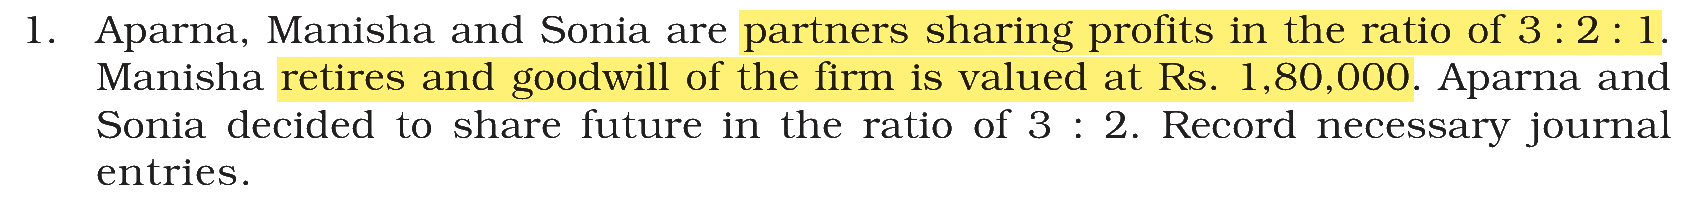
A, B and C are partners in a firm sharing profits in the ratio of 3:2:1. Firm is maintaining fixed capital accounts. B retired and the value of goodwill of the firm is valued at Rs. 1,80,000.
The journal entry for adjustment of goodwill will be :
Answer & explanation
Correct answer: option 2
The correct answer is Option (2) → A’s Current A/c Dr. Rs. 45,000 and C’s Current A/c Dr. Rs. 15,000, To B’s Current A/c Rs. 60,000
Under the fixed capital method, capital accounts change only when capital is brought in or withdrawn by agreement. Every other adjustment, goodwill included, passes through the partners’ current accounts. The continuing partners compensate B for his share of goodwill in their gaining ratio.
B’s share of goodwill = Rs. 1,80,000 × 2/6 = Rs. 60,000
No new ratio is given, so A and C take over B’s share in their old ratio of 3:1, which is their gaining ratio
A pays Rs. 60,000 × 3/4 = Rs. 45,000
C pays Rs. 60,000 × 1/4 = Rs. 15,000
The credit goes to B’s Current A/c as well, since B’s capital is also fixed.
Note: NTA picked this question from an NCERT (2026-27) exercise and changed the figures. Do not ignore NCERT while practising numericals.
NCERT (2026-27 edition):
|