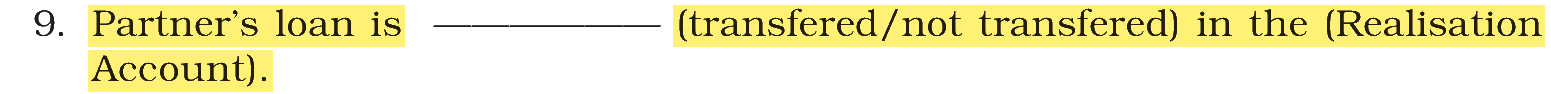For which of the following, situations "No entry" will be passed at the time of Dissolution of firm when all the assets and Liabilities were already transferred.
A. Creditors of ₹50,000 were settled by giving stock of ₹60,000 in full settlement.
B. Loan to B of ₹ 60,000 was settled at ₹55,000 (B is a partner).
C. Realisation expense amounted to ₹5,000. Debtor of ₹ 8,000 paid these expenses in full settlement
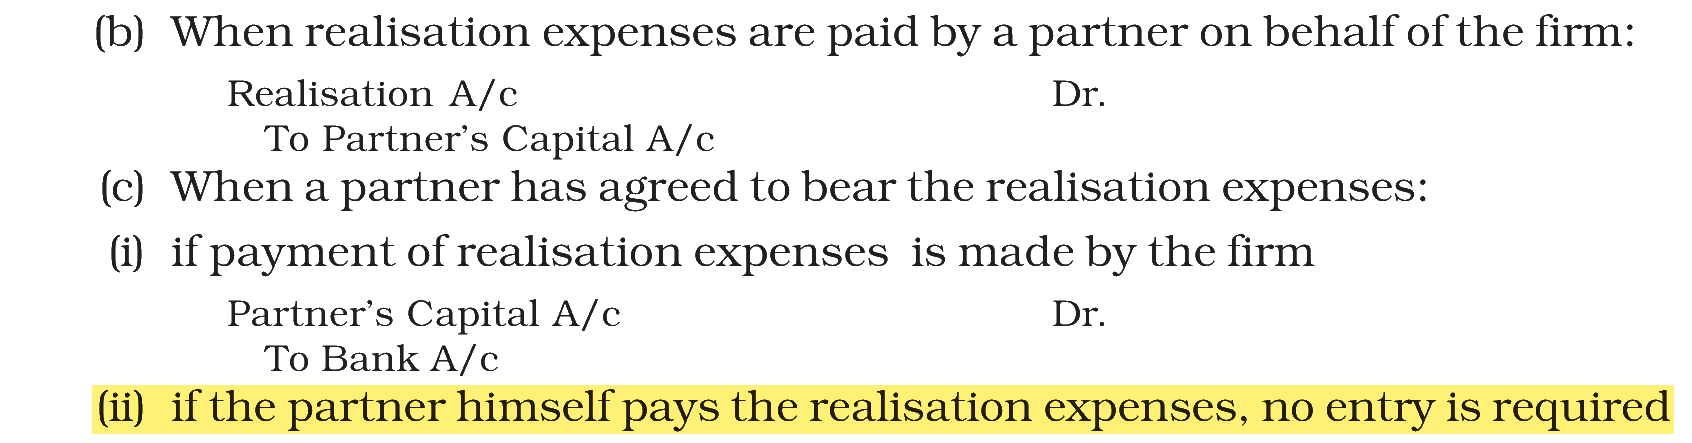
D. Realisation expenses amounted to ₹10,000 were to be borne by C, a partner and were paid by him personally.
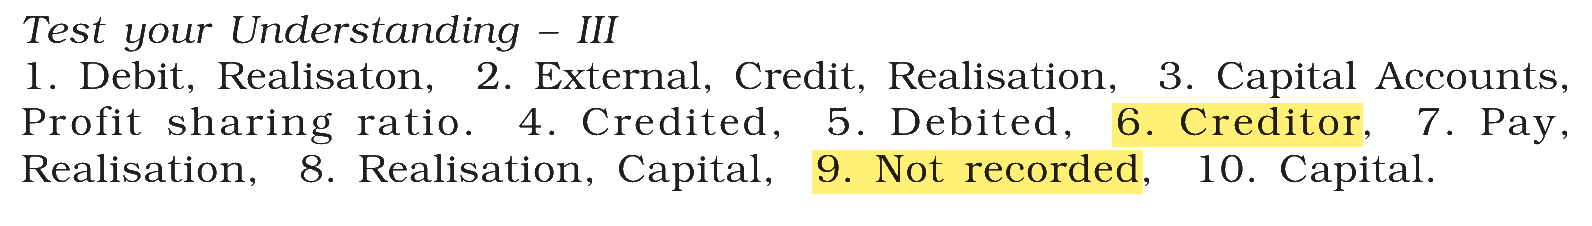
E. A's Loan to firm of ₹25,000 was settled by giving him furniture of same amount
Choose the correct answer from the options given below:
Answer & explanation
Correct answer: option 2
The correct answer is Option (2) → A, C and D only
Once all assets and outside liabilities stand in the Realisation Account, no entry is needed where an asset settles a liability directly, or where a partner both bears and pays an expense himself.
A. Creditors of ₹50,000 were settled by giving stock of ₹60,000 in full settlement. — Correct. No entry: the creditor accepts an asset in full settlement; no cash moves.
B. Loan to B of ₹ 60,000 was settled at ₹55,000 (B is a partner). — Incorrect. An entry is needed: a loan to a partner is not in the Realisation Account; its settlement is recorded.
C. Realisation expense amounted to ₹5,000. Debtor of ₹ 8,000 paid these expenses in full settlement — Correct. No entry: the debtor (already in the Realisation Account) settles his debt by paying the firm's expense directly; the firm neither receives nor pays any cash.
D. Realisation expenses amounted to ₹10,000 were to be borne by C, a partner and were paid by him personally. — Correct. No entry: the partner who is to bear the expense pays it himself.
E. A's Loan to firm of ₹25,000 was settled by giving him furniture of same amount — Incorrect. An entry is needed: a partner's loan is not in the Realisation Account, so the asset given is recorded against it.
NCERT (2026-27 edition): NCERT (2026-27 edition):
NCERT (2026-27 edition):
NCERT (2026-27 edition):
|