Which of the following provisions of Partnership Act is not relevant for accounting?
Answer & explanation
Correct answer: option 3
The correct answer is Option (3) → Private assets of competitors
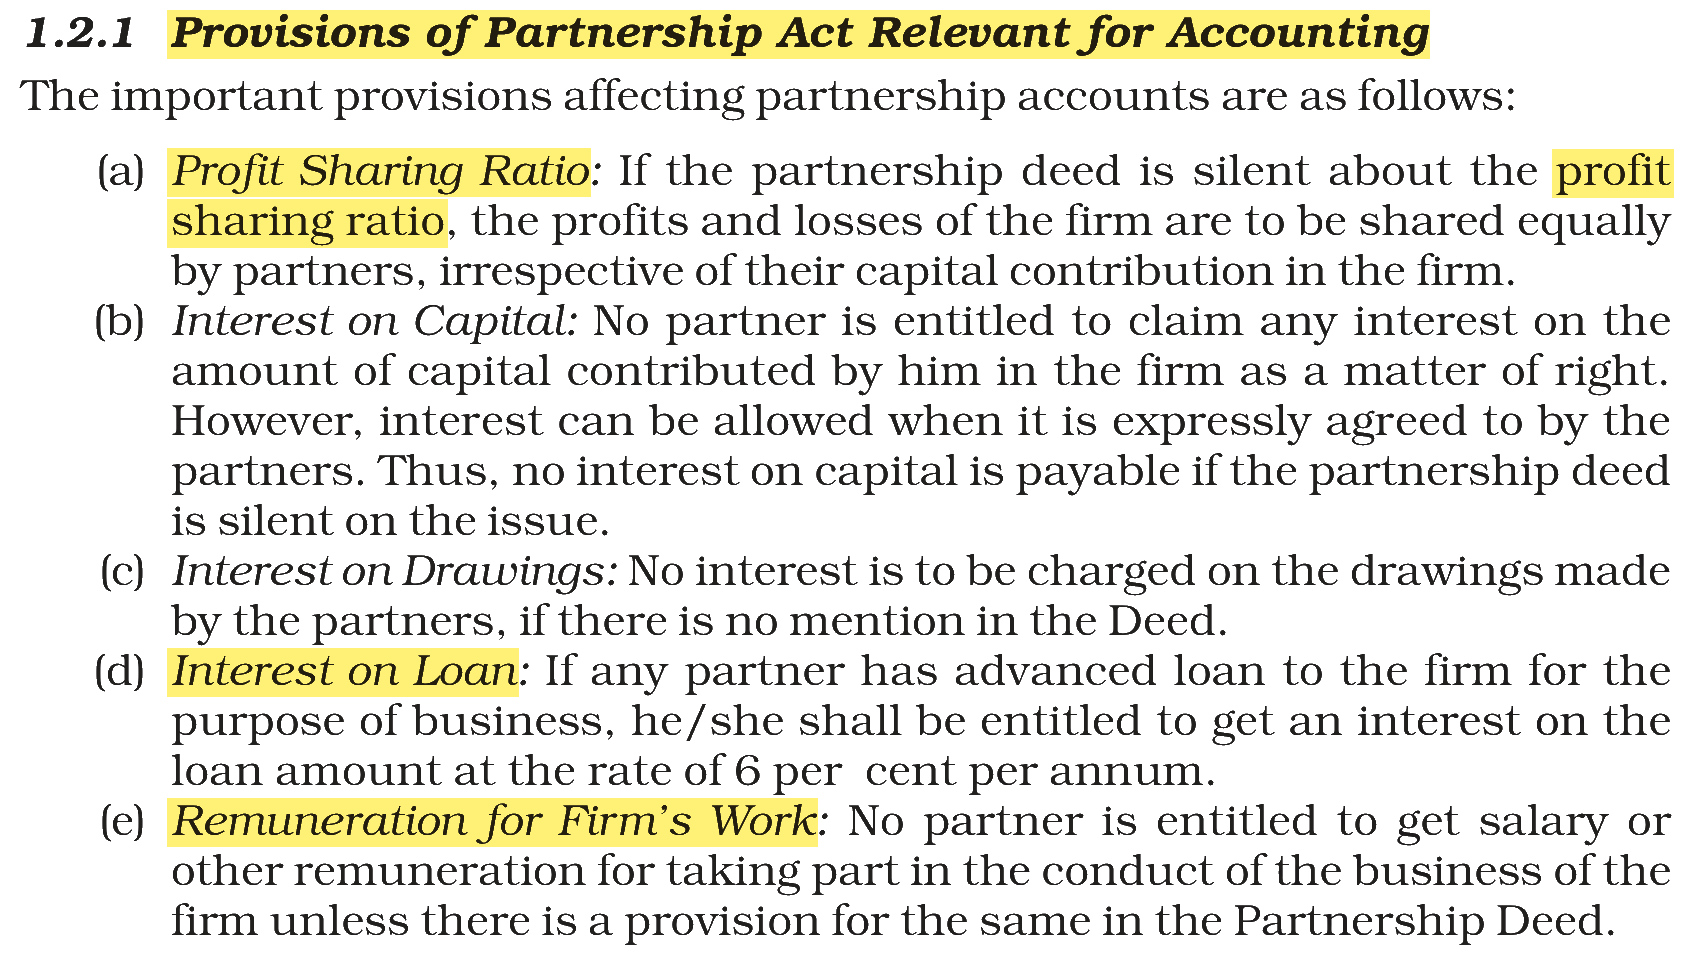
Where the partnership deed is silent, the Indian Partnership Act, 1932 fills the gap on the points that affect the firm’s accounts: profit sharing ratio, interest on capital, interest on drawings, interest on loan and remuneration for firm’s work. The private assets of a competitor are not the firm’s business at all, so the Act lays down no rule about them.
Option (1) Profit Sharing Ratio — A provision relevant for accounting. If the deed is silent, profits and losses are shared equally, whatever the capital of each partner.
Option (2) Interest on Loan — A provision relevant for accounting. A partner who lends money to the firm gets interest at 6% per annum on it.
Option (4) Remuneration for Firm’s Work — A provision relevant for accounting. No salary or other remuneration is allowed to a partner for working in the firm unless the deed provides for it.
NCERT (2026-27 edition):
|