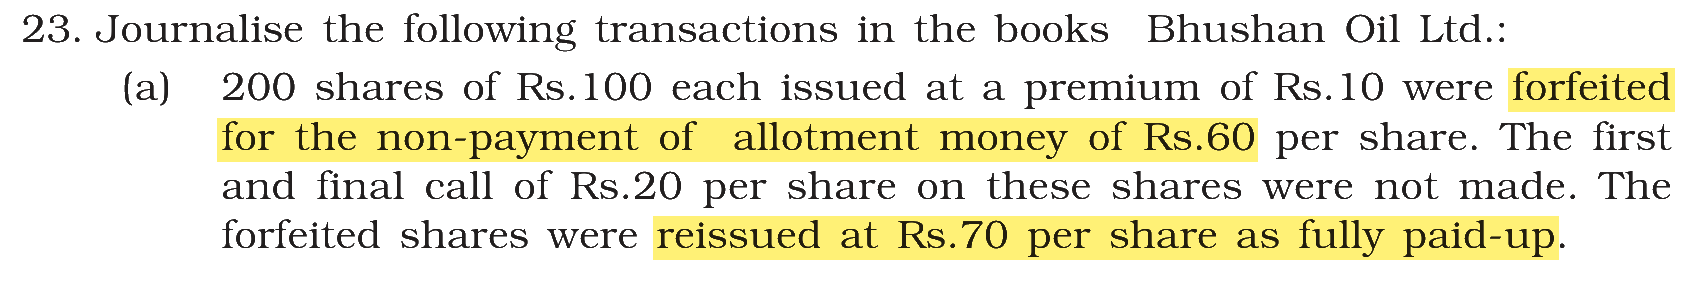
200 shares of Rs. 100 each were forfeited for the non-payment of allotment money of Rs. 60 per share. The first and final call of Rs. 20 per share on these shares was not made. The forfeited shares were reissued at Rs. 80 per share as fully paid-up. Calculate the amount of share forfeited account transferred to capital reserve.
Answer & explanation
Correct answer: option 4
The correct answer is Option (4) → Nil
On forfeiture, the amount already received on the shares is credited to Share Forfeiture Account. On reissue, any discount allowed is met out of that forfeited amount, and only what is left is a gain, transferred to Capital Reserve.
Called up per share = Rs. 100 − Rs. 20 (call not made) = Rs. 80
Amount received per share = Rs. 80 − Rs. 60 (allotment unpaid) = Rs. 20
Share Forfeiture A/c credited = 200 × Rs. 20 = Rs. 4,000
Discount on reissue = Rs. 100 − Rs. 80 = Rs. 20 per share
Discount on 200 shares = 200 × Rs. 20 = Rs. 4,000, debited to Share Forfeiture A/c
Balance left for Capital Reserve = Rs. 4,000 − Rs. 4,000 = Nil
The shares are reissued as fully paid at Rs. 80, so the whole forfeited amount goes to cover the Rs. 20 discount and nothing is left over.
Note: NTA picked this question from an NCERT (2026-27) exercise and changed the figures. Do not ignore NCERT while practising numericals.
NCERT (2026-27 edition):
|