Raman and Naman were in partnership sharing profit and losses as 3: 2. Their partnership firm was dissolved on 31 March 2022. On the date of dissolution, Naman's loan was ₹20,000. Naman agreed to take stock (already transferred to Realisation A/c) of ₹15,000 at ₹18,000 and balance in cash for the settlement of the loan.
Journal Entry for the above transaction is:
Answer & explanation
Correct answer: option 1
The correct answer is Option (1) → Naman’s Loan A/c Dr ₹20,000 To Realisation A/c ₹18,000 To cash A/c ₹2,000 (Settlement of loan)
Naman takes the stock at the agreed value of ₹18,000 against his loan of ₹20,000, and the balance of ₹2,000 is paid to him in cash. The stock is already in the Realisation Account, so the Realisation Account is credited with the value at which he takes it over (₹18,000), not its book value (₹15,000).
Naman’s Loan A/c Dr. ₹20,000
To Realisation A/c ₹18,000
To Cash A/c ₹2,000
(Settlement of loan)
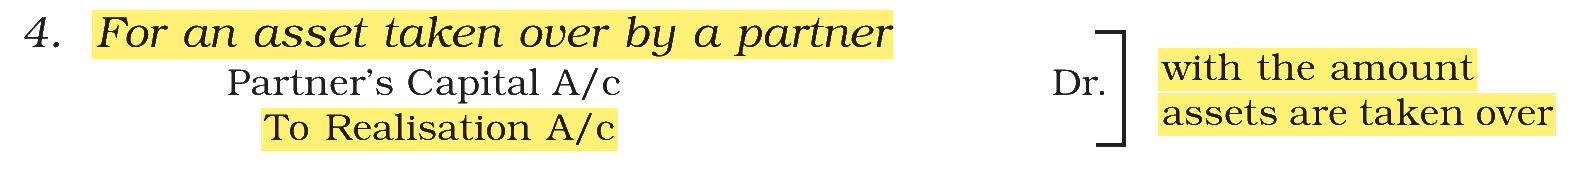
When a partner takes over an asset, the book entry is normally Partner’s Capital A/c Dr. To Realisation A/c; here the asset is taken against his loan, so his Loan Account is debited instead.
NCERT (2026-27 edition):
|