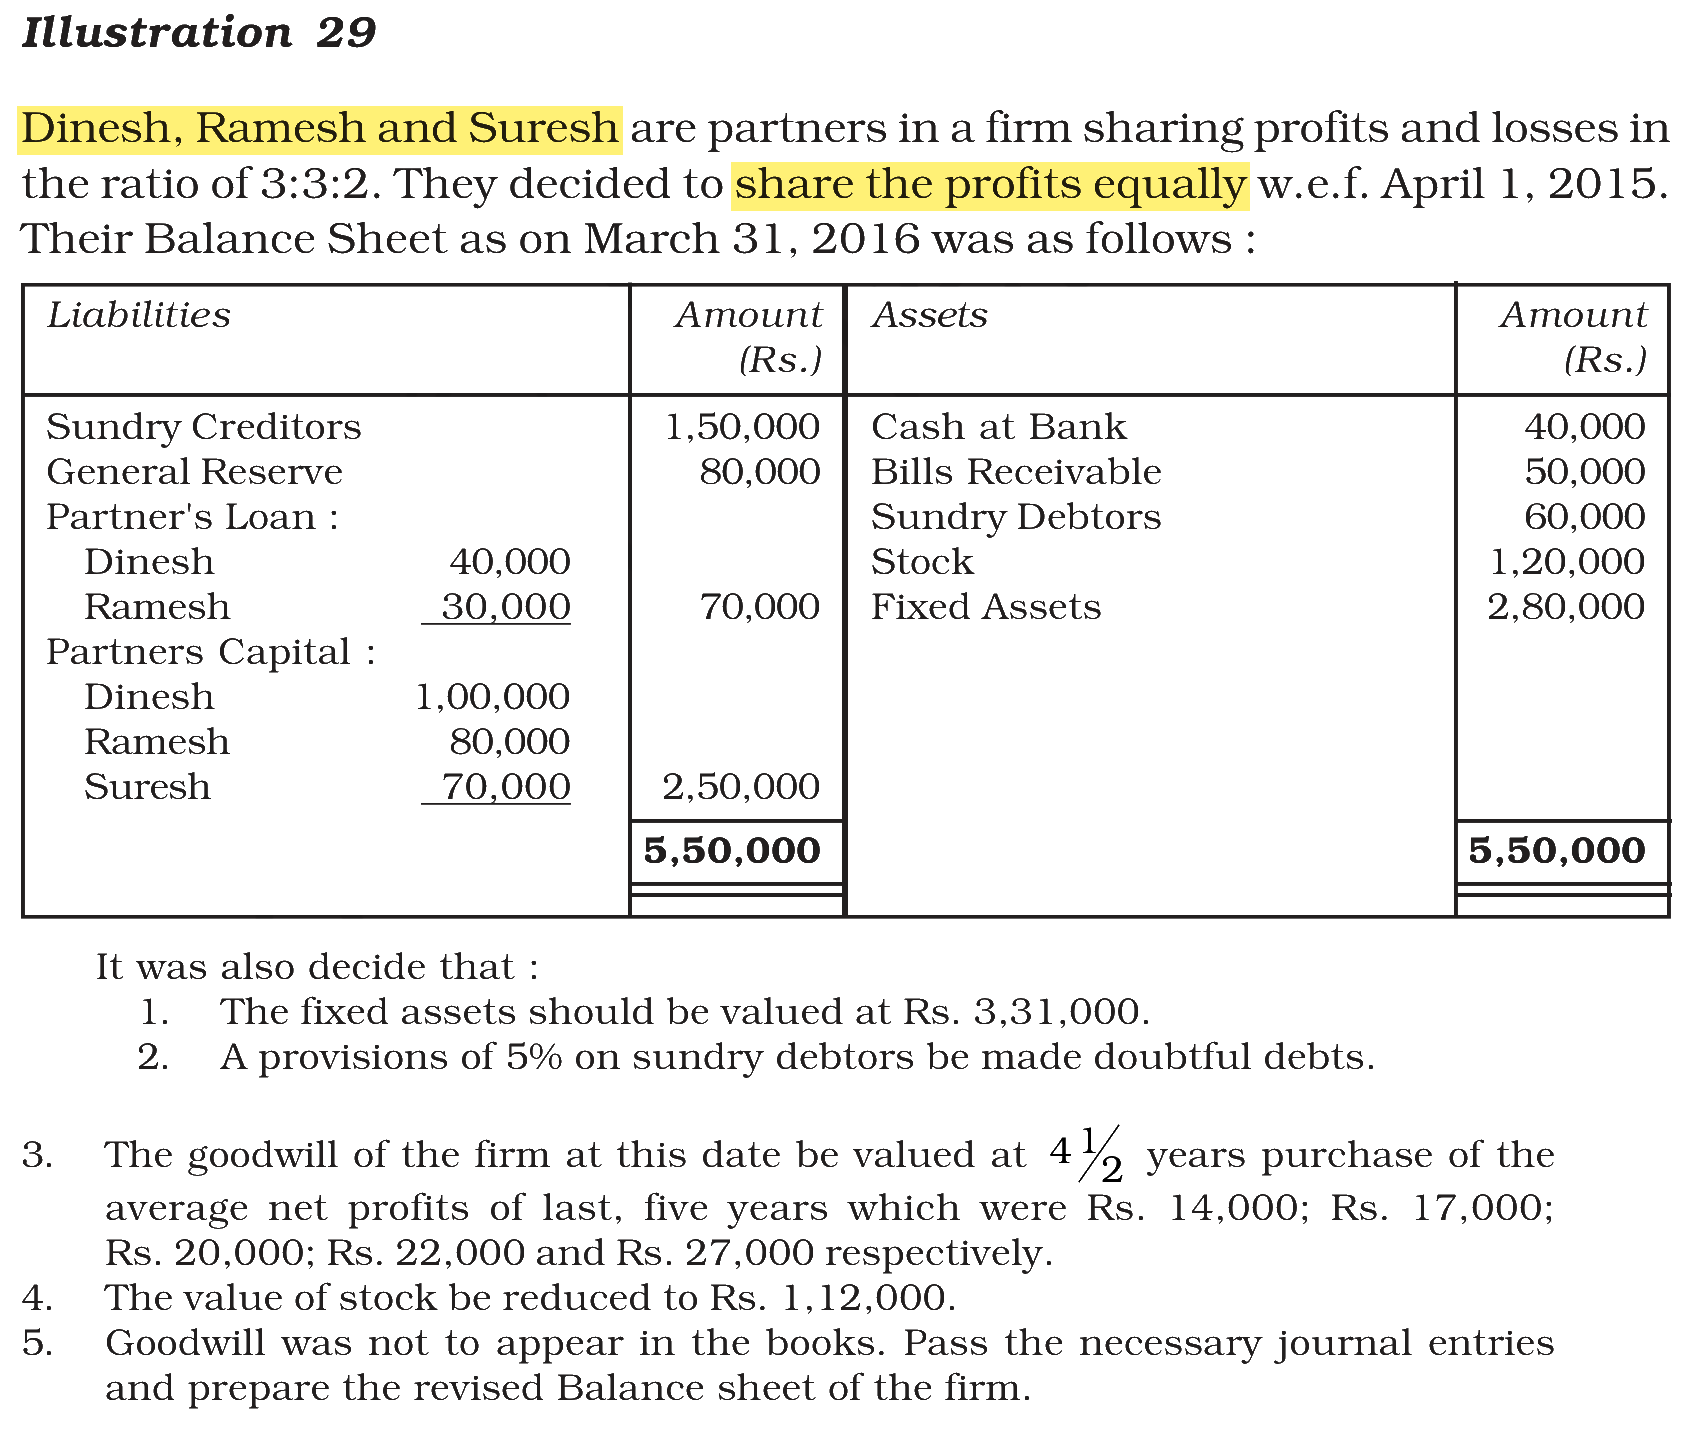
Dinesh, Ramesh and Suresh are partners in a firm sharing profits and losses in the ratio of 3:3:2. They decided to share the profits equally w.e.f. April 1, 2015.
Match List-I with List-II
| List-I Events/ Transactions | List-II Accounting Treatment | ||
|---|---|---|---|
| (A) | Profit on revaluation Rs. 40,000 | (I) | Dinesh's Capital A/c will be credited by Rs. 25,000 |
| (B) | General reserve of Rs. 60,000 distributed. | (II) | Dinesh's Capital A/c will be credited by Rs. 20,000 |
| (C) | Goodwill Rs. 6,00,000 adjusted in partners' capital | (III) | Dinesh's Capital A/c will be credited by Rs. 22,500 |
| (D) | Workmen Compensation Reserve Rs. 4,80,000 adjusted in partners' capital | (IV) | Dinesh's Capital A/c will be credited by Rs. 15000 |
Choose the correct answer from the options given below:
Answer & explanation
Correct answer: option 4
The correct answer is Option (4) → (A) - (IV), (B) - (III), (C) - (I), (D) - (II)
Dinesh’s old share is 3/8 (3 : 3 : 2) and his new share, with equal sharing, is 1/3. Revaluation profit and reserves belong to the partners in the old ratio, while goodwill is adjusted through each partner’s sacrifice or gain.
Dinesh’s sacrifice = 3/8 − 1/3 = 9/24 − 8/24 = 1/24
(A) Profit on revaluation Rs. 40,000 — this matches (IV) Dinesh’s Capital A/c will be credited by Rs. 15000. A revaluation gain goes to the partners in the old ratio.
3/8 × Rs. 40,000 = Rs. 15,000
(B) General reserve of Rs. 60,000 distributed. — this matches (III) Dinesh’s Capital A/c will be credited by Rs. 22,500. An accumulated reserve is shared in the old ratio.
3/8 × Rs. 60,000 = Rs. 22,500
(C) Goodwill Rs. 6,00,000 adjusted in partners’ capital — this matches (I) Dinesh’s Capital A/c will be credited by Rs. 25,000. Dinesh is a sacrificing partner, so he is credited for the share he gives up.
1/24 × Rs. 6,00,000 = Rs. 25,000
(D) Workmen Compensation Reserve Rs. 4,80,000 adjusted in partners’ capital — this matches (II) Dinesh’s Capital A/c will be credited by Rs. 20,000. “Adjusted” means the reserve stays in the books: each partner is credited in the old ratio and debited in the new ratio, so only the net effect reaches the capital account.
Credit in old ratio = 3/8 × Rs. 4,80,000 = Rs. 1,80,000
Debit in new ratio = 1/3 × Rs. 4,80,000 = Rs. 1,60,000
Net credit to Dinesh = Rs. 20,000
Note: NTA picked this question from an NCERT (2026-27) illustration and changed the figures. Do not ignore NCERT while practising numericals.
NCERT (2026-27 edition):
|